...

News

China Micro-Short Drama Regulation: Key Compliance and Global Expansion Issues for AI Short Drama Companies

On July 31, 2026, the National Radio and Television Administration (NRTA) officially issued Order No. 16, the Measures for the Administration of the Development of Micro-Short Dramas, which takes effect on September 1, 2026. This is China’s first departmental regulation dedicated specifically to micro-short dramas. The new rules set out requirements for classified management, filing and public announcement, distribution licensing, content review, broadcasting management, labeling of AI-generated content, and overseas broadcasting.

This article examines the key issues that AI short drama companies should focus on under the new regulation.
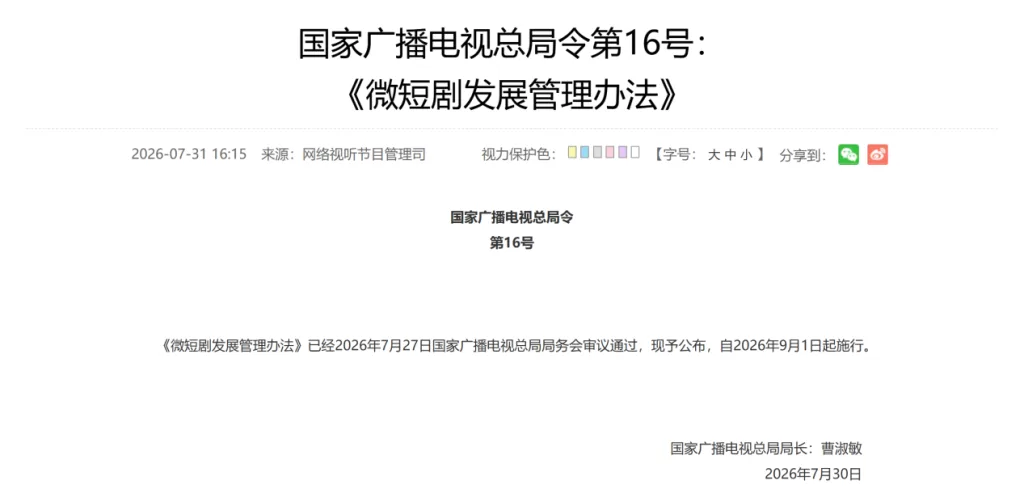
(Source: National Radio and Television Administration (NRTA))


I. Three-Tier Classified Management: How Should AI Short Dramas Be Categorized?

The new regulation divides micro-short dramas into three categories based on investment amount and subject matter, applying differentiated regulation:

CategoryCriteriaRegulatory Requirements
Category IRelatively large investment amount, or involving special subject matters such as politics, military, diplomacy, national security, united front, ethnicity, religion, judiciary, public security, etc.Filing and public announcement + content review + Micro-Short Drama Distribution License
Category IIGeneral subject matter with relatively moderate investmentFiling and public announcement + content review + approval document from provincial radio and TV authorities by reference
Category IIIGeneral subject matter with relatively low investmentPre-broadcast review by the broadcasting entity + program number labeling

AI short drama companies must first clarify their content positioning. At present, most AI-generated short dramas have relatively low production costs, but this does not automatically mean they fall into Category III. Project classification still depends on a concrete assessment of investment amount, subject matter, and other factors. For Category II micro-short dramas, the new regulation also makes clear that provincial radio and TV authorities may formulate local implementation rules by reference to the filing and public announcement system for Category I micro-short dramas.

Legal Recommendations:
Prepare a list of existing and in-production projects, and classify them by investment amount, subject matter, production entity, production location, broadcasting platform, and domestic/overseas broadcasting. This will help identify the compliance path and time cost for each project. For AI short drama projects that plan to bring in foreign capital or involve co-production, it is especially important to clarify the regulatory classification at the project initiation stage, so as to avoid compliance issues that could affect cross-border capital flows or cooperation.


II. Special Rules for AI Short Dramas: Labeling Obligations, Content Red Lines, and Algorithm Governance

1. Labeling obligation: Article 34 of the new regulation expressly provides: “For micro-short dramas generated or produced using artificial intelligence technology, the production entity and the broadcasting entity shall comply with relevant national provisions and, in accordance with relevant rules, add a conspicuous notice label in each episode.”

2. Content red lines: Article 25 lists 11 prohibited categories. Micro-short dramas may not contain content that endangers national security or national unity, incites ethnic hatred, denigrates China’s excellent traditional culture, incites disruption of national religious policy, infringes on the lawful rights and interests or physical and mental health of minors, damages ecological and environmental protection, promotes obscenity, gambling, drug use, money worship, or extravagance, or depicts violence and terror.

3. Algorithm governance: “Addictive” features have also become a regulatory focus. Article 37 requires broadcasting entities to “regularly review, evaluate, and verify algorithm mechanisms,” give priority to recommending high-quality content, and refrain from using algorithm models that induce addiction or excessive consumption.

AI short dramas face “dual compliance” pressure: they must meet the general content standards for micro-short dramas and also satisfy the special disclosure requirements for AI-generated content. In practice, AI-generated historical figures and fictional plots can easily cross red lines such as “distorting history” or “desecrating heroes and martyrs.” Companies need to establish an AI content pre-review mechanism and cannot rely solely on technical review.

Legal Recommendations:

  1. Embed an “AI-generated” watermark or label during the final production stage to ensure the label is conspicuous.
  2. Establish a dual human + AI content review process, focusing on sensitive scenes involving history, ethnicity, religion, and minors.
  3. Retain full-chain evidence, including AI training data sources, generation parameters, and human modification records, for regulatory inspection.
(Source: Online Audio-Visual Program Review System)

III. Heavier Platform Responsibility: Stricter Review by Broadcasting Entities and Higher Market Entry Thresholds

The new regulation imposes strict primary responsibility on broadcasting entities:

  1. Before broadcasting Category I and Category II micro-short dramas, they must verify the Micro-Short Drama Distribution License or approval document.
  2. For Category III micro-short dramas, the broadcasting entity must perform content management duties, conduct pre-broadcast review, and label the program number.
  3. Establish an editor-in-chief content responsibility system and a full-process accountability and traceability mechanism for content safety.
  4. Establish a credit evaluation system for key accounts that disseminate micro-short dramas and subject them to focused management.

Due to the special nature of AI content generation, AI short dramas may face stricter requirements in the future regarding copyright proof, AI labeling, licenses, material authorization, and manual re-review. This may lead to longer review cycles, more supplementary document requests, and an increased risk of temporary removal. This means that content compliance costs for AI short drama companies will rise significantly.

Legal Recommendations:

  1. Communicate with major broadcasting platforms in advance to understand their internal review rules and special requirements for AI content.
  2. Introduce compliance assessment at the project planning stage to avoid sunk costs caused by failed review after production is completed.
  3. Consider voluntarily applying for Category I or Category II standards for some projects. Obtaining formal permission may actually give the project priority in platform recommendations.

IV. Intellectual Property and Data Compliance: Legal Risks in AI Short Drama Content

Article 10 of the new regulation clearly states that “intellectual property related to micro-short dramas is protected by law” and that “organizations and individuals engaged in micro-short drama activities shall enhance their awareness of intellectual property.”

AI short dramas face three major legal risks in this area:

  1. Training data compliance: Have the film and television materials, scripts, novels, images, and music used in AI model training been authorized?
  2. Ownership of generated content: Who owns the copyright in AI-generated scripts, characters, and images? For example, directly uploading screenshots of popular TV dramas, celebrity photos, or anime character images and asking AI to “generate by reference.” Even if the final result is not the original image, copyright and portrait rights risks cannot be excluded.
  3. Infringement of personality rights: If AI-generated character images or voices resemble real natural persons, this may trigger infringement of portrait rights or voice rights.

Legal Recommendations:

  1. Establish a mechanism for reviewing the lawful source of training data and retain evidence of the authorization chain.
  2. Conduct a “significant difference” review of AI-generated content to avoid high similarity with real persons or existing IP.
  3. Clearly agree with AI technology suppliers on the ownership of intellectual property in generated content and the allocation of liability for infringement.

V. Global Expansion Compliance: The “Dual Threshold” of Domestic Production and Overseas Broadcasting, and Global Layout

Article 8 of the new regulation states that China “supports the creation, production, and dissemination of export-oriented micro-short dramas, facilitates the participation of overseas principal creators in the creation of micro-short dramas, and supports the simultaneous domestic and overseas broadcasting of excellent micro-short dramas.” Article 52 provides that “micro-short dramas filmed within China for overseas broadcasting shall be subject to the relevant provisions of these Measures on filing and public announcement, review, and licensing.”

This legislative attitude of “supporting global expansion but requiring compliance first” deserves close attention. Although global expansion of AI short dramas is an industry hotspot, “domestic production and overseas broadcasting” still requires domestic filing and review procedures. Content that has not obtained domestic permission may face regulatory tracing even if it is broadcast only on overseas platforms.

A deeper issue is that different jurisdictions have vastly different regulatory frameworks for AI-generated content:

JurisdictionKey Regulatory RequirementsImpact on AI Short Dramas
European UnionThe AI Act classifies AI-generated content as subject to limited transparency obligations, requiring clear labeling of AI generationAI system compliance assessment required
United StatesSome states have enacted laws requiring AI content disclosure; at the federal level, rules mainly involve consumer protection, advertising, and misleading promotionClear AI-generated labeling in content to avoid misleading consumers
Southeast AsiaStandards vary by country; some countries have no dedicated legislation, but content review is tighteningCountry-by-country assessment required; domestic version cannot simply be copied
Middle EastStrict review of religious and cultural content; AI-generated content may receive additional scrutinyLocal cultural compliance review must be conducted in advance

If companies produce content only according to domestic standards, they may face secondary compliance or even removal risks after going overseas. In particular, the “AI-generated labeling” required by the new domestic rules is converging in direction with the transparency obligations of the EU AI Act and the disclosure requirements of some U.S. states, but there may be differences in label placement, wording, and technical implementation. A direct translation of the domestic version may not satisfy overseas requirements.

Legal Recommendations:

  1. Incorporate the AI content regulatory requirements of target markets into the script and production stages, rather than simply adding labels later.
  2. After completing domestic compliance review and obtaining permission, make localized compliance adjustments for different markets, rather than releasing one version globally.
  3. For companies planning to operate overseas businesses, it is necessary to simultaneously monitor the connection between the new domestic rules and overseas investment regulatory requirements.
(Source: CCTV.com)

Conclusion

The implementation of the Measures for the Administration of the Development of Micro-Short Dramas presents both difficulties and opportunities for AI short drama companies. The difficulties lie in rising compliance costs, stricter content review, and intensified algorithm governance; the extensive growth model will be difficult to sustain. The opportunities lie in the fact that compliant companies will obtain the “credit endorsement” of formal permission and gain a first-mover advantage in platform recommendations, capital connections, and global expansion.

For AI short drama companies intending to enter overseas markets, domestic compliance permission is not only a “passport” but may also become the credit foundation for negotiating with overseas platforms and obtaining copyright procurement or co-production opportunities. Only by front-loading compliance, actively adapting, and establishing a dual-track risk control system at home and abroad can AI short drama companies stand out in the industry’s development.

About the Author
Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
Recommend
Legal Guide for the 140th Canton Fair | Legal Services and Dispute Resolution

The 140th China Import and Export Fair (Canton Fair) takes place in Guangzhou from October 15 to November 4, 2026. Bringing together thousands of international buyers and domestic exhibitors, the fair serves as a vital global trade platform.

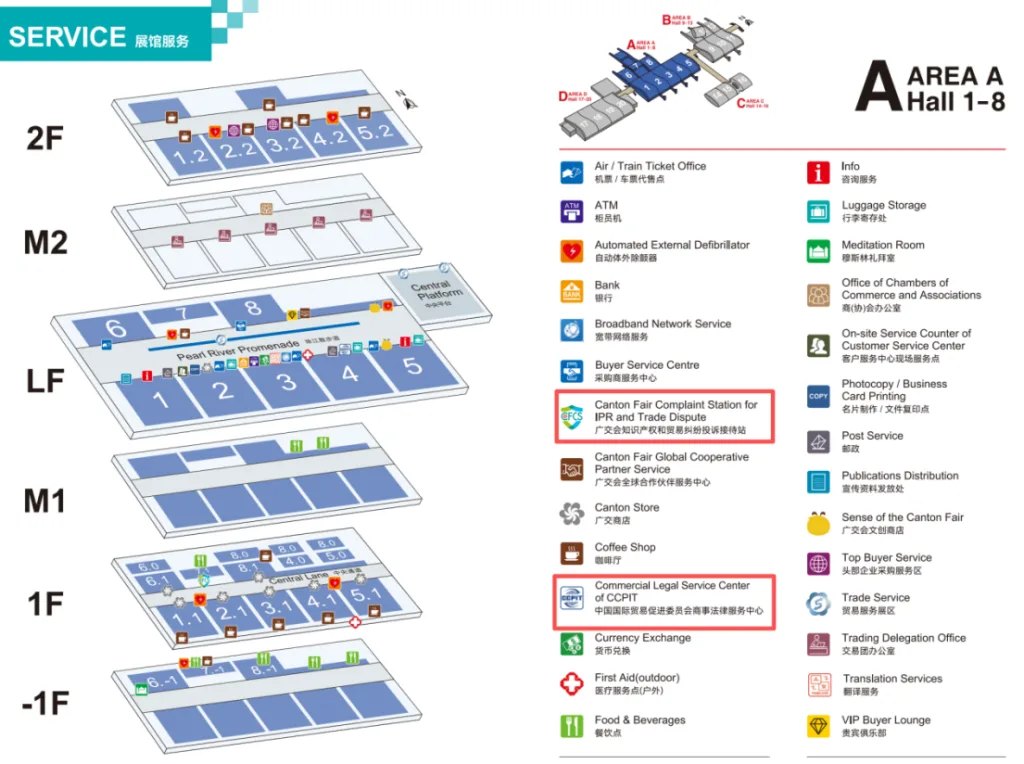
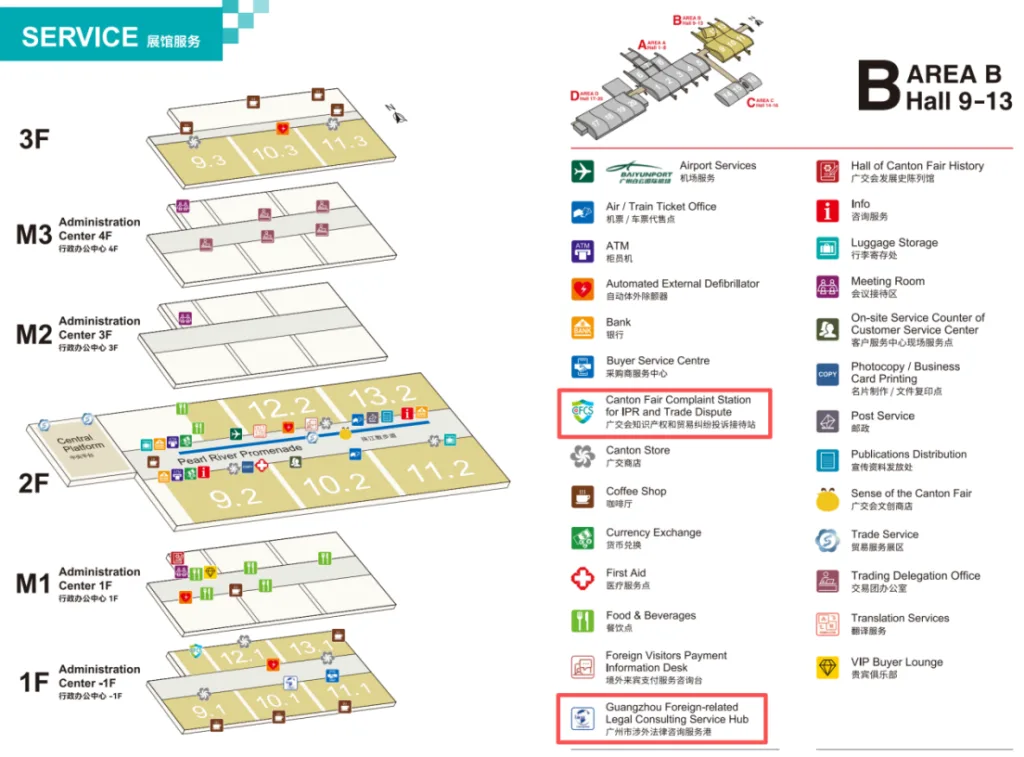
To help participants navigate legal issues and resolve commercial conflicts efficiently, this guide outlines on-site legal service stations, offline dispute resolution channels, online complaint mechanisms, and the duty schedule for Attorney Yuting Yu (Partner & Head of International Legal Affairs at Neo-Ark Law Firm), who will serve at the Guangzhou Foreign-Related Legal Advisory Service Port.

I. Three On-Site Legal Service Channels

Service StationCore Service ScopeRecommended Scenarios
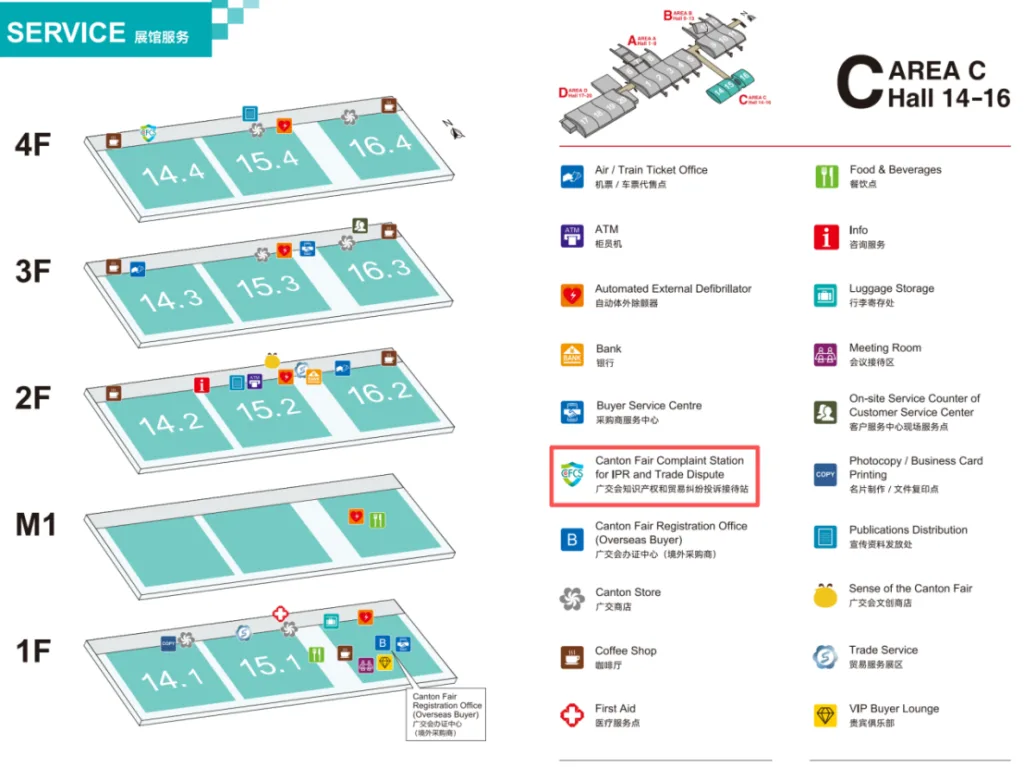
IP & Trade Dispute Complaint Station
(知识产权和贸易纠纷投诉接待站)
Processes compliant intellectual property (IP) and trade dispute complaints under official Canton Fair guidelines.On-site IP infringement allegations or trade contract disputes within Canton Fair jurisdiction.
CCPIT Commercial Legal Service Center
(中国贸促会商事法律服务中心)
Provides commercial legal counseling, contract risk assessment, and trade dispute advice.Enterprises seeking guidance on international trade laws, cross-border contracts, and commercial risk.
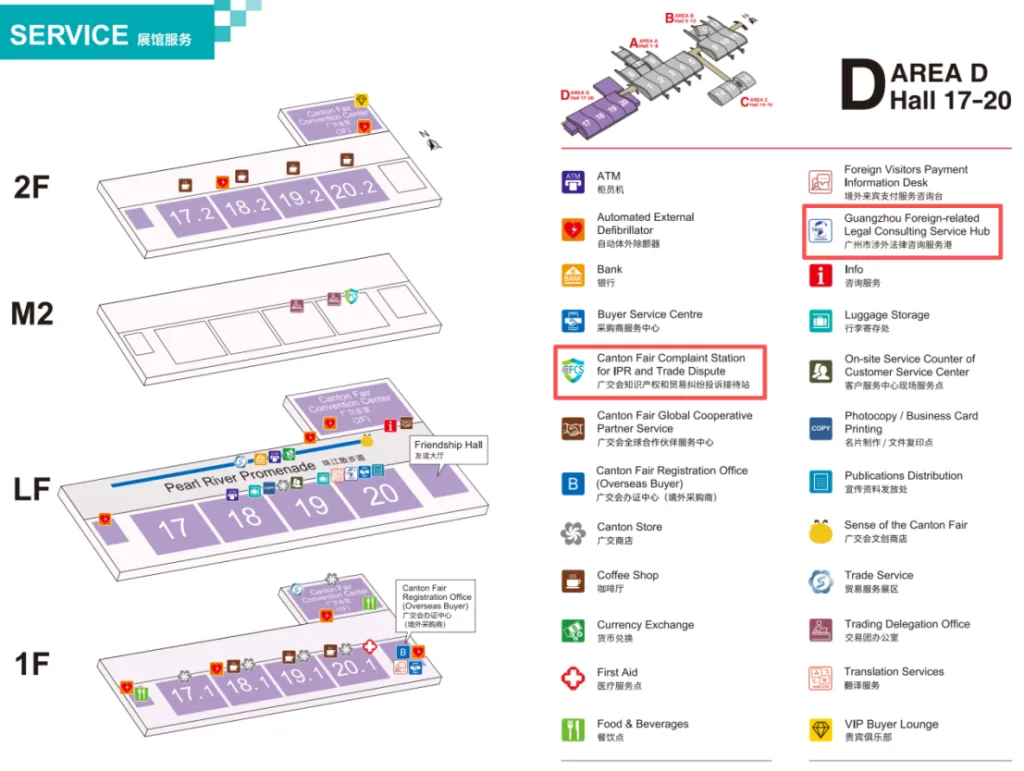
Guangzhou Foreign-Related Legal Service Port
(广州市涉外法律咨询服务港)
Connects exhibitors with cross-border legal consulting, attorney services, arbitration, notarization, mediation, and foreign law ascertainment.Overseas buyers and domestic suppliers requiring advice on governing laws, cross-border dispute resolution, or legal representation.

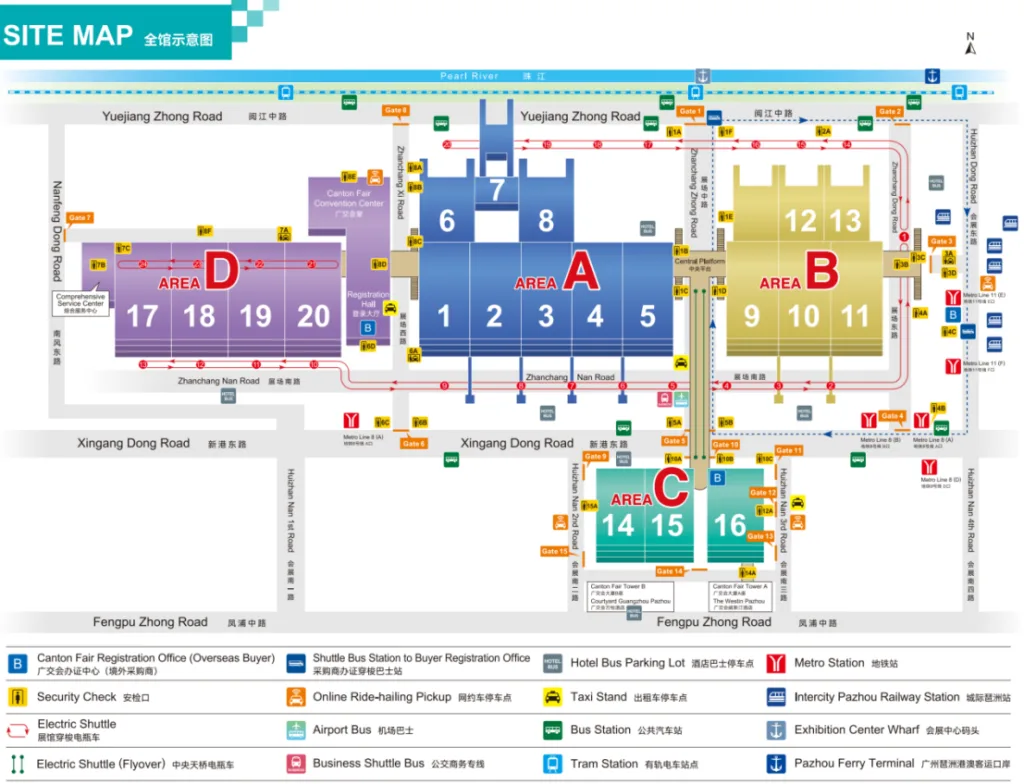
Zone Service Rules: IP and Trade Dispute Complaint Stations are stationed across Complex Areas A, B, C, and D. While Areas A and B accept both IP and trade dispute complaints, Areas C and D handle IP complaints exclusively. Trade dispute complaints occurring in Areas C or D must be submitted at the Area A or B complaint desks.

II. Offline Dispute Resolution Pathways

1. Alleged Intellectual Property (IP) Infringement

  • Recommended Desks: Complex Areas C & D (or Areas A & B) Complaint Reception Stations.
  • Action Steps: Prepare proof of IP ownership (trademark/patent certificates), evidence of alleged infringement, and booth/exhibitor identification before submitting a formal complaint.

2. Trade Disputes & Contract Breach

  • Recommended Desks: Complex Areas A & B Complaint Reception Stations; or the CCPIT Commercial Legal Service Center (Area A).
  • Action Steps: Gather signed contracts, Purchase Orders (PO), Proforma Invoices (PI), remittance receipts, delivery records, and communication logs to confirm eligibility under Canton Fair rules.

3. Cross-Border Contracts & Complex Legal Matters

  • Recommended Desks: Complex Areas B & D, Guangzhou Foreign-Related Legal Advisory Service Port.
  • Action Steps: Consult on-site attorneys regarding governing law clauses, arbitration clauses, cross-border asset preservation, and international litigation frameworks.

III. Online Dispute Resolution Pathways

For online and hybrid exhibitors, the official Canton Fair portal maintains a continuous online complaint system:

  • Online IP Complaints: Submit digital evidence and ownership certificates through the official Canton Fair website portal.
  • Trade Dispute Inquiries: Contact the official Canton Fair legal customer service hotlines:
    • Domestic Hotline: 4000-888-999
    • International Hotline: +86 (20) 28-888-999

IV. On-Site Duty Schedule of Attorney Yuting Yu

Attorney Yuting Yu (Partner and Head of International Legal Affairs at Neo-Ark Law Firm) will be on duty at the Guangzhou Foreign-Related Legal Advisory Service Port on the following dates to deliver direct legal counseling for exhibitors and buyers:

[On-Site Duty Schedule: Attorney Yuting Yu]
 ├── October 19, 2026 | Area B, Booth 10.1
 ├── November 2, 2026 | Area D, Booth 20-4
 └── November 3, 2026 | Area B, Booth 10.1
  • October 19, 2026 (Phase 1): Complex Area B, Booth 10.1
  • November 2, 2026 (Phase 3): Complex Area D, Booth 20-4
  • November 3, 2026 (Phase 3): Complex Area B, Booth 10.1

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-14

New Regulations for Hong Kong and Macao Lawyers Practicing in the Greater Bay Area: Where to Practice, Permitted Scope, and Partnership Eligibility

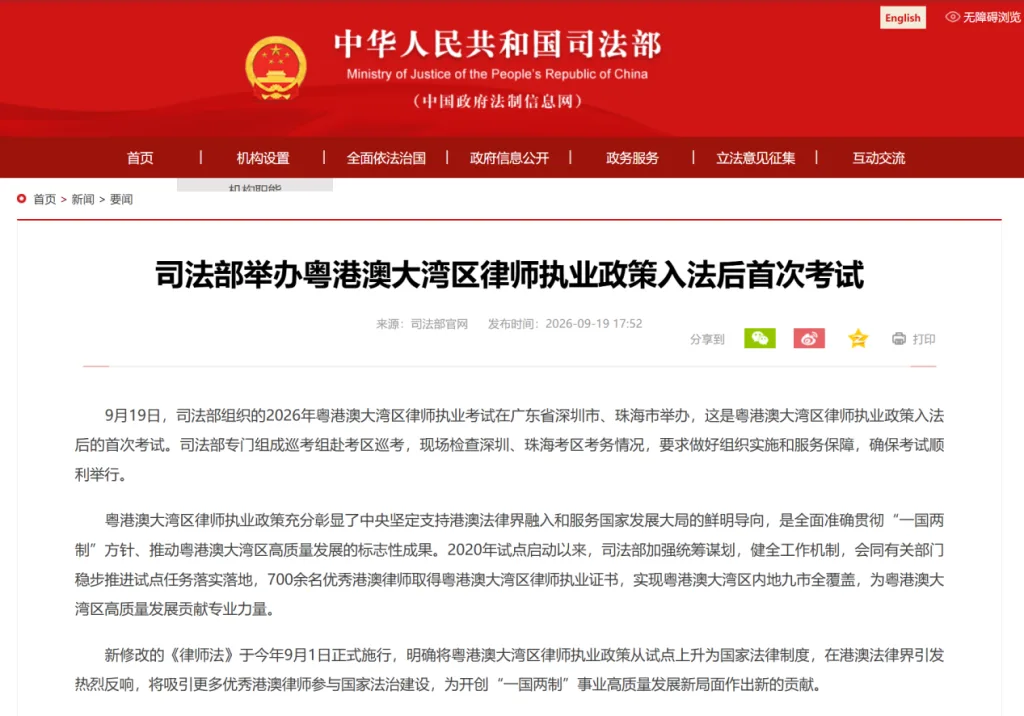
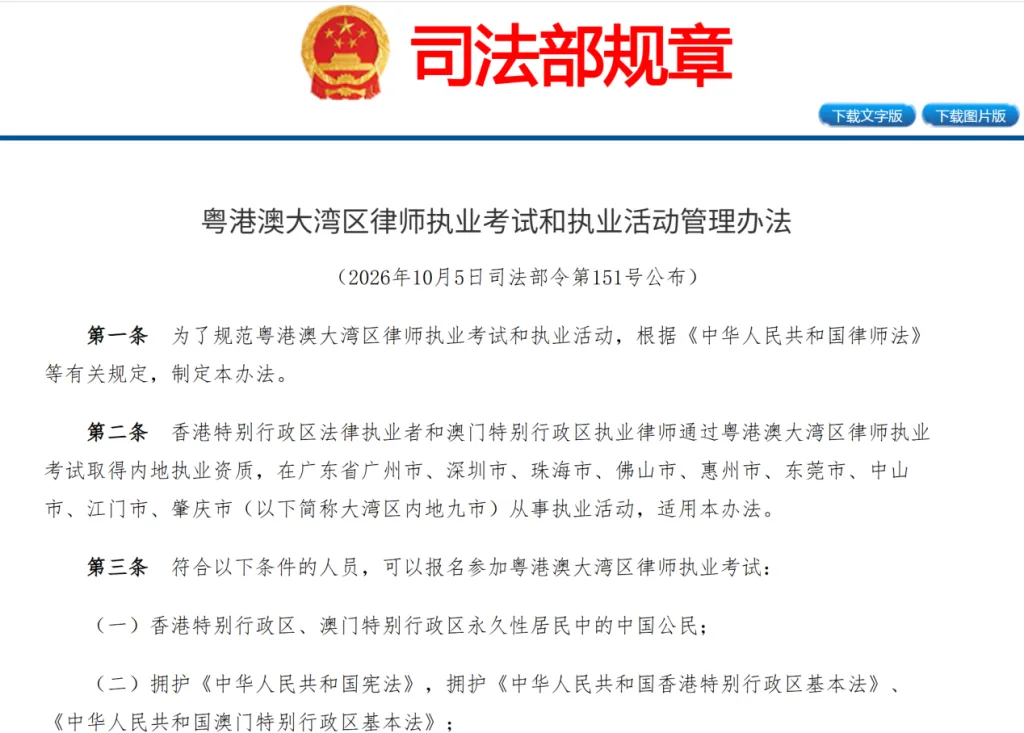
On October 5, 2026, the Ministry of Justice of the People's Republic of China promulgated Order No. 151, issuing the updated Measures for the Administration of the Examination and Practice Activities of Greater Bay Area Lawyers (粤港澳大湾区律师执业考试和执业活动管理办法), effective immediately. Comprising 12 comprehensive articles, the new regulations standardize qualifications, practice scopes, institutional affiliations, and partnership rights for legal practitioners from Hong Kong and Macao operating in the Greater Bay Area (GBA).

Legal practitioners from Hong Kong and Macao who pass the GBA Legal Qualification Examination and obtain mainland practice certificates are authorized to handle designated civil and commercial legal matters—encompassing both litigation and non-litigation services—across nine mainland GBA cities. Within this defined scope, GBA lawyers enjoy equal rights and bear equal obligations as mainland Chinese attorneys. As of September 2026, over 700 Hong Kong and Macao lawyers have successfully obtained GBA practice certificates.

I. Core Policy Highlights & Regulatory Framework

1. Institutionalization of the Examination

  • Examination Frequency: The GBA Legal Qualification Examination is officially established on a biennial schedule (held every two years).
  • Examination Locations: The primary examination center is located in Shenzhen, with an additional test center in Zhuhai depending on the volume of Macao-based applicants.

2. Eligibility Criteria for Applicants

Applicants must fulfill the following statutory requirements:

  • Citizenship & Status: Chinese citizens who are permanent residents of the Hong Kong Special Administrative Region (HKSAR) or Macao Special Administrative Region (MSAR).
  • Constitutional Compliance: Express support for the Constitution of the People's Republic of China and the Basic Laws of Hong Kong and Macao.
  • Practice Experience: A minimum of 3 cumulative years of legal practice experience. Hong Kong solicitors and barristers must not be subject to temporary qualification suspension; Macao practicing lawyers must not be under preventive suspension measures.
  • Language & Professional Ethics: High standard of professional ethics; demonstrated capability to draft legal documents in written Chinese and conduct professional activities in Mandarin (Putonghua).
  • Mandatory Training: Following examination passage, candidates must complete centralized training and pass the evaluation administered by the Guangdong Lawyers Association prior to applying for a practice certificate.

3. Permitted Practice Scope & Jurisdictional Connections

GBA lawyers are authorized to handle civil and commercial legal matters across nine mainland GBA cities (Guangzhou, Shenzhen, Zhuhai, Foshan, Huizhou, Dongguan, Zhongshan, Jiangmen, and Zhaoqing).

4. Institutional Affiliation & Partnership Eligibility

  • Permitted Employing Entities: GBA lawyers may be employed by mainland Chinese law firms located in the nine cities or by joint-venture law firms (港澳与内地合伙联营律所) established between Hong Kong/Macao and mainland firms.
  • Prohibited Employment: GBA lawyers cannot be employed by mainland representative offices of foreign law firms or mainland representative offices of Hong Kong/Macao law firms.
  • Partnership Rights: GBA lawyers are explicitly permitted to become partners in mainland law firms based within the nine GBA cities.

II. Industry Impact & Compliance Considerations

1. Strategic Advantages for Cross-Border Enterprises

The updated framework enables multi-jurisdictional enterprises to receive integrated, cross-border legal services under a unified mainland law firm structure. By bridging common law (Hong Kong), civil law (Macao), and mainland socialist legal frameworks, GBA lawyers streamline communication, optimize cross-border corporate transactions, and enhance efficiency in international commercial arbitration.

2. Institutional Operational Adjustments for Mainland Law Firms

While incorporating Hong Kong and Macao legal talent strengthens mainland firms in cross-border M&A, cross-border insolvency, and international arbitration, it necessitates internal compliance upgrades:

  • Cross-Jurisdictional Conflict Audits: Establishing robust conflict-of-interest screening across mainland and offshore client rosters.
  • Data & Document Governance: Aligning cross-border client confidentiality, document retention, and fee-sharing protocols with mainland regulatory standards.
  • Client Due Diligence (KYC): Implementing unified Anti-Money Laundering (AML) and client identity verification workflows across cross-border engagements.

Conclusion

Ministry of Justice Order No. 151 marks a significant milestone in the institutional integration of legal services across the Guangdong-Hong Kong-Macao Greater Bay Area. By clarifying practice boundaries and opening law firm partnership pathways, the new rules provide a transparent legal environment for cross-border investments, international trade, and commercial dispute resolution.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-09

Invalid Trust Loan Agreements in China: Limiting a Guarantor’s Liability

When a trust loan agreement is found invalid, the consequences may extend beyond the lender and borrower to a third party that has provided a guarantee. However, an invalid guarantee does not necessarily mean that the guarantor bears no liability. A court may examine whether the guarantor was at fault in causing the underlying contract to become invalid and whether compensation is warranted under the applicable law.

In this case, a trust company extended a substantial loan to a property development company after receiving a document purportedly issued in connection with a financing guarantee. The authenticity of that document was later challenged. An individual subsequently entered into a guarantee agreement to secure the borrower’s obligations.

The trust company brought proceedings before the Beijing High People’s Court, seeking to hold the individual liable for the borrower’s outstanding debt, interest, default interest and related recovery costs.

Representing the individual guarantor, the defense challenged the validity of both the underlying trust loan agreement and the guarantee agreement, and disputed the amount of interest-related losses claimed by the lender.

The court found both agreements invalid. However, because a criminal judgment had found that the individual used a false contract to represent the borrower in applying for the loan, the court also found that the individual was at fault in relation to the invalidity of the principal contract. The individual was therefore ordered to compensate the lender for a portion of specified losses that the borrower could not repay, rather than being held liable under the guarantee as originally agreed.

The case illustrates the distinction between contractual guarantee liability and compensation liability arising from fault associated with an invalid contract.

Case Snapshot

ItemDetails
Practice AreaTrust and Finance Disputes / Guarantee Liability
JurisdictionMainland China
CourtBeijing High People’s Court
Original Claim ValueApproximately RMB 120 million
Client PositionDefendant and individual guarantor
AttorneyYu Yuting
Law FirmNEO-ARK Law Firm
Key IssuesInvalid loan agreement, invalid guarantee, fault-based compensation, excessive interest claims

Key Legal Issues

1. What happens to a guarantee when the underlying loan agreement is invalid?

A guarantee is intended to secure an underlying obligation, but its legal effect must be assessed under the applicable law and the circumstances of the case. Where the principal contract is invalid, the guarantee agreement may also be invalid, subject to the relevant legal framework.

In this case, the lender sought to enforce an individual guarantee securing a substantial trust loan. The defense argued that the underlying trust loan agreement was invalid and that the guarantee agreement should likewise be found invalid.

The court accepted the challenge to the validity of both agreements.

This did not, however, automatically eliminate every possible form of liability. The court separately considered whether the individual guarantor had contributed to the invalidity of the principal contract and whether compensation was justified.

The practical distinction is important: a claim for performance under a valid guarantee is legally different from a claim for compensation arising from fault associated with an invalid contract.

2. Can a guarantor still be liable if the guarantee agreement is invalid?

Potentially, yes. Depending on the applicable law, the reasons for invalidity and the parties’ respective fault, a court may consider whether a party should compensate the other side for losses resulting from an invalid contract.

In this case, a criminal judgment had found that the individual used a false contract while representing the borrower in the loan application process. The court considered this finding when assessing the individual’s fault in relation to the invalidity of the principal contract.

As a result, the individual was ordered to bear a proportion of specified losses that the borrower could not repay.

This outcome demonstrates why a defense should distinguish between denying liability under the guarantee itself and addressing any separate compensation claim based on fault. Invalidity and liability are related issues, but they are not interchangeable conclusions.

3. How can a defense challenge excessive interest and default interest claims?

A lender’s claim may include principal, contractual interest, default interest and recovery expenses. Each component must be assessed according to the applicable law, the contract’s validity and the evidence supporting the claimed loss.

Here, the defense challenged not only the validity of the loan and guarantee agreements but also the amount of interest-related losses claimed by the lender.

The court found the trust loan agreement invalid and determined that the borrower’s liability for the resulting loss of use of funds should be calculated by reference to the applicable one-year benchmark lending rate of the People’s Bank of China under the legal framework applied in the case. It did not simply enforce the lender’s original contractual interest and default interest claims as presented.

The case illustrates the importance of examining the legal basis of each claimed amount. Where the underlying agreement is invalid, contractual interest provisions may not determine the measure of recoverable loss.

The precise rules and interest benchmarks applicable to a dispute depend on the relevant dates, transitional provisions and governing law.

4. Why does fault in causing contractual invalidity matter?

When a contract is invalid, a court may need to examine the conduct of the parties and determine whether any party should bear responsibility for resulting losses. The consequences are fact-specific and depend on the legal rules applicable to the transaction.

In this dispute, the court did not treat the individual’s invalid guarantee as the end of the analysis. It considered the criminal judgment concerning the individual’s conduct in the loan application process and found fault relevant to the invalidity of the principal contract.

The resulting compensation obligation was distinct from the guarantee obligation originally asserted by the lender.

For guarantors, this means that a legal defense should assess the basis and scope of each potential claim, including whether the lender is seeking contractual performance, restitution or compensation arising from fault.

Legal Strategy and Case Outcome

IssueCourt’s Determination
Validity of the trust loan agreementThe agreement was found invalid.
Validity of the guarantee agreementThe guarantee agreement was also found invalid.
Borrower’s liabilityThe borrower was responsible for the loss of use of funds arising from the invalid loan agreement, assessed under the applicable legal framework.
Individual guarantor’s conductThe court considered the relevant criminal judgment and found the individual at fault in relation to the invalidity of the principal contract.
Scope of the individual’s liabilityThe individual was ordered to compensate the lender for a portion of specified losses that the borrower could not repay, including relevant interest-related losses and reasonable legal fees.
Original contractual guarantee claimThe individual was not held liable simply by enforcing the guarantee as written; the court assessed liability in light of the invalid agreements and the individual’s fault.

The court accepted the defense’s position that the principal loan agreement and the guarantee agreement were invalid. It nevertheless imposed a limited compensation obligation on the individual because of the fault found in connection with the principal contract’s invalidity.

The precise amounts claimed and the detailed calculation of liability are omitted to protect client confidentiality.

Practical Lessons for Guarantee and Trust Loan Disputes in China

Examine the validity of the underlying transaction first. A guarantee dispute may depend on whether the principal contract is valid and whether the underlying obligation can be enforced as agreed. The documents and circumstances surrounding the original financing should be reviewed carefully.

Separate guarantee liability from compensation liability. A finding that a guarantee is invalid does not necessarily resolve every claim against the guarantor. The legal basis, relevant conduct and scope of any alleged loss must be analyzed separately.

Assess the significance of related criminal findings. Where a criminal judgment concerns conduct connected with the loan application or contract formation, its findings may be relevant to the civil court’s assessment of fault. The precise effect depends on the issues decided and the applicable law.

Challenge each component of the lender’s claim. Principal, contractual interest, default interest and legal expenses may be governed by different legal considerations. If the underlying contract is invalid, the lender may not automatically recover every amount calculated under its original terms.

Determine the scope of liability by reference to the governing law. Compensation arising from an invalid contract is not automatically equivalent to the entire debt or the full amount demanded by the lender. The applicable legal framework and the court’s findings determine the nature and extent of any liability.

Frequently Asked Questions

Does an invalid loan agreement automatically release the guarantor in China?

No. The invalidity of the principal contract may affect the guarantee agreement, but it does not automatically exclude every possible claim against the guarantor. Depending on the circumstances and applicable law, a court may consider separate compensation liability based on fault.

Can a guarantor be ordered to pay compensation even if the guarantee agreement is invalid?

Potentially, yes. A court may assess whether the guarantor was at fault in relation to the invalidity of the underlying contract and whether compensation is warranted under the applicable rules. Such liability is fact-specific and should not be assumed in every case involving an invalid guarantee.

Can a lender recover contractual interest when the underlying loan agreement is invalid?

The outcome depends on the legal basis of the claim and the rules applicable to the transaction. A court may assess the loss associated with the use of funds under the rules governing invalid contracts rather than simply enforce the contractual interest provisions.

Can a guarantor challenge a claim for excessive default interest and legal expenses?

Yes. The guarantor may dispute the legal basis, calculation and recoverability of the amounts claimed, subject to the procedural rules and the circumstances of the case. Whether the challenge succeeds depends on the evidence and applicable law.

Is compensation liability the same as joint and several guarantee liability?

No. Joint and several guarantee liability arises from an enforceable guarantee obligation. Compensation liability associated with an invalid contract has a different legal basis and depends on the applicable rules and the court’s findings concerning fault and loss.

Conclusion

This case demonstrates that a guarantee dispute involving an invalid trust loan agreement requires a careful distinction between contractual enforcement and fault-based compensation. Although the court found both the loan agreement and guarantee agreement invalid, it separately assessed the individual guarantor’s conduct and imposed a limited compensation obligation.

For parties involved in trust financing and guarantee disputes in mainland China, reviewing the validity of the underlying transaction, the conduct of the guarantor and the legal basis for each claimed loss can be central to determining the proper scope of liability.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-06

Enforcing Renewed Loan Agreements in China: Debt Classification and Interest Reconciliation

Large private lending disputes can involve years of renewed agreements, substantial transfers and repeated interest payments. When a borrower later argues that the relationship was a form of investment or financial cooperation rather than a loan, the creditor may need to establish the true nature of the transactions and reconcile the historical accounts.

In this case, a US national entered into multiple renewed loan agreements with an individual borrower in China. Two companies were named as joint and several guarantors. After interest payments stopped, the lender commenced proceedings before the Shanghai Financial Court to recover the outstanding principal and interest.

The first-instance court upheld the validity of the loan agreements and recognized the underlying relationship as borrowing rather than a risk-sharing investment arrangement. After reviewing the historical payments and interest calculations, the court determined the outstanding debt. The claims against the two corporate guarantors were unsuccessful because the guarantees were found invalid and the applicable guarantee periods had expired.

The case illustrates the importance of documenting the continuity of a long-term lending relationship, establishing the legal character of renewed agreements and reconciling principal and interest under the rules applicable to the transactions.

Case Snapshot

ItemDetails
Practice AreaContract Disputes / Private Lending
JurisdictionMainland China
CourtShanghai Financial Court
Cross-Border ElementThe lender was a US national
Original Claim ValueApproximately RMB 93 million
AttorneyYu Yuting
Law FirmNEO-ARK Law Firm
Key IssuesRenewed loan agreements, debt classification, interest reconciliation, guarantee enforceability
Procedural StatusFirst-instance judgment; within the appeal period as reported

Key Legal Issues

1. Can renewed agreements remain valid loan contracts when the borrower alleges an investment or cooperation arrangement?

A dispute over the legal nature of a funding arrangement can materially affect the creditor’s recovery rights. A borrower may argue that funds were advanced as part of a broader commercial cooperation rather than a conventional loan, particularly where the parties have signed successive agreements over several years.

In this case, the borrower challenged the characterization of the relationship as a loan. The lender maintained that the arrangement involved repayment obligations and fixed returns rather than an investment under which the lender assumed the underlying business risks.

The first-instance court accepted the loan characterization and upheld the relevant renewed agreements and confirmation document.

The case demonstrates that contractual labels alone may not resolve a dispute over the nature of a transaction. The substance of the arrangement, the parties’ actual obligations and the history of performance can all be relevant to determining whether the relationship constitutes a loan or another form of commercial arrangement.

2. How can a creditor establish the outstanding balance under multiple renewed loan agreements?

Where a lending relationship continues through successive agreements, the outstanding balance may be affected by historical payments, interest settlements and adjustments made over time. A creditor must establish not only the original amount advanced but also how the balance developed throughout the relationship.

Here, the court considered the multiple loan agreements and the parties’ historical financial dealings when determining the outstanding debt. It accounted for interest previously paid and the relevant compensation associated with the use of funds before calculating the balance recoverable under the first-instance judgment.

The result illustrates the distinction between the original principal recorded in the agreements and the amount ultimately recognized as outstanding after the court’s accounting assessment.

For creditors, consistent records of the contractual history and payment arrangements can help explain how a debt has evolved and reduce uncertainty over the amount claimed.

3. How are historical interest payments treated when determining the remaining principal?

Long-term lending relationships may involve payments that need to be reconciled against the interest legally recoverable under the applicable rules. Depending on the facts and the governing provisions, the court may need to consider whether previous payments exceed the permitted interest and how any resulting adjustment affects the outstanding balance.

In this case, the court examined the historical interest payments and the parties’ account records. After its assessment of the interest and funding-related compensation, it determined the principal remaining payable by the borrower.

The applicable interest rules can depend on the agreement date, the relevant period and transitional provisions. The rate and accounting treatment applied in an individual judgment should therefore not be assumed to govern every private lending arrangement.

4. Why might corporate guarantors be released even when the borrower remains liable?

A creditor may obtain a judgment against a borrower without necessarily establishing an enforceable guarantee against every company named in the agreements.

In this case, the two corporate guarantees were found invalid, and the applicable guarantee periods had also expired. The first-instance court therefore did not impose guarantee liability on the companies.

This outcome highlights the need to assess the validity of each guarantee and the timing of actions required to preserve rights under it. The borrower’s repayment obligation and a third party’s guarantee obligation are legally distinct questions; success on the underlying debt claim does not automatically establish liability against every guarantor.

Legal Strategy and Case Outcome

IssueCourt’s First-Instance Determination
Nature of the transactionThe relationship was recognized as borrowing rather than the alleged investment or financial cooperation arrangement.
Renewed agreementsThe relevant loan agreements and confirmation document were upheld as valid.
Outstanding principalThe court determined the remaining principal after reviewing historical payments and relevant adjustments.
InterestThe court assessed the historical interest and ordered payment of overdue interest under the terms and legal analysis reflected in its judgment.
Corporate guaranteesThe two companies were not held liable because the guarantees were found invalid and the applicable guarantee periods had expired.
Procedural statusThe case was within the appeal period following the first-instance judgment, as reported.

The first-instance court ordered the individual borrower to repay the outstanding principal and overdue interest. It did not impose guarantee liability on the two corporate defendants.

The precise judgment amount, detailed interest adjustments and litigation-cost allocation are omitted to protect client confidentiality. The first-instance result should not be treated as final while the appeal period remains relevant.

Practical Lessons for Large Private Lending Disputes in China

Document each renewal clearly. When a loan is renewed repeatedly, the agreements should make the continuing repayment obligation and the relationship to earlier transactions understandable. Confirmation documents and payment records may also help establish the continuity of the debt.

Establish the substance of the funding arrangement. Where the borrower characterizes a transaction as investment or cooperation, the parties’ actual obligations, allocation of commercial risk and payment arrangements may be important to the legal analysis.

Maintain a consistent historical account. For long-term lending, a coherent record of principal, payments, interest and adjustments can help explain the outstanding balance. Calculations should be reconcilable with the underlying transaction records and the legal rules applicable to each relevant period.

Review guarantee validity and timing separately. Corporate approval requirements and guarantee periods can determine whether a company can be held liable. These issues should be assessed independently of the borrower’s underlying repayment obligation.

Distinguish a first-instance result from a final outcome. A judgment that remains subject to appeal may be challenged or changed. Public case descriptions should accurately identify the procedural stage and avoid presenting the first-instance result as conclusively final.

Frequently Asked Questions

Can a renewed loan agreement be enforced in China if the borrower says the transaction was an investment?

Potentially, yes. The court may examine the substance of the arrangement, the parties’ contractual obligations, how returns were structured and whether the lender assumed commercial risks. The characterization depends on the facts and applicable law, not simply on the terminology used by one party.

How does a court calculate the outstanding principal in a long-term private lending dispute?

The court may review the original advances, renewed agreements, repayments, historical interest payments and other relevant adjustments. The resulting balance depends on the evidence and the legal rules applicable to the transaction and the relevant periods.

Can a company avoid guarantee liability if its guarantee is invalid?

An invalid guarantee may prevent enforcement of the guarantee as written, but the legal consequences depend on the circumstances and applicable law. Any separate compensation liability requires its own legal basis and should not be assumed automatically.

Does the borrower’s liability depend on whether the corporate guarantees are enforceable?

Not necessarily. The borrower’s contractual repayment obligation and a guarantor’s liability are distinct. A borrower may remain liable even where claims against corporate guarantors fail.

Is a first-instance judgment final in China?

Not necessarily. Where an appeal remains available or has been filed, the first-instance judgment should be described according to its actual procedural status. The final outcome may differ if the judgment is changed on appeal.

Conclusion

This case illustrates the challenges of recovering a substantial debt arising from multiple renewed loan agreements. Establishing the true nature of the transaction, documenting the continuity of the debt and reconciling historical interest are central to determining the amount legally recoverable. At the same time, guarantee validity and the applicable guarantee periods must be examined separately from the borrower’s repayment obligation.

For creditors involved in long-term private lending in mainland China, careful contractual documentation and a consistent financial record can help clarify the debt and support a more reliable assessment of recovery prospects.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-02

Scroll to Top

+86 13503030053

BackToTop

Inquiry Inquiry Email Email Tel Tel

Request A Quote

×
Please enable JavaScript in your browser to complete this form.