...

News

When Loan Repayments Are Disputed: Evidence and Corporate Guarantee Liability in China

Overview

Private loan recovery disputes can become more complicated when a borrower claims that payments were made toward the debt, but the creditor maintains that those payments related to other transactions. A separate issue may arise where a company provided a guarantee without satisfying the applicable corporate approval requirements.

In this case, a US national advanced funds to an individual borrower under a loan arrangement documented through WhatsApp communications and a subsequent written IOU. A company also purported to provide a joint and several guarantee. When the borrower failed to repay the outstanding debt, the lender brought proceedings before the Shanghai Pudong New Area People’s Court.

The court examined the actual amount advanced, the parties’ repayment records and the disputed allocation of payments. It also found the corporate guarantee invalid but held the company liable to compensate for part of the borrower’s loss attributable to the unenforceable guarantee, based on the circumstances and the parties’ respective fault.

The case illustrates two important issues in Chinese loan litigation: distinguishing repayments across multiple lending transactions and assessing potential corporate liability when a guarantee is invalid.

Case Snapshot

ItemDetails
Practice AreaContract Disputes / Private Lending
JurisdictionMainland China
CourtShanghai Pudong New Area People’s Court
Cross-Border ElementThe lender was a US national
Disputed AmountApproximately RMB 5 million
AttorneyYu Yuting
Law FirmNEO-ARK Law Firm
Key IssuesRepayment allocation, loan interest, invalid corporate guarantee

Key Legal Issues

1. How can a lender prove that disputed payments relate to other loans?

Where the same parties have multiple lending transactions, a borrower may argue that payments made in connection with other transactions should reduce the debt being litigated. The central issue is not simply whether money changed hands, but which obligation each payment was intended to discharge.

In this case, the borrower argued that additional transfers should be treated as repayments under the disputed loan. The lender presented communications and reconciliation materials to distinguish the transactions and explain how the disputed transfers had been recorded.

The court accepted the lender’s position on the disputed allocation. This prevented payments associated with other lending arrangements from being incorrectly deducted from the balance claimed in this case.

The broader lesson is that creditors involved in multiple loan transactions should maintain records that clearly distinguish the parties’ different obligations. Communications, payment records and account reconciliations may help establish the context of a transfer when its purpose is disputed.

2. Can a WhatsApp conversation help establish a loan agreement?

Electronic communications may be relevant to proving the formation and terms of a loan agreement, particularly where the parties discussed the arrangement before signing a formal document.

Here, the parties discussed the loan through WhatsApp, and a written IOU was subsequently issued. The court considered the loan arrangement and related financial records when determining the actual amount advanced and the outstanding obligation.

The evidential value of a message depends on its authenticity, completeness, context and consistency with other evidence. A creditor should therefore preserve relevant electronic records and ensure that the communications can be connected to the parties and transactions in dispute.

3. What happens when a company guarantee is invalid?

A corporate guarantee may be challenged where the company failed to obtain the approval required under applicable company law or its governing arrangements. Whether the guarantee is effective depends on the relevant legal requirements and the circumstances in which it was provided.

In this case, the court found the company guarantee invalid because the required shareholder resolution was absent. However, the invalidity of the guarantee did not automatically eliminate all potential liability. The court found fault on both sides and ordered the company to bear a proportion of the borrower’s loss, subject to the conditions stated in the judgment.

This distinction matters: liability arising from an invalid guarantee is not the same as enforcement of a valid guarantee. The legal basis, degree of fault and applicable statutory rules must be considered before determining whether compensation may be available and how much may be recoverable.

4. How are interest and overdue interest assessed in a private lending case?

The interest stated in a loan document does not necessarily determine the full amount recoverable in court. Applicable judicial rules may limit the interest that can be claimed, and the relevant limit may depend on the contract date and the legal provisions applicable to the particular period.

In this dispute, the court assessed interest by reference to the applicable lending rules and supported interest calculated within the relevant legal limit. The result reflected the court’s legal assessment rather than simply adopting every term in the parties’ original interest arrangement.

For creditors and borrowers alike, interest calculations should account for the date and terms of the agreement, payments already made, the applicable legal cap and the distinction between interest during the loan term and overdue interest.

Legal Strategy and Case Outcome

IssueApproach and Result
Actual amount advancedThe court distinguished the amount actually transferred from the higher face amount recorded in the IOU.
Disputed repaymentsThe court accepted the lender’s position that certain disputed transfers related to other lending transactions.
InterestThe court applied the relevant legal limits when determining recoverable interest.
Corporate guaranteeThe guarantee was found invalid because the required shareholder resolution was absent.
Company’s liabilityThe company was ordered to compensate for part of the borrower’s loss based on the parties’ respective fault and the court’s findings.

The court ordered the borrower to repay the outstanding debt and applicable interest. It also held the company liable for a portion of the borrower’s loss arising from the invalid guarantee.

The precise amounts and detailed reconciliation records are omitted to protect client confidentiality.

Practical Lessons for Private Loan Recovery in China

Keep separate loans clearly documented. When the same parties engage in several lending transactions, each loan should have identifiable terms, payment records and a clear accounting history. This can reduce disputes over whether a transfer relates to one loan or another.

Preserve electronic communications in context. Messages exchanged through WhatsApp or other platforms may help establish a loan arrangement, clarify repayment intentions or explain the relationship between different transactions. Their evidential value depends on authenticity, completeness and consistency with other records.

Record the actual amount advanced. If interest is deducted before funds are transferred, the amount actually delivered may differ from the nominal amount written in an IOU. The legal treatment of the transaction should be assessed using the actual payment history and applicable rules.

Check corporate approval before relying on a guarantee. A company’s written promise to guarantee a debt does not necessarily mean that the guarantee is legally enforceable. Creditors should assess whether the required corporate approvals and other legal conditions have been satisfied.

Do not assume an invalid guarantee ends every potential claim against the company. Depending on the applicable law and the parties’ conduct, a court may need to consider whether liability arises from fault associated with the invalid guarantee. Such liability is fact-specific and should not be treated as automatic.

Frequently Asked Questions

Can a court distinguish repayments made under different loan agreements?

Yes. When a borrower has multiple transactions with a creditor, the court may examine payment records, communications, account reconciliations and other relevant evidence to determine which debt a payment was intended to discharge.

Can WhatsApp messages be used as evidence in a loan dispute in China?

Electronic messages may be considered as evidence if they are relevant and their authenticity and evidential value can be established. Their significance depends on the content, context and relationship to other evidence in the case.

Is a company automatically liable if its guarantee is invalid?

No. An invalid guarantee does not automatically make the company liable for the entire debt. A court may need to examine the applicable legal rules, the parties’ respective fault and the requirements for any resulting compensation liability.

Can a court limit interest even if the loan document specifies a higher rate?

Yes. Contractual interest may be subject to applicable statutory or judicial limits. The permissible rate and its application should be assessed in light of the agreement date, relevant transitional rules and the periods for which interest is claimed.

Conclusion

This case demonstrates the importance of transaction-specific accounting in private loan recovery. Where multiple loans exist between the same parties, clear records can help prevent unrelated payments from being incorrectly applied to the debt in dispute. It also shows why a corporate guarantee should be assessed not only by reference to its written terms, but also by reference to the legal requirements governing its validity and any potential consequences of invalidity.

For cross-border lenders pursuing claims in mainland China, careful documentation, preservation of electronic records and early review of corporate guarantee formalities can help clarify the claim and identify the legal basis for potential recovery.

About the Author
Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
Recommend
Legal Guide for the 140th Canton Fair | Legal Services and Dispute Resolution

The 140th China Import and Export Fair (Canton Fair) takes place in Guangzhou from October 15 to November 4, 2026. Bringing together thousands of international buyers and domestic exhibitors, the fair serves as a vital global trade platform.

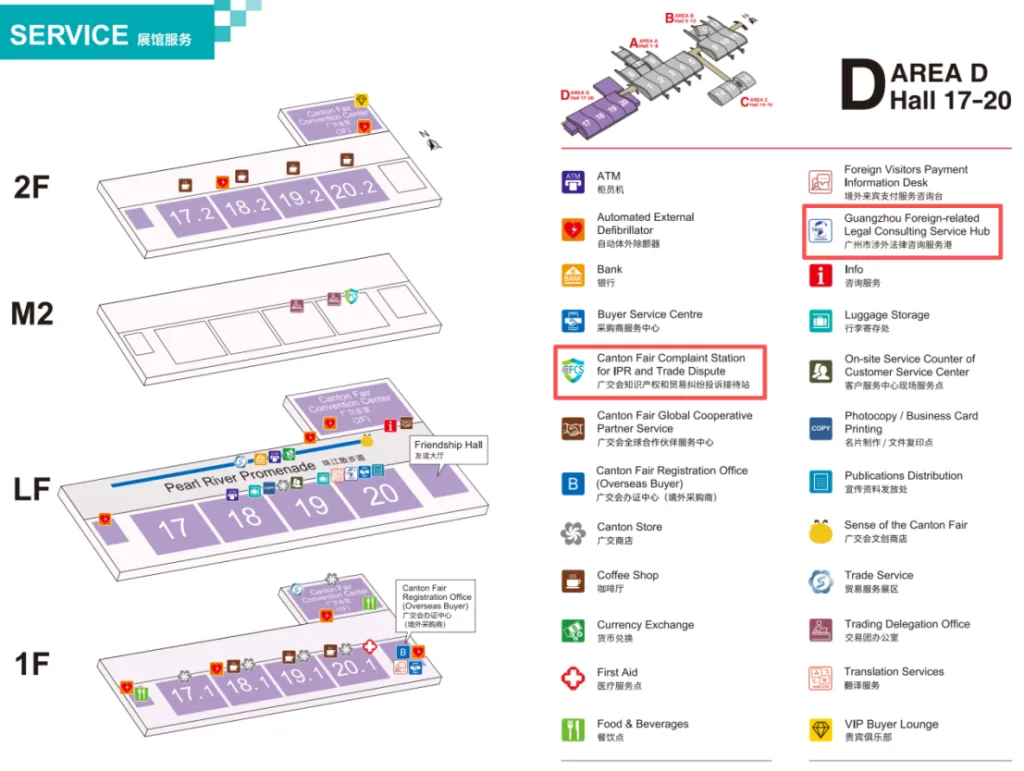
To help participants navigate legal issues and resolve commercial conflicts efficiently, this guide outlines on-site legal service stations, offline dispute resolution channels, online complaint mechanisms, and the duty schedule for Attorney Yuting Yu (Partner & Head of International Legal Affairs at Neo-Ark Law Firm), who will serve at the Guangzhou Foreign-Related Legal Advisory Service Port.

I. Three On-Site Legal Service Channels

Service StationCore Service ScopeRecommended Scenarios
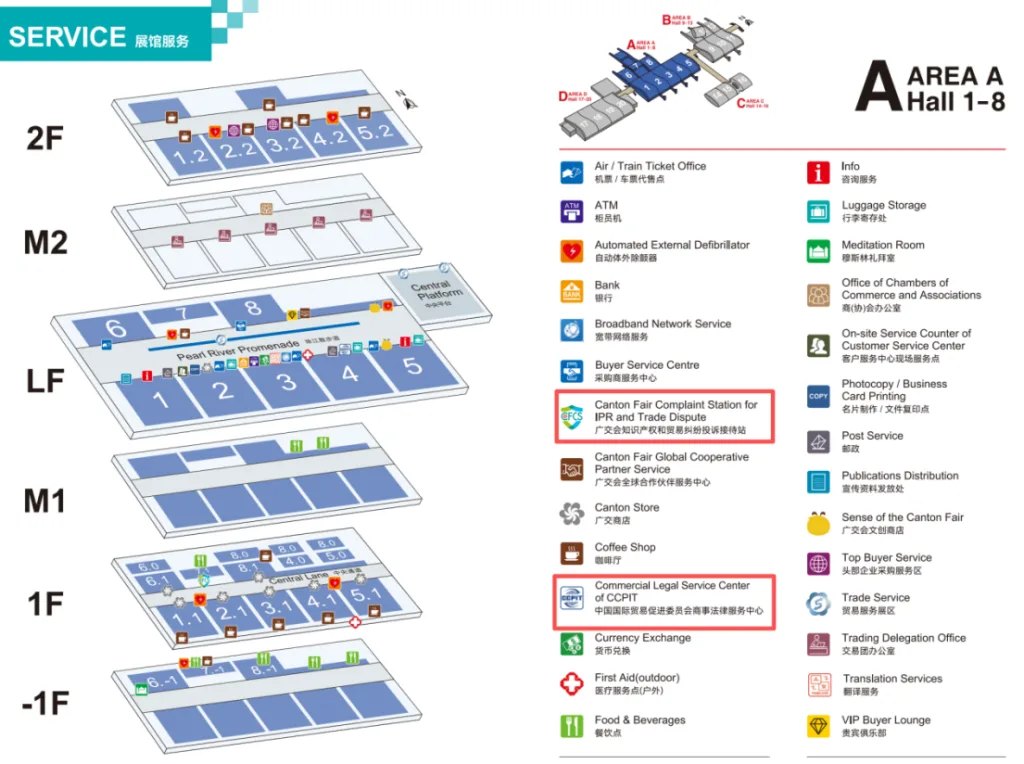
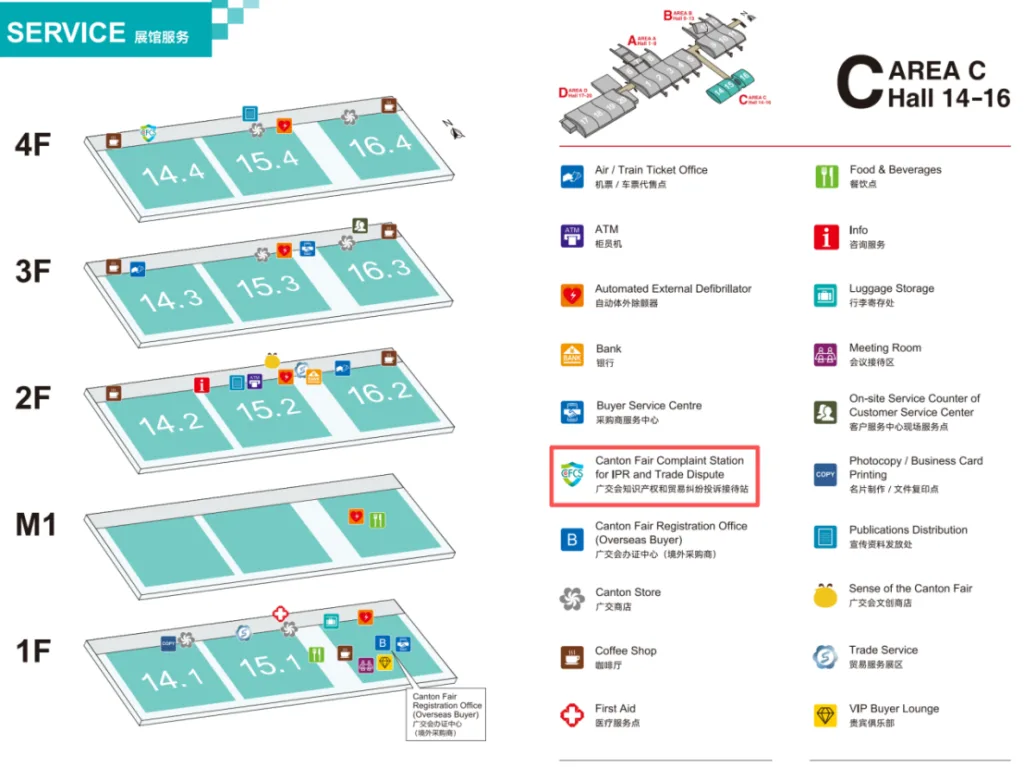
IP & Trade Dispute Complaint Station
(知识产权和贸易纠纷投诉接待站)
Processes compliant intellectual property (IP) and trade dispute complaints under official Canton Fair guidelines.On-site IP infringement allegations or trade contract disputes within Canton Fair jurisdiction.
CCPIT Commercial Legal Service Center
(中国贸促会商事法律服务中心)
Provides commercial legal counseling, contract risk assessment, and trade dispute advice.Enterprises seeking guidance on international trade laws, cross-border contracts, and commercial risk.
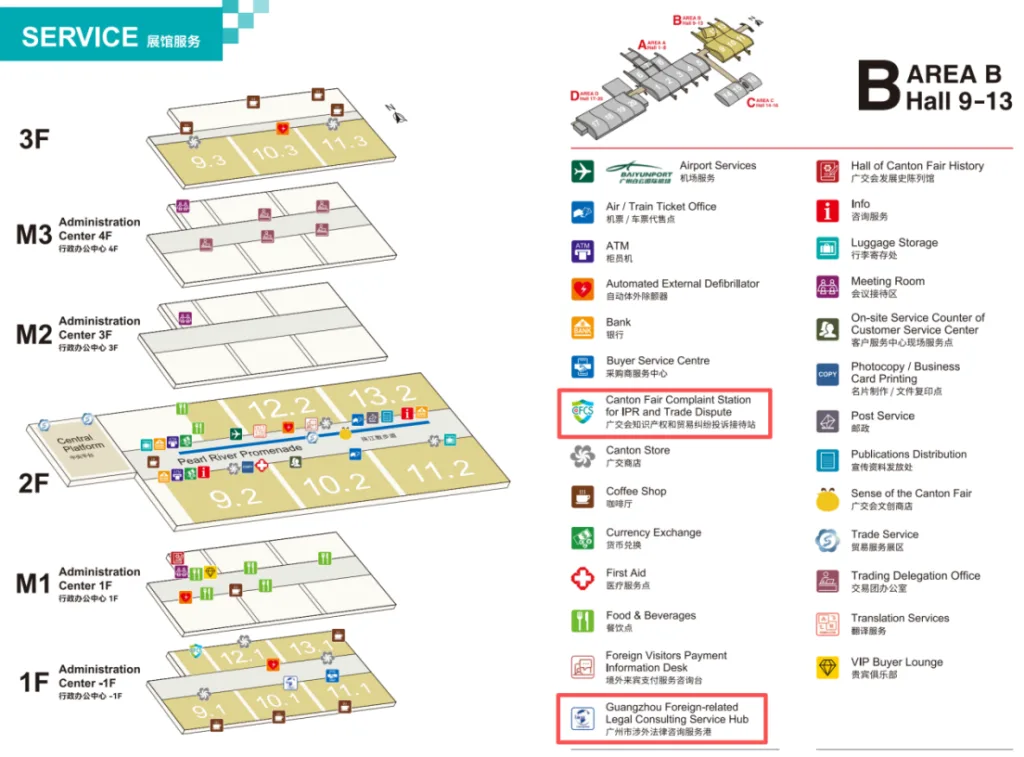
Guangzhou Foreign-Related Legal Service Port
(广州市涉外法律咨询服务港)
Connects exhibitors with cross-border legal consulting, attorney services, arbitration, notarization, mediation, and foreign law ascertainment.Overseas buyers and domestic suppliers requiring advice on governing laws, cross-border dispute resolution, or legal representation.

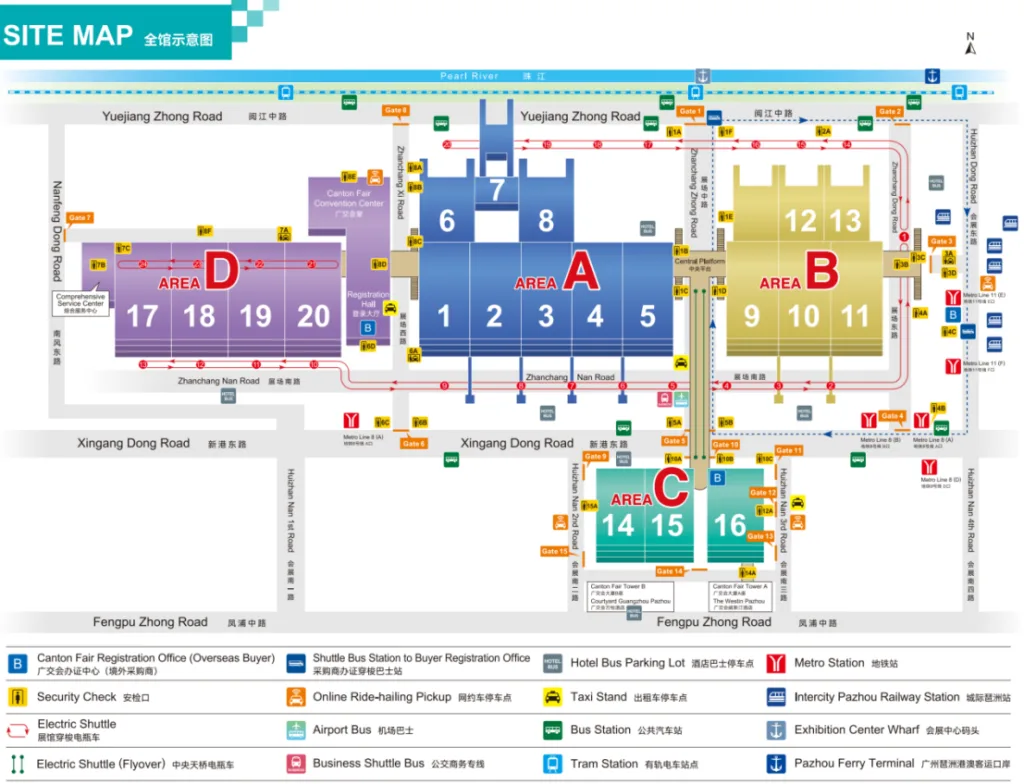
Zone Service Rules: IP and Trade Dispute Complaint Stations are stationed across Complex Areas A, B, C, and D. While Areas A and B accept both IP and trade dispute complaints, Areas C and D handle IP complaints exclusively. Trade dispute complaints occurring in Areas C or D must be submitted at the Area A or B complaint desks.

II. Offline Dispute Resolution Pathways

1. Alleged Intellectual Property (IP) Infringement

  • Recommended Desks: Complex Areas C & D (or Areas A & B) Complaint Reception Stations.
  • Action Steps: Prepare proof of IP ownership (trademark/patent certificates), evidence of alleged infringement, and booth/exhibitor identification before submitting a formal complaint.

2. Trade Disputes & Contract Breach

  • Recommended Desks: Complex Areas A & B Complaint Reception Stations; or the CCPIT Commercial Legal Service Center (Area A).
  • Action Steps: Gather signed contracts, Purchase Orders (PO), Proforma Invoices (PI), remittance receipts, delivery records, and communication logs to confirm eligibility under Canton Fair rules.

3. Cross-Border Contracts & Complex Legal Matters

  • Recommended Desks: Complex Areas B & D, Guangzhou Foreign-Related Legal Advisory Service Port.
  • Action Steps: Consult on-site attorneys regarding governing law clauses, arbitration clauses, cross-border asset preservation, and international litigation frameworks.

III. Online Dispute Resolution Pathways

For online and hybrid exhibitors, the official Canton Fair portal maintains a continuous online complaint system:

  • Online IP Complaints: Submit digital evidence and ownership certificates through the official Canton Fair website portal.
  • Trade Dispute Inquiries: Contact the official Canton Fair legal customer service hotlines:
    • Domestic Hotline: 4000-888-999
    • International Hotline: +86 (20) 28-888-999

IV. On-Site Duty Schedule of Attorney Yuting Yu

Attorney Yuting Yu (Partner and Head of International Legal Affairs at Neo-Ark Law Firm) will be on duty at the Guangzhou Foreign-Related Legal Advisory Service Port on the following dates to deliver direct legal counseling for exhibitors and buyers:

[On-Site Duty Schedule: Attorney Yuting Yu]
 ├── October 19, 2026 | Area B, Booth 10.1
 ├── November 2, 2026 | Area D, Booth 20-4
 └── November 3, 2026 | Area B, Booth 10.1
  • October 19, 2026 (Phase 1): Complex Area B, Booth 10.1
  • November 2, 2026 (Phase 3): Complex Area D, Booth 20-4
  • November 3, 2026 (Phase 3): Complex Area B, Booth 10.1

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-14

New Regulations for Hong Kong and Macao Lawyers Practicing in the Greater Bay Area: Where to Practice, Permitted Scope, and Partnership Eligibility

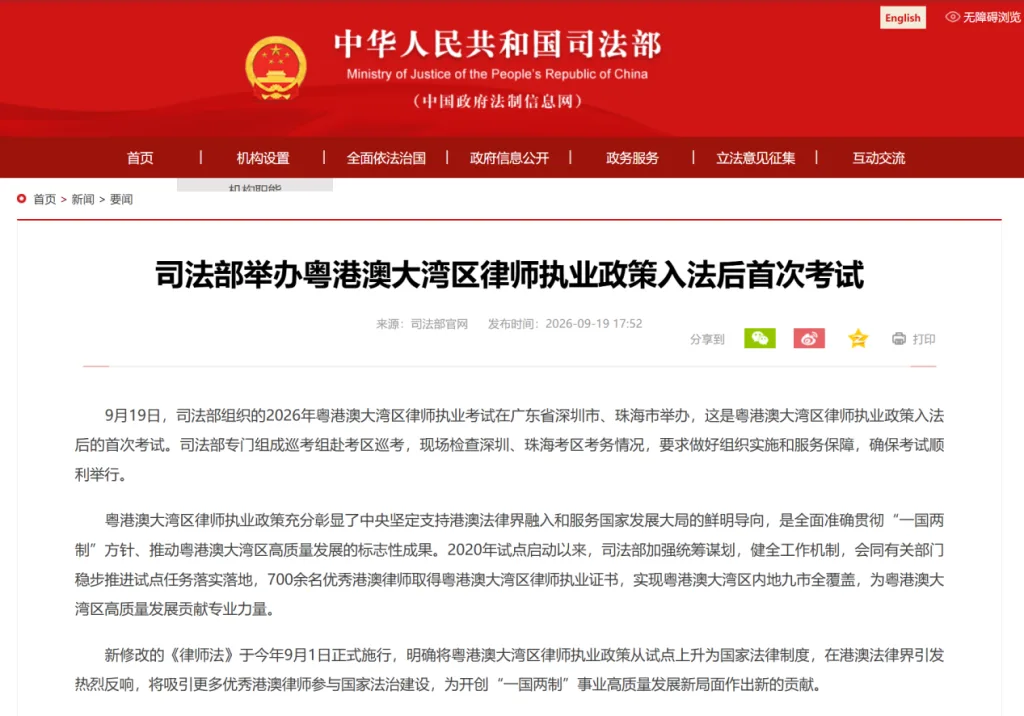
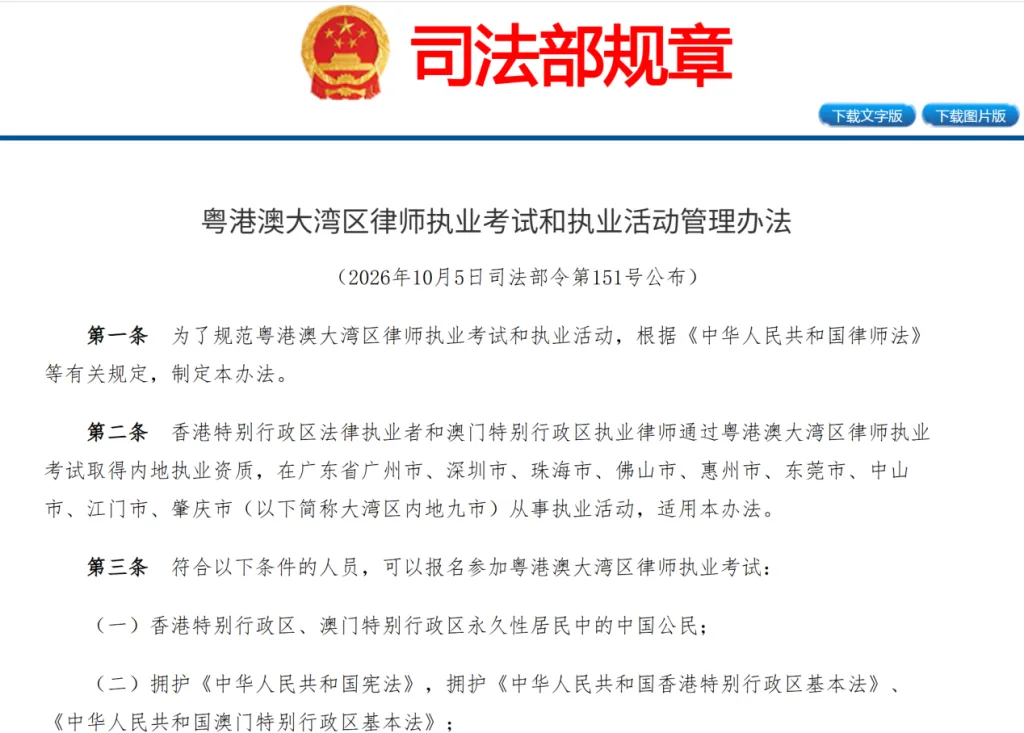
On October 5, 2026, the Ministry of Justice of the People's Republic of China promulgated Order No. 151, issuing the updated Measures for the Administration of the Examination and Practice Activities of Greater Bay Area Lawyers (粤港澳大湾区律师执业考试和执业活动管理办法), effective immediately. Comprising 12 comprehensive articles, the new regulations standardize qualifications, practice scopes, institutional affiliations, and partnership rights for legal practitioners from Hong Kong and Macao operating in the Greater Bay Area (GBA).

Legal practitioners from Hong Kong and Macao who pass the GBA Legal Qualification Examination and obtain mainland practice certificates are authorized to handle designated civil and commercial legal matters—encompassing both litigation and non-litigation services—across nine mainland GBA cities. Within this defined scope, GBA lawyers enjoy equal rights and bear equal obligations as mainland Chinese attorneys. As of September 2026, over 700 Hong Kong and Macao lawyers have successfully obtained GBA practice certificates.

I. Core Policy Highlights & Regulatory Framework

1. Institutionalization of the Examination

  • Examination Frequency: The GBA Legal Qualification Examination is officially established on a biennial schedule (held every two years).
  • Examination Locations: The primary examination center is located in Shenzhen, with an additional test center in Zhuhai depending on the volume of Macao-based applicants.

2. Eligibility Criteria for Applicants

Applicants must fulfill the following statutory requirements:

  • Citizenship & Status: Chinese citizens who are permanent residents of the Hong Kong Special Administrative Region (HKSAR) or Macao Special Administrative Region (MSAR).
  • Constitutional Compliance: Express support for the Constitution of the People's Republic of China and the Basic Laws of Hong Kong and Macao.
  • Practice Experience: A minimum of 3 cumulative years of legal practice experience. Hong Kong solicitors and barristers must not be subject to temporary qualification suspension; Macao practicing lawyers must not be under preventive suspension measures.
  • Language & Professional Ethics: High standard of professional ethics; demonstrated capability to draft legal documents in written Chinese and conduct professional activities in Mandarin (Putonghua).
  • Mandatory Training: Following examination passage, candidates must complete centralized training and pass the evaluation administered by the Guangdong Lawyers Association prior to applying for a practice certificate.

3. Permitted Practice Scope & Jurisdictional Connections

GBA lawyers are authorized to handle civil and commercial legal matters across nine mainland GBA cities (Guangzhou, Shenzhen, Zhuhai, Foshan, Huizhou, Dongguan, Zhongshan, Jiangmen, and Zhaoqing).

4. Institutional Affiliation & Partnership Eligibility

  • Permitted Employing Entities: GBA lawyers may be employed by mainland Chinese law firms located in the nine cities or by joint-venture law firms (港澳与内地合伙联营律所) established between Hong Kong/Macao and mainland firms.
  • Prohibited Employment: GBA lawyers cannot be employed by mainland representative offices of foreign law firms or mainland representative offices of Hong Kong/Macao law firms.
  • Partnership Rights: GBA lawyers are explicitly permitted to become partners in mainland law firms based within the nine GBA cities.

II. Industry Impact & Compliance Considerations

1. Strategic Advantages for Cross-Border Enterprises

The updated framework enables multi-jurisdictional enterprises to receive integrated, cross-border legal services under a unified mainland law firm structure. By bridging common law (Hong Kong), civil law (Macao), and mainland socialist legal frameworks, GBA lawyers streamline communication, optimize cross-border corporate transactions, and enhance efficiency in international commercial arbitration.

2. Institutional Operational Adjustments for Mainland Law Firms

While incorporating Hong Kong and Macao legal talent strengthens mainland firms in cross-border M&A, cross-border insolvency, and international arbitration, it necessitates internal compliance upgrades:

  • Cross-Jurisdictional Conflict Audits: Establishing robust conflict-of-interest screening across mainland and offshore client rosters.
  • Data & Document Governance: Aligning cross-border client confidentiality, document retention, and fee-sharing protocols with mainland regulatory standards.
  • Client Due Diligence (KYC): Implementing unified Anti-Money Laundering (AML) and client identity verification workflows across cross-border engagements.

Conclusion

Ministry of Justice Order No. 151 marks a significant milestone in the institutional integration of legal services across the Guangdong-Hong Kong-Macao Greater Bay Area. By clarifying practice boundaries and opening law firm partnership pathways, the new rules provide a transparent legal environment for cross-border investments, international trade, and commercial dispute resolution.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-09

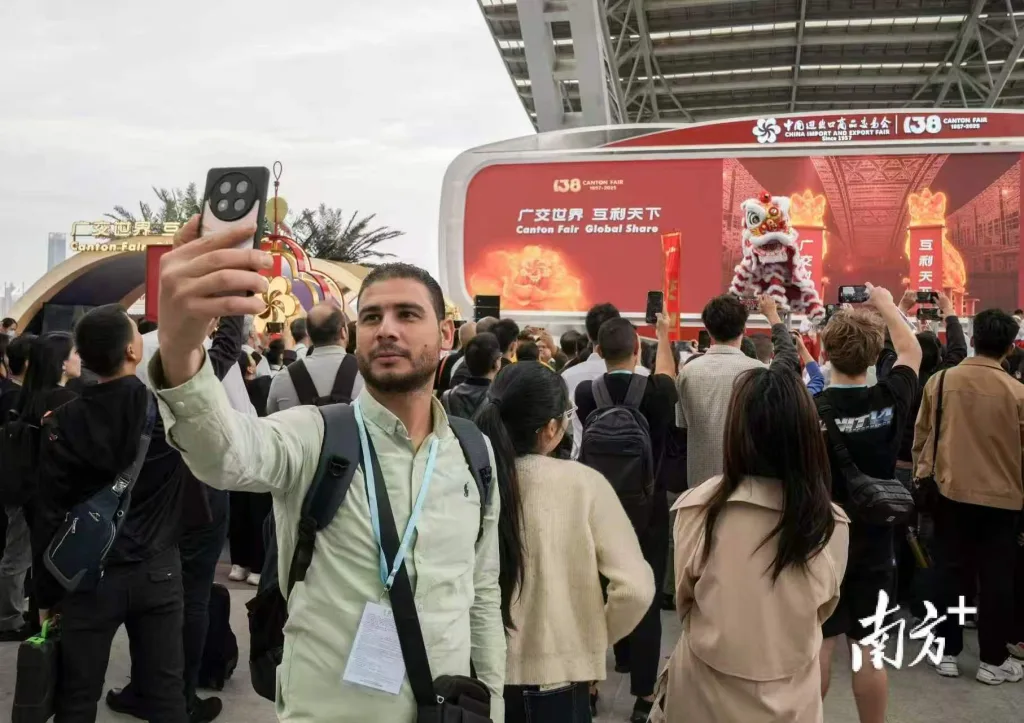
The 140th Canton Fair Series | Payment Security: Mitigating Collection Risks in Canton Fair Orders Through Landmark Precedents

As the 140th Canton Fair approaches, foreign buyers and Chinese exporters gather in Guangzhou to negotiate deals and finalize commercial contracts. While the exhibition provides extensive market access, transition from initial trade show leads to final payment collection involves serious legal hurdles: buyer identity verification, contract validity, payment routing, cargo title control, and judicial enforcement.

(Image Source: Nanfang+)

This article examines payment security across four operational stages—pre-contractual due diligence, contract drafting, performance management, and emergency dispute response—supported by key judicial precedents.

I. Case Studies: Payment Collection Disputes in Canton Fair Transactions

Case 1: Inaccurate Buyer Verification Creates Standing Barriers in Court

  • Fact Pattern: In a cross-border sales dispute heard by the Guangzhou Intermediate People's Court, plaintiff ADEL sued Algerian merchant SAMIR over unpaid apparel orders negotiated at the Canton Fair.
  • Judicial Determination: During proceedings, the court identified discrepancies between the defendant's submitted passport records and official entry-exit databases. Through cross-referencing name data and travel history, the court confirmed SAMIR's physical presence in Guangzhou during the relevant transaction window. Based on transaction logs, the court ordered SAMIR to pay over RMB 9.02 million in principal plus interest.
  • Legal Takeaway: When contracting with new overseas buyers, exporters must verify the buyer's legal identity, corporate registration, and signatory Power of Attorney (POA). Complete passport copies, business registries, purchase orders, and communication records should be preserved.

Case 2: Unilateral Order Cancellations and Seller Loss Allocations

  • Fact Pattern: In an international commercial arbitration administered by the Guangzhou Arbitration Commission, parties signed a $40,000 mineral water procurement contract during the Spring 2019 Canton Fair, backed by a $10,000 deposit. The buyer subsequently sought contract termination citing canceled downstream business events, triggering a dispute over incurred manufacturing costs.
  • Arbitral Outcome: The tribunal successfully mediated a settlement balancing accrued production, raw material, and warehousing costs against the deposit.
  • Legal Takeaway: Custom products or long-lead items carry significant upfront manufacturing costs. Contracts must incorporate explicit provisions governing payment milestones, cancellation penalties, termination rights, and cost-allocation mechanisms.

Case 3: Third-Party Remittances and Bank Account Freezing Risks

  • Fact Pattern: In an execution objection case handled by the Guangzhou Internet Court in April 2026, a Nigerian buyer challenged the court-ordered freezing of over RMB 10,000 in a domestic account belonging to an individual, Zhang. The buyer asserted the funds were trade remittances intended for a domestic supplier.
  • Judicial Determination: The court verified that during the Autumn 2025 Canton Fair, the buyer and Zhang executed a transaction exceeding RMB 150,000 without a formal written contract, relying instead on WeChat logs and Alipay transfers. By auditing chat histories, bank transfer receipts, and counterparty confirmations, the court verified the fund origins and released the freeze with the judgment creditor's consent.
  • Legal Takeaway: Discrepancies between the contract counterparty, remitter, and consignee create severe compliance risks under anti-money laundering (AML) rules. If third-party payment is necessary, parties must execute a formal Third-Party Payment Authorization Agreement and retain supporting payment instructions and bank slips.

(Image Source: The Paper)

II. Practical Recommendations Across Pre-Contractual, Contracting, and Performance Stages

1. Pre-Contractual Stage: Conducting Buyer Credit Due Diligence

  • Overseas Entity Verification: For new foreign buyers, exporters should request a Buyer Credit Report via China Export & Credit Insurance Corporation (Sinosure, [www.sinosure.com](https://www.sinosure.com).cn, Hotline: 95387) to review overseas corporate registration status, credit history, and pending litigation.
  • Domestic Intermediary Vetting: Where Chinese trading agents, forwarders, or local representatives are involved, conduct public registry searches (via Tianyancha or Qichacha) to review corporate status and court enforcement records.
  • Signatory Authorization: Inspect original Powers of Attorney (POA) and passport credentials for on-site negotiators. Exercise caution with counterparties lacking physical office addresses or operating exclusively via free webmail domains.

2. Contracting Stage: Formulating Clear & Enforceable Payment Arrangements

While Proforma Invoices (PI) are widely used to confirm orders, whether a PI constitutes a binding contract depends on its specific terms, price firming language, and execution history. For high-value or customized orders, parties should execute a formal contract covering subject matter, specifications, pricing, payment schedules, inspection, default liabilities, and dispute resolution.

  • Payment Milestones: Align production and delivery strictly with received payments (e.g., production commences only upon deposit clearance; document release occurs only after final balance settlement).
  • Documenting Third-Party Remittances: Require written triangular payment agreements signed by the buyer, remitter, and seller whenever payments originate from non-contractual bank accounts.
  • Liquidated Damages: Specify clear default interest rates and penalty terms for late payments, tailored to local enforcement standards under the governing law.

3. Performance Stage: Synchronizing Payments, Cargo Control, and Shipping Documents

  • Internal Control Triggers: Link ERP workflow stages—raw material sourcing, manufacturing, inspection, shipping booking, and original Bill of Lading (B/L) release—directly to verified bank payment receipts.
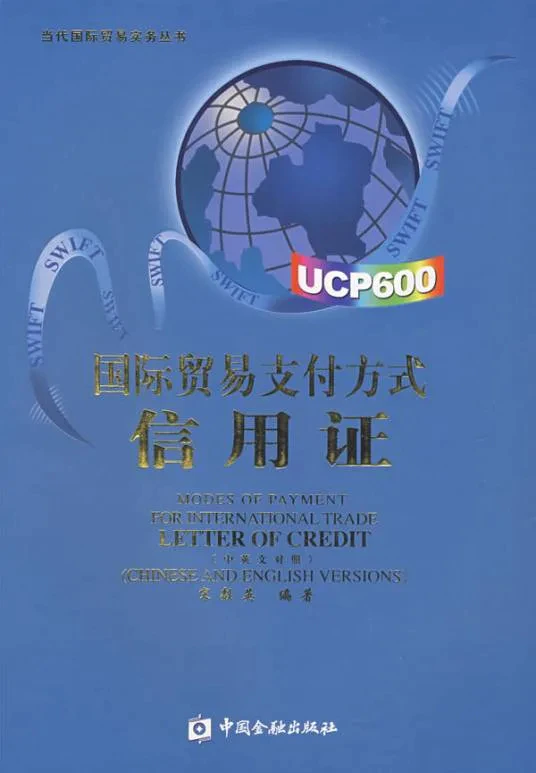
  • Letter of Credit (L/C) Compliance: Examine L/C terms for soft clauses or non-documentary conditions controlled solely by the buyer (e.g., buyer-issued inspection certificates). Conduct pre-presentation document audits for high-value transactions.
  • Export Credit Insurance: For open-account (O/A) or extended credit terms, leverage export credit insurance to mitigate buyer insolvency or political risks, ensuring full compliance with policy reporting and claim filing deadlines.

(Image Source: Baidu Baike)

III. Incident Response & Emergency Risk Mitigation Following a Dispute

When faced with payment delays, buyer default, order cancellation requests, or frozen account notifications, exporters should follow a structured three-step response protocol:

1.Fix and Preserve Primary Evidence:

Compile and organize all original contracts, Purchase Orders (PO), Proforma Invoices (PI), email threads, WhatsApp/WeChat logs, Bills of Lading (B/L), customs declarations, and bank remittance slips. Preserve complete digital chat histories on their original devices to ensure judicial admissibility.

2.Execute Cargo and Production Control Measures:

  • Unshipped Orders: Immediately evaluate pausing production and halting port dispatch.
  • Manufactured Goods: Assess alternative resale channels, re-routing, or modification options to minimize holding costs.
  • In-Transit Cargo: Review Incoterms, B/L types (e.g., Negotiable Original B/L vs. Telex Release), and payment status to issue hold-shipment instructions to freight forwarders or carriers.

3.Initiate Legal & Asset Preservation Procedures:

If payment default is evident, initiate arbitration or court litigation pursuant to the contractual dispute clause. Where risks of asset dissipation exist, apply for pre-litigation or interim property preservation orders (财产保全) to freeze the buyer's domestic assets or accounts.

(Image Source: Official Canton Fair Website)

Conclusion

The Canton Fair offers vital trade opportunities for international buyers and Chinese exporters. Securing transaction value requires diligence beyond exhibition negotiations—encompassing buyer vetting, structured contract terms, rigorous payment control, and proactive evidence preservation to ensure sustainable international growth.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-09-21

Can a Lender Recover a Large Private Loan in China? Interest Calculation and Guarantor Liability

Overview

Recovering a substantial private loan in China can involve more than proving that funds were advanced and remain unpaid. Where the transaction involves multiple loan agreements, extended interest payments, cross-border fund transfers and several guarantors, the outcome may depend on the validity of the agreements, the accounting of principal and interest, and whether each guarantor remains legally liable.

In this case, a US national advanced funds to a Chinese pawn company under two loan agreements. A separate asset management company and an individual had undertaken to provide joint and several guarantees. After the borrower stopped making payments, the lender commenced proceedings to recover the outstanding debt, interest and related obligations from the borrower and the guarantors.

The borrower challenged the validity of the loan agreements, while the parties also disputed how previous interest payments should be accounted for. The court upheld the validity of the loan agreements, recalculated the outstanding principal after adjusting the interest account, and held the individual guarantor liable. The claim against the corporate guarantor was dismissed on separate legal grounds.

The case demonstrates three important aspects of Chinese private lending litigation: a regulatory argument does not automatically invalidate a loan contract; a detailed financial reconciliation can be central to principal recovery; and the liability of each guarantor must be assessed independently.

The case remains subject to appeal. The outcome described below is therefore the first-instance result, not a final appellate determination.

Case Snapshot

ItemDetails
Case TypePrivate Lending Dispute
JurisdictionMainland China
CourtYangpu District People's Court, Shanghai
PartiesIndividual lender, pawn company, asset management company and individual guarantor
Cross-Border ElementThe lender is a US national
Original Claim ValueApproximately RMB 15 million
Main ClaimsRepayment of principal and interest
Additional ClaimsJoint and several liability of the guarantors
Key Legal IssuesContract validity, interest reconciliation, guarantee period and corporate guarantee requirements
First-Instance OutcomeSubstantial principal recovery upheld; individual guarantor held jointly and severally liable; claim against corporate guarantor dismissed
Procedural StatusAppeal pending
AttorneyYu Yuting
Law FirmNEO-ARK Law Firm

The Core Legal Issues

1. Does a loan agreement become invalid because the borrower is a pawn company?

The borrower argued that, as a pawn company, it was subject to industry-specific regulatory requirements and that lending to an individual in the circumstances of the case rendered the agreements invalid.

The lender disputed this interpretation.

The court accepted the position that the regulatory argument did not, by itself, invalidate the loan agreements. It found the agreements legally effective and proceeded to examine the parties' repayment obligations.

This distinction matters in Chinese contract litigation. A regulatory breach and contractual invalidity are not necessarily the same legal question. Whether a contract is invalid depends on the applicable legal rules and the specific circumstances, rather than solely on whether one party has referred to an industry regulation.

For lenders, this means that the defense to a loan claim should be assessed against the actual legal grounds for invalidity, not simply the existence of regulatory requirements affecting the borrower.

2. How should principal and interest be reconciled when the payment history is complex?

A substantial portion of the dispute concerned the accounting of funds already paid.

The lender had advanced funds under two separate loan agreements. The borrower had made interest payments for an extended period, but later stopped making payments. The parties disagreed over how the previous payments should affect the outstanding debt.

The lender's case relied on a systematic reconciliation of the loan balances and interest payments, supported by periodic account records and communications between the parties.

The court reviewed the payment history and adjusted the account to reflect the applicable legal limits on recoverable interest. It then determined the remaining principal obligation.

This illustrates why a loan recovery claim should not rely on a single headline balance. The calculation may need to distinguish between:

  • the principal actually advanced;
  • payments made during the loan term;
  • interest accrued under the agreements;
  • interest that can legally be claimed; and
  • the outstanding principal and interest after the appropriate adjustments.

A consistent reconciliation can help the court trace the movement of funds and determine the enforceable debt.

3. When can an individual guarantor be held jointly and severally liable?

The loan agreements included a guarantee from an individual.

The court found that the lender had asserted its rights against the individual guarantor within the applicable guarantee period. It therefore held the guarantor jointly and severally liable for the relevant repayment obligations.

This part of the case highlights the importance of reviewing not only the guarantee wording, but also the timing and manner in which the creditor exercises its rights.

Depending on the guarantee arrangement and applicable law, a creditor may need to establish that the relevant claim was made within the required period. A guarantee should not be assumed to remain enforceable indefinitely merely because the underlying debt has not been repaid.

4. Why was the corporate guarantor treated differently?

The asset management company had also undertaken to provide a guarantee. However, the court dismissed the claim against it on separate grounds involving the guarantee period and the absence of an effective corporate resolution.

The different outcomes demonstrate that a corporate guarantee and an individual's guarantee may raise distinct legal issues.

For a corporate guarantor, the analysis may include whether the guarantee was properly authorized under the applicable corporate governance requirements, as well as whether the creditor's rights were asserted within the relevant period.

The creditor's ability to recover from one guarantor therefore does not automatically establish liability for every other guarantor.

Legal Strategy

IssueLegal Approach
Contract validityAddress the specific legal basis for the borrower's invalidity argument
Multiple loan agreementsAnalyze each agreement and the associated payment obligations
Complex interest historyReconcile the payment records and distinguish legally recoverable interest from amounts requiring adjustment
Cross-border transfersEstablish the movement and receipt of the loan funds through consistent transaction records
Individual guaranteeEstablish the applicable guarantee terms and whether the creditor asserted its rights in time
Corporate guaranteeExamine guarantee authorization, corporate resolution requirements and the guarantee period
Recovery prospectsIdentify the parties against whom liability can legally be established

The strategy treated the debt calculation and guarantee issues as related but separate questions. Establishing the borrower's repayment obligation was only one part of the case; determining which additional parties could be held liable required a separate legal analysis.

Evidence and Financial Reconciliation

The dispute involved multiple transactions and a lengthy payment history. A central challenge was presenting the financial relationship in a form that could be checked against the agreements, payment records and communications.

The case illustrates the importance of maintaining a consistent record of:

  • loan agreements and amendments;
  • records showing the transfer and receipt of funds;
  • periodic loan and interest reconciliations;
  • payment records; and
  • communications concerning the balance, interest and repayment arrangements.

For confidentiality reasons, this case study does not disclose the underlying reconciliation figures, detailed payment history or internal evidence strategy.

Outcome

At first instance, the court upheld the validity of the loan agreements and ordered the borrower to repay the outstanding principal, together with applicable interest.

The court adjusted the financial account to reflect the legally recoverable interest and the treatment of previous payments.

The court also held the individual guarantor jointly and severally liable. However, the claim against the corporate guarantor was dismissed because of issues relating to the guarantee period and corporate authorization.

The individual guarantor subsequently appealed. The first-instance judgment should therefore not be described as a final resolution of the entire dispute.

For confidentiality reasons, the specific amount of principal recognized by the court, the detailed interest adjustments and the underlying financial calculations are not disclosed.

Why This Case Matters

Regulatory compliance arguments require legal analysis

A borrower cannot establish contractual invalidity merely by referring to industry regulation. The court must consider the relevant legal rules and the facts of the transaction.

Financial reconciliation can determine the recoverable debt

Where a loan has generated repeated payments over an extended period, the outstanding balance may differ materially from the original amount advanced.

A reliable reconciliation should distinguish the actual funds advanced, the payments received and the interest legally recoverable.

Guarantees must be assessed individually

The liability of an individual guarantor and a corporate guarantor may differ because the applicable legal requirements and factual circumstances are not necessarily the same.

Guarantee periods can affect recovery prospects

Creditors should identify the relevant guarantee period and take appropriate steps to preserve their rights. Delayed action can affect whether a guarantor remains liable.

Cross-border elements increase the importance of clear records

Where a lender is overseas or funds move across borders, the documentation should clearly establish the parties, the loan agreements, the transfer of funds and the payment history.

The presence of a foreign national does not, by itself, determine which law governs the dispute. The applicable law and jurisdiction must be assessed from the relevant contractual and factual circumstances.

Frequently Asked Questions

Can a lender recover a private loan from a company in China?

Potentially. The lender generally needs to establish the loan relationship, the funds advanced, the repayment obligations and the outstanding debt. The legal effect of the agreement and any defenses raised by the borrower must also be assessed.

Does a regulatory breach automatically invalidate a loan agreement in China?

No. A regulatory issue does not automatically establish contractual invalidity. The court must assess the applicable legal rules and the circumstances of the transaction.

Can a lender claim interest at the rate stated in a loan agreement?

Not necessarily in full. The enforceable amount depends on the applicable rules governing private lending interest, the relevant time period and the facts of the transaction.

Can an individual guarantor be liable even if a corporate guarantor is released?

Yes. The liability of each guarantor depends on the relevant guarantee terms, applicable legal requirements and the circumstances of the case. One guarantor's liability does not automatically determine another's.

Why is the guarantee period important in Chinese loan disputes?

The guarantee period can affect whether the creditor has preserved its rights against the guarantor. Creditors should review the applicable period and take the legally required steps within that time.

Can a US national bring a private lending claim in a Chinese court?

A foreign national may bring a civil claim before a Chinese court where the court has jurisdiction and the relevant procedural requirements are met. The applicable law and any cross-border issues depend on the circumstances of the transaction.

Key Takeaways

For lenders pursuing substantial private loan claims in China:

  1. Assess contract validity against the applicable legal rules rather than relying solely on regulatory arguments.
  2. Maintain a traceable record of funds advanced, payments received and interest calculations.
  3. Separate principal recovery from the calculation of legally recoverable interest.
  4. Analyze each guarantee independently.
  5. Check guarantee periods and corporate authorization requirements at an early stage.
  6. For cross-border transactions, preserve clear records of transfers, agreements and repayment communications.
  7. Distinguish first-instance results from final judgments when a case remains under appeal.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-09-17

Scroll to Top

+86 13503030053

BackToTop

Inquiry Inquiry Email Email Tel Tel

Request A Quote

×
Please enable JavaScript in your browser to complete this form.