Taste of Home: Neo-Ark Law Firm Youth Working Committee Hosts Mid-Autumn Hometown Culinary Contest
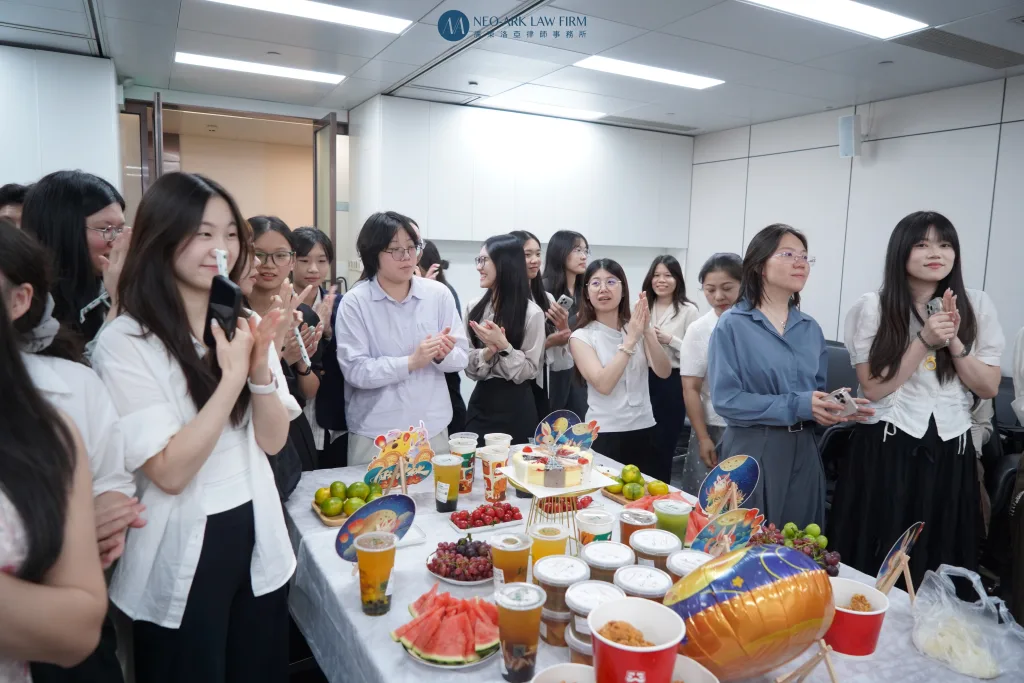
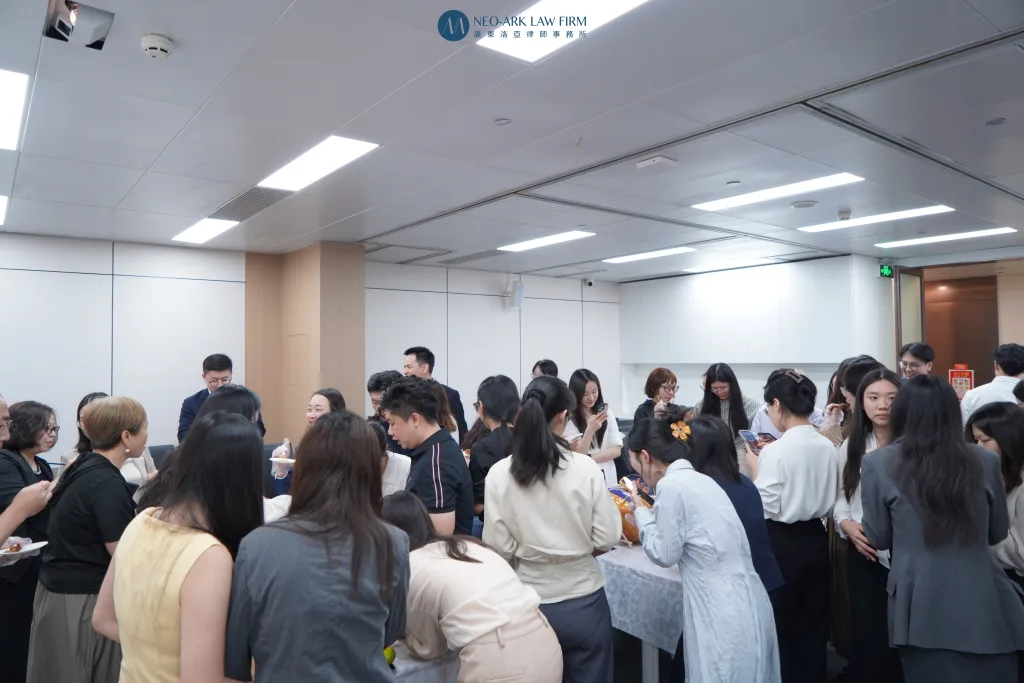
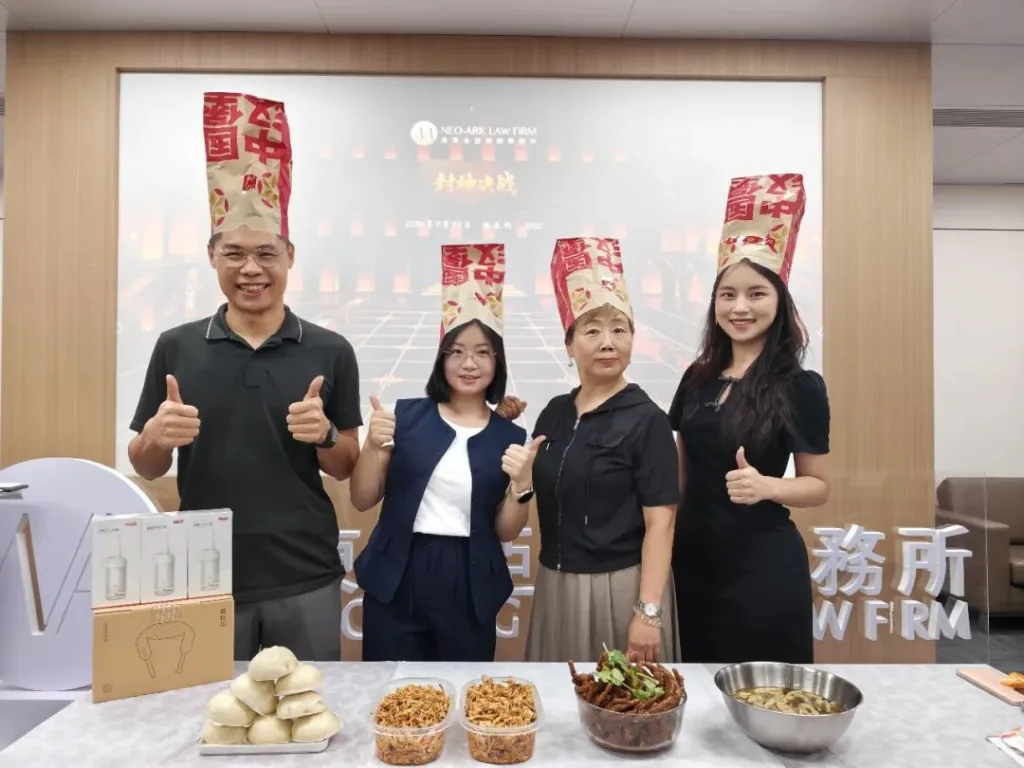
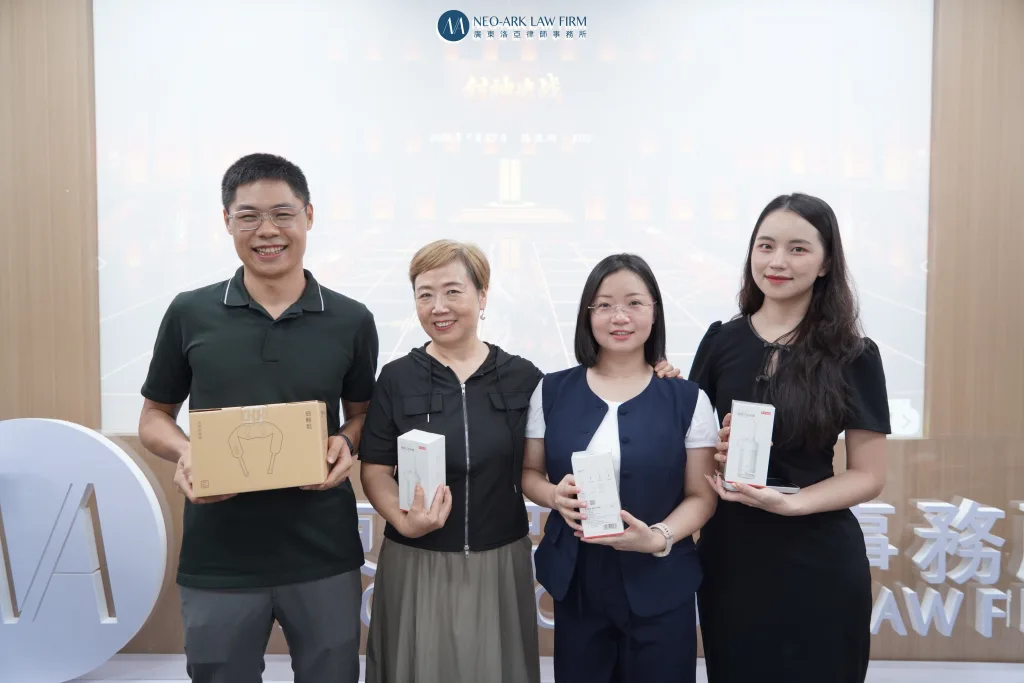
In celebration of the Mid-Autumn Festival, the Youth Working Committee of Guangdong Neo-Ark Law Firm hosted a specialized firm-culture event entitled the "Taste of Home" Culinary Contest (“一饭封神”家乡美食大赛).
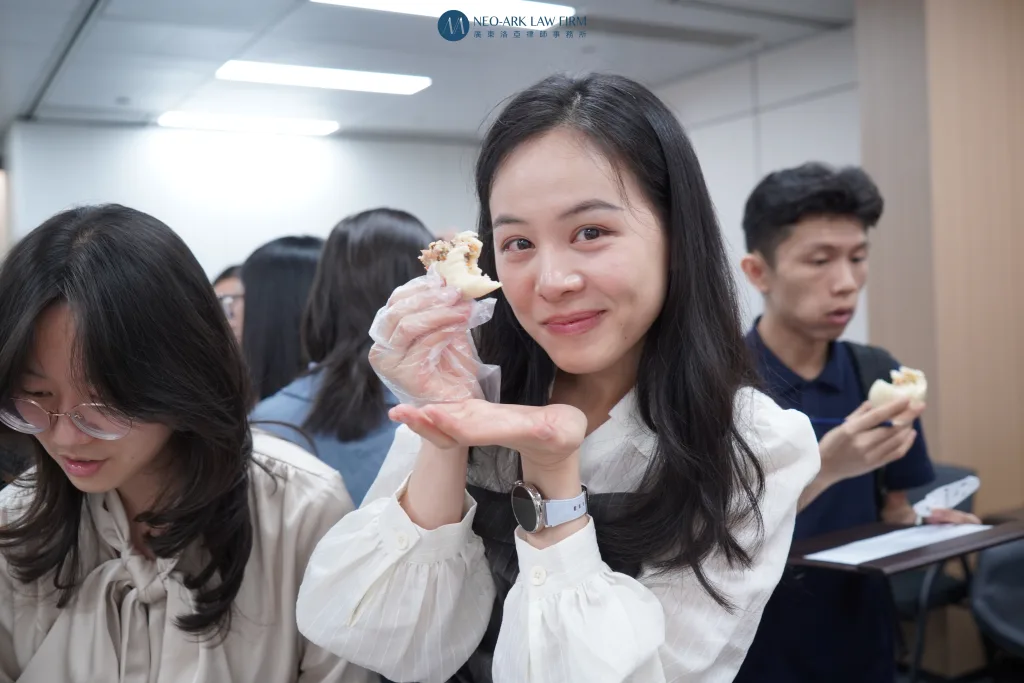
Designed to foster camaraderie and support work-life balance for legal practitioners, the event brought together attorneys, partners, and staff to share regional dishes from their respective hometowns. Beyond legal briefs and courtroom advocacy, the contest provided a warm platform for team bonding and cultural celebration ahead of the traditional holiday of reunion.
I. Culinary Creations & Hometown Traditions
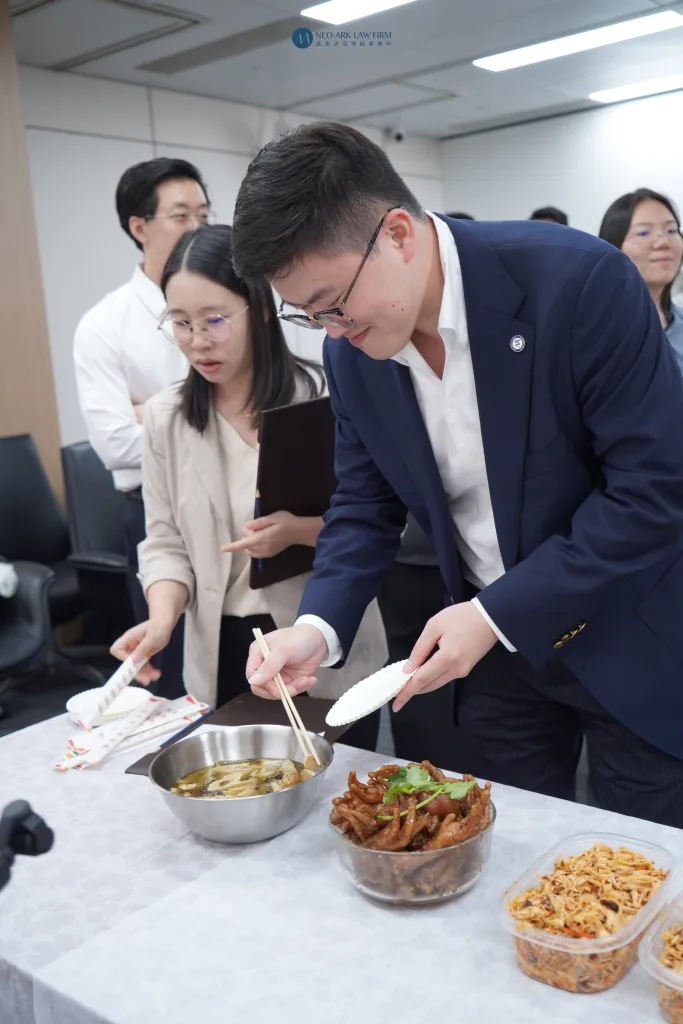
Stepping away from courtroom filings and legal research, participating attorneys showcased signature regional recipes, transforming the firm's event space into a vibrant culinary showcase:
"Jingxiang Handcrafted Buns" (荆乡手工包): Freshly steamed breakfast buns representing classic central Chinese comfort food and morning culinary traditions.
"Chilled Spicy Tofu Skin" (凉拌豆皮): A savory, cold-appetizer dish featuring traditional chili oil blend seasoning.
"Hand in Hand" (小手拉大手): A thoughtfully named multi-ingredient regional combination symbolizing intergenerational connection and mutual support.
"Bittersweet Harmony" (苦尽甘来): A creative dish blending bitter melon and sweet reduction, poetically reflecting perseverance and reward in both life and legal practice.
II. Professional Judging & Award Ceremony
To balance casual festivity with engaging competition, a panel of Senior Partners evaluated each dish using a 100-point scoring framework across five distinct metrics: Color, Aroma, Taste, Conceptual Meaning, and Visual Presentation (色、香、味、意、形).
After thorough tasting and scoring deliberation:
III. Strengthening Firm Culture & Community
Mid-Autumn Festival serves as a timeless symbol of togetherness and reflection in Chinese culture. For legal professionals who manage demanding litigation schedules and corporate advisory retainers, cultivating a supportive workplace community remains a priority at Neo-Ark Law Firm.
The Youth Working Committee continues to sponsor diverse team-building, mentorship, and wellness initiatives. By celebrating regional heritage and personal culinary traditions, Neo-Ark reinforces its commitment to an inclusive, collaborative culture that empowers attorneys both professionally and personally.
About the Author
Yu Yuting Partner | NEO-ARK Law Firm
LawyerYu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.
NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
Legal Guide for the 140th Canton Fair | Legal Services and Dispute Resolution
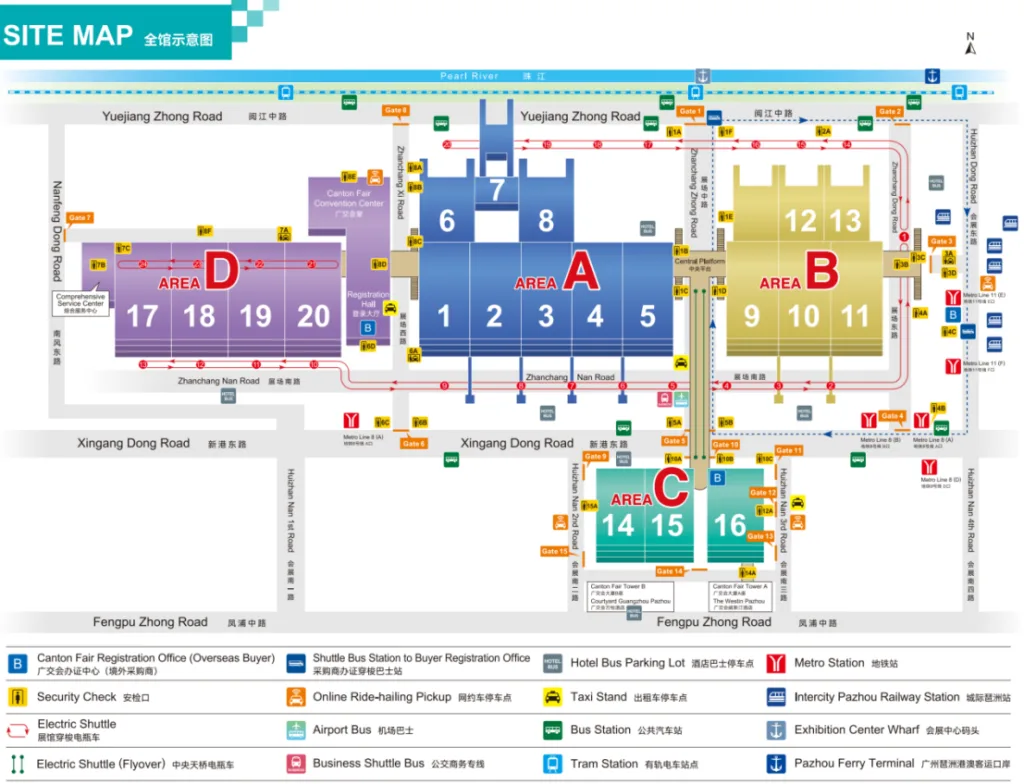
The 140th China Import and Export Fair (Canton Fair) takes place in Guangzhou from October 15 to November 4, 2026. Bringing together thousands of international buyers and domestic exhibitors, the fair serves as a vital global trade platform.
To help participants navigate legal issues and resolve commercial conflicts efficiently, this guide outlines on-site legal service stations, offline dispute resolution channels, online complaint mechanisms, and the duty schedule for Attorney Yuting Yu (Partner & Head of International Legal Affairs at Neo-Ark Law Firm), who will serve at the Guangzhou Foreign-Related Legal Advisory Service Port.
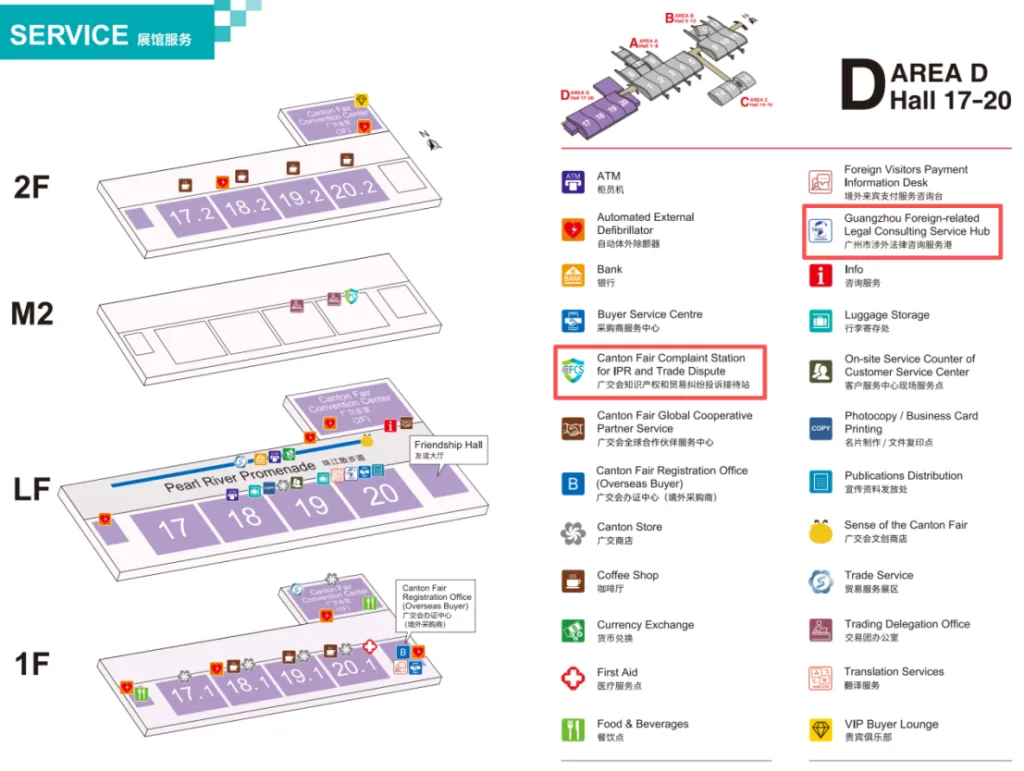
I. Three On-Site Legal Service Channels
Service Station
Core Service Scope
Recommended Scenarios
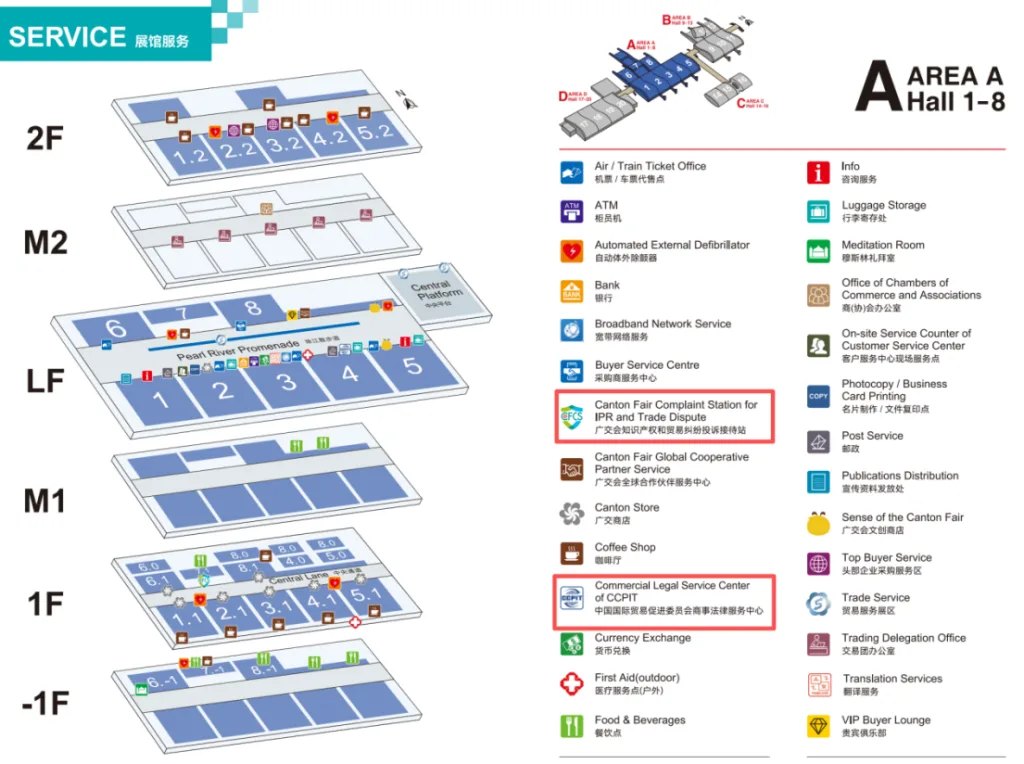
IP & Trade Dispute Complaint Station (知识产权和贸易纠纷投诉接待站)
Processes compliant intellectual property (IP) and trade dispute complaints under official Canton Fair guidelines.
On-site IP infringement allegations or trade contract disputes within Canton Fair jurisdiction.
CCPIT Commercial Legal Service Center (中国贸促会商事法律服务中心)
Enterprises seeking guidance on international trade laws, cross-border contracts, and commercial risk.
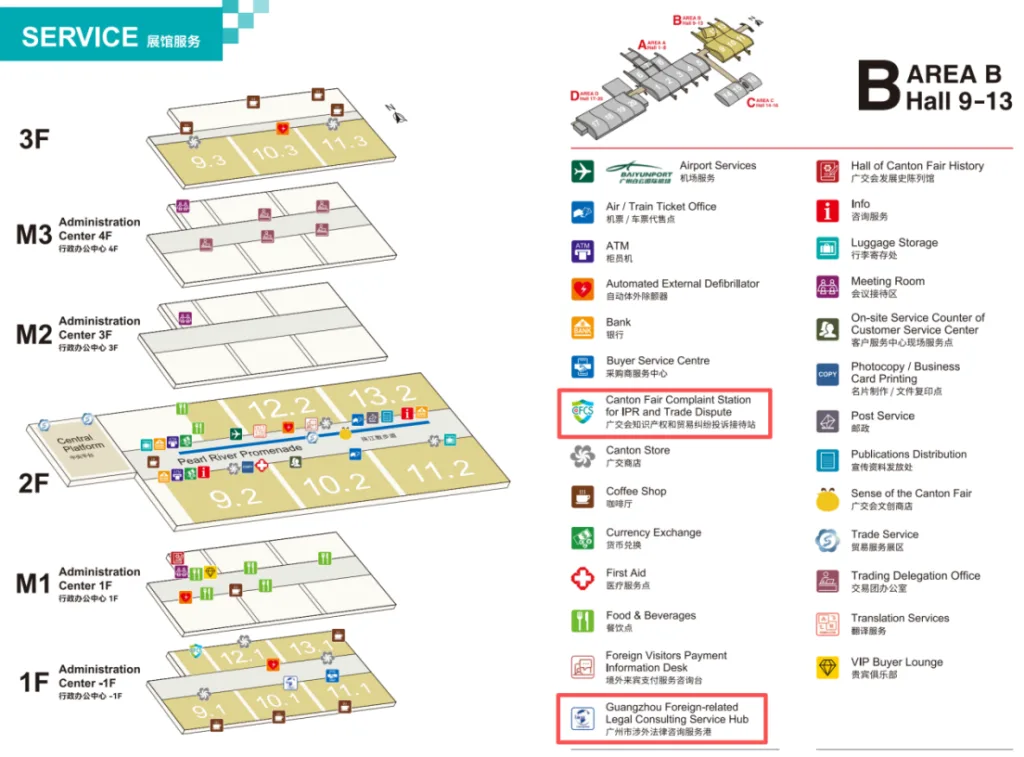
Guangzhou Foreign-Related Legal Service Port (广州市涉外法律咨询服务港)
Connects exhibitors with cross-border legal consulting, attorney services, arbitration, notarization, mediation, and foreign law ascertainment.
Overseas buyers and domestic suppliers requiring advice on governing laws, cross-border dispute resolution, or legal representation.
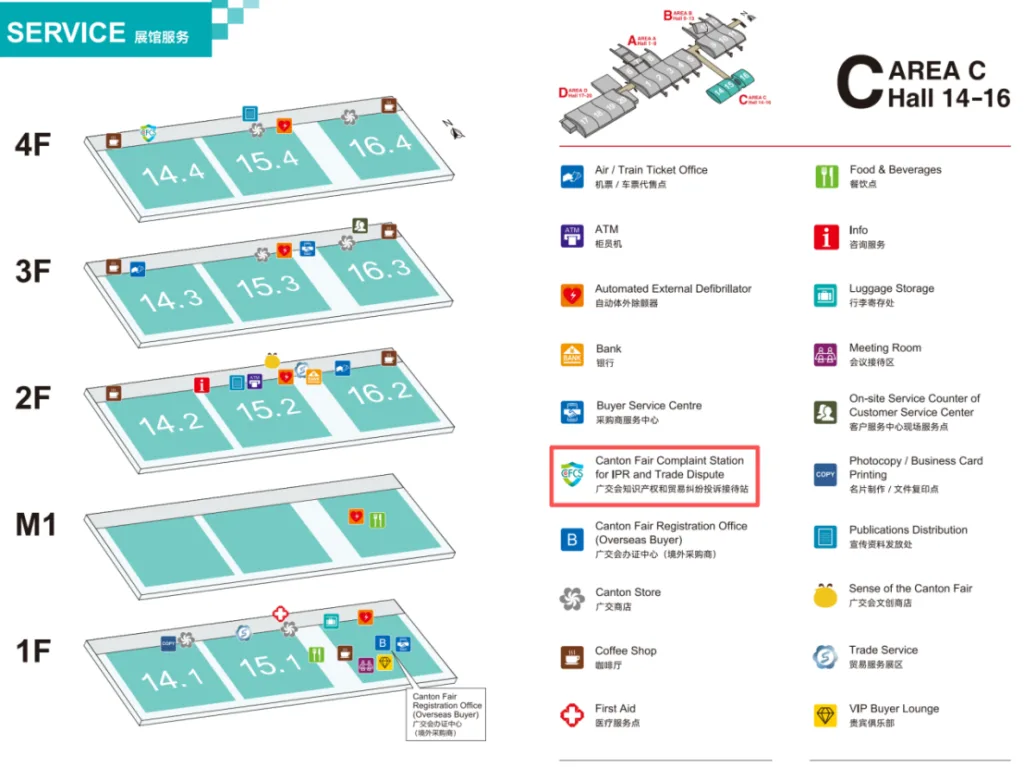
Zone Service Rules: IP and Trade Dispute Complaint Stations are stationed across Complex Areas A, B, C, and D. While Areas A and B accept both IP and trade dispute complaints, Areas C and D handle IP complaints exclusively. Trade dispute complaints occurring in Areas C or D must be submitted at the Area A or B complaint desks.
Recommended Desks:Complex Areas C & D (or Areas A & B) Complaint Reception Stations.
Action Steps: Prepare proof of IP ownership (trademark/patent certificates), evidence of alleged infringement, and booth/exhibitor identification before submitting a formal complaint.
2. Trade Disputes & Contract Breach
Recommended Desks:Complex Areas A & B Complaint Reception Stations; or the CCPIT Commercial Legal Service Center (Area A).
Action Steps: Gather signed contracts, Purchase Orders (PO), Proforma Invoices (PI), remittance receipts, delivery records, and communication logs to confirm eligibility under Canton Fair rules.
3. Cross-Border Contracts & Complex Legal Matters
Recommended Desks:Complex Areas B & D, Guangzhou Foreign-Related Legal Advisory Service Port.
Action Steps: Consult on-site attorneys regarding governing law clauses, arbitration clauses, cross-border asset preservation, and international litigation frameworks.
III. Online Dispute Resolution Pathways
For online and hybrid exhibitors, the official Canton Fair portal maintains a continuous online complaint system:
Online IP Complaints: Submit digital evidence and ownership certificates through the official Canton Fair website portal.
Trade Dispute Inquiries: Contact the official Canton Fair legal customer service hotlines:
Domestic Hotline:4000-888-999
International Hotline:+86 (20) 28-888-999
IV. On-Site Duty Schedule of Attorney Yuting Yu
Attorney Yuting Yu (Partner and Head of International Legal Affairs at Neo-Ark Law Firm) will be on duty at the Guangzhou Foreign-Related Legal Advisory Service Port on the following dates to deliver direct legal counseling for exhibitors and buyers:
[On-Site Duty Schedule: Attorney Yuting Yu]
 ├── October 19, 2026 | Area B, Booth 10.1
 ├── November 2, 2026 | Area D, Booth 20-4
 └── November 3, 2026 | Area B, Booth 10.1
October 19, 2026 (Phase 1): Complex Area B, Booth 10.1
November 2, 2026 (Phase 3): Complex Area D, Booth 20-4
November 3, 2026 (Phase 3): Complex Area B, Booth 10.1
About the Author
Yu Yuting Partner | NEO-ARK Law Firm
LawyerYu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.
NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-14
New Regulations for Hong Kong and Macao Lawyers Practicing in the Greater Bay Area: Where to Practice, Permitted Scope, and Partnership Eligibility
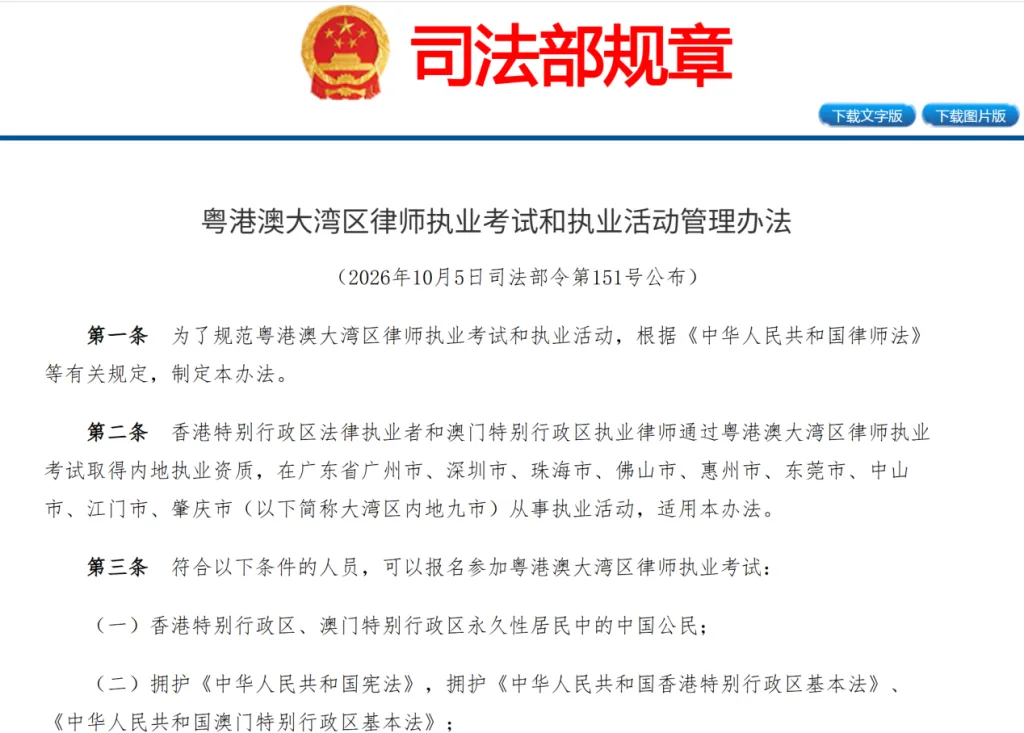
On October 5, 2026, the Ministry of Justice of the People's Republic of China promulgated Order No. 151, issuing the updated Measures for the Administration of the Examination and Practice Activities of Greater Bay Area Lawyers (粤港澳大湾区律师执业考试和执业活动管理办法), effective immediately. Comprising 12 comprehensive articles, the new regulations standardize qualifications, practice scopes, institutional affiliations, and partnership rights for legal practitioners from Hong Kong and Macao operating in the Greater Bay Area (GBA).
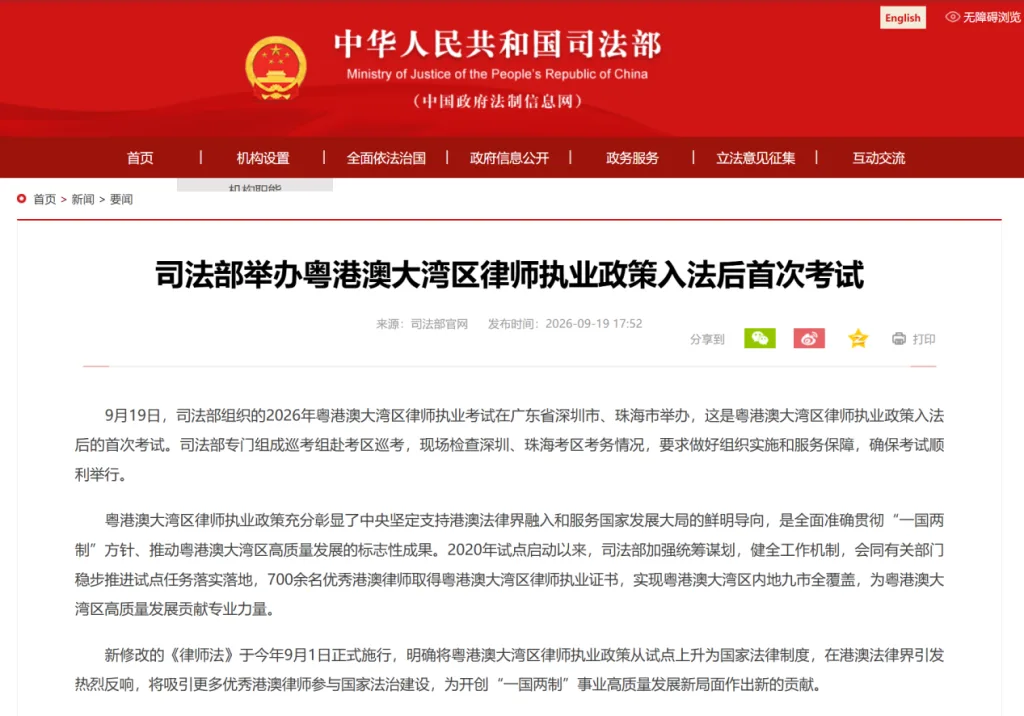
Legal practitioners from Hong Kong and Macao who pass the GBA Legal Qualification Examination and obtain mainland practice certificates are authorized to handle designated civil and commercial legal matters—encompassing both litigation and non-litigation services—across nine mainland GBA cities. Within this defined scope, GBA lawyers enjoy equal rights and bear equal obligations as mainland Chinese attorneys. As of September 2026, over 700 Hong Kong and Macao lawyers have successfully obtained GBA practice certificates.
I. Core Policy Highlights & Regulatory Framework
1. Institutionalization of the Examination
Examination Frequency: The GBA Legal Qualification Examination is officially established on a biennial schedule (held every two years).
Examination Locations: The primary examination center is located in Shenzhen, with an additional test center in Zhuhai depending on the volume of Macao-based applicants.
2. Eligibility Criteria for Applicants
Applicants must fulfill the following statutory requirements:
Citizenship & Status: Chinese citizens who are permanent residents of the Hong Kong Special Administrative Region (HKSAR) or Macao Special Administrative Region (MSAR).
Constitutional Compliance: Express support for the Constitution of the People's Republic of China and the Basic Laws of Hong Kong and Macao.
Practice Experience: A minimum of 3 cumulative years of legal practice experience. Hong Kong solicitors and barristers must not be subject to temporary qualification suspension; Macao practicing lawyers must not be under preventive suspension measures.
Language & Professional Ethics: High standard of professional ethics; demonstrated capability to draft legal documents in written Chinese and conduct professional activities in Mandarin (Putonghua).
Mandatory Training: Following examination passage, candidates must complete centralized training and pass the evaluation administered by the Guangdong Lawyers Association prior to applying for a practice certificate.
3. Permitted Practice Scope & Jurisdictional Connections
GBA lawyers are authorized to handle civil and commercial legal matters across nine mainland GBA cities (Guangzhou, Shenzhen, Zhuhai, Foshan, Huizhou, Dongguan, Zhongshan, Jiangmen, and Zhaoqing).
Permitted Employing Entities: GBA lawyers may be employed by mainland Chinese law firms located in the nine cities or by joint-venture law firms (港澳与内地合伙联营律所) established between Hong Kong/Macao and mainland firms.
Prohibited Employment: GBA lawyers cannot be employed by mainland representative offices of foreign law firms or mainland representative offices of Hong Kong/Macao law firms.
Partnership Rights: GBA lawyers are explicitly permitted to become partners in mainland law firms based within the nine GBA cities.
II. Industry Impact & Compliance Considerations
1. Strategic Advantages for Cross-Border Enterprises
The updated framework enables multi-jurisdictional enterprises to receive integrated, cross-border legal services under a unified mainland law firm structure. By bridging common law (Hong Kong), civil law (Macao), and mainland socialist legal frameworks, GBA lawyers streamline communication, optimize cross-border corporate transactions, and enhance efficiency in international commercial arbitration.
2. Institutional Operational Adjustments for Mainland Law Firms
While incorporating Hong Kong and Macao legal talent strengthens mainland firms in cross-border M&A, cross-border insolvency, and international arbitration, it necessitates internal compliance upgrades:
Cross-Jurisdictional Conflict Audits: Establishing robust conflict-of-interest screening across mainland and offshore client rosters.
Data & Document Governance: Aligning cross-border client confidentiality, document retention, and fee-sharing protocols with mainland regulatory standards.
Client Due Diligence (KYC): Implementing unified Anti-Money Laundering (AML) and client identity verification workflows across cross-border engagements.
Conclusion
Ministry of Justice Order No. 151 marks a significant milestone in the institutional integration of legal services across the Guangdong-Hong Kong-Macao Greater Bay Area. By clarifying practice boundaries and opening law firm partnership pathways, the new rules provide a transparent legal environment for cross-border investments, international trade, and commercial dispute resolution.
About the Author
Yu Yuting Partner | NEO-ARK Law Firm
LawyerYu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.
NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-09
Invalid Trust Loan Agreements in China: Limiting a Guarantor’s Liability
When a trust loan agreement is found invalid, the consequences may extend beyond the lender and borrower to a third party that has provided a guarantee. However, an invalid guarantee does not necessarily mean that the guarantor bears no liability. A court may examine whether the guarantor was at fault in causing the underlying contract to become invalid and whether compensation is warranted under the applicable law.
In this case, a trust company extended a substantial loan to a property development company after receiving a document purportedly issued in connection with a financing guarantee. The authenticity of that document was later challenged. An individual subsequently entered into a guarantee agreement to secure the borrower’s obligations.
The trust company brought proceedings before the Beijing High People’s Court, seeking to hold the individual liable for the borrower’s outstanding debt, interest, default interest and related recovery costs.
Representing the individual guarantor, the defense challenged the validity of both the underlying trust loan agreement and the guarantee agreement, and disputed the amount of interest-related losses claimed by the lender.
The court found both agreements invalid. However, because a criminal judgment had found that the individual used a false contract to represent the borrower in applying for the loan, the court also found that the individual was at fault in relation to the invalidity of the principal contract. The individual was therefore ordered to compensate the lender for a portion of specified losses that the borrower could not repay, rather than being held liable under the guarantee as originally agreed.
The case illustrates the distinction between contractual guarantee liability and compensation liability arising from fault associated with an invalid contract.
1. What happens to a guarantee when the underlying loan agreement is invalid?
A guarantee is intended to secure an underlying obligation, but its legal effect must be assessed under the applicable law and the circumstances of the case. Where the principal contract is invalid, the guarantee agreement may also be invalid, subject to the relevant legal framework.
In this case, the lender sought to enforce an individual guarantee securing a substantial trust loan. The defense argued that the underlying trust loan agreement was invalid and that the guarantee agreement should likewise be found invalid.
The court accepted the challenge to the validity of both agreements.
This did not, however, automatically eliminate every possible form of liability. The court separately considered whether the individual guarantor had contributed to the invalidity of the principal contract and whether compensation was justified.
The practical distinction is important: a claim for performance under a valid guarantee is legally different from a claim for compensation arising from fault associated with an invalid contract.
2. Can a guarantor still be liable if the guarantee agreement is invalid?
Potentially, yes. Depending on the applicable law, the reasons for invalidity and the parties’ respective fault, a court may consider whether a party should compensate the other side for losses resulting from an invalid contract.
In this case, a criminal judgment had found that the individual used a false contract while representing the borrower in the loan application process. The court considered this finding when assessing the individual’s fault in relation to the invalidity of the principal contract.
As a result, the individual was ordered to bear a proportion of specified losses that the borrower could not repay.
This outcome demonstrates why a defense should distinguish between denying liability under the guarantee itself and addressing any separate compensation claim based on fault. Invalidity and liability are related issues, but they are not interchangeable conclusions.
3. How can a defense challenge excessive interest and default interest claims?
A lender’s claim may include principal, contractual interest, default interest and recovery expenses. Each component must be assessed according to the applicable law, the contract’s validity and the evidence supporting the claimed loss.
Here, the defense challenged not only the validity of the loan and guarantee agreements but also the amount of interest-related losses claimed by the lender.
The court found the trust loan agreement invalid and determined that the borrower’s liability for the resulting loss of use of funds should be calculated by reference to the applicable one-year benchmark lending rate of the People’s Bank of China under the legal framework applied in the case. It did not simply enforce the lender’s original contractual interest and default interest claims as presented.
The case illustrates the importance of examining the legal basis of each claimed amount. Where the underlying agreement is invalid, contractual interest provisions may not determine the measure of recoverable loss.
The precise rules and interest benchmarks applicable to a dispute depend on the relevant dates, transitional provisions and governing law.
4. Why does fault in causing contractual invalidity matter?
When a contract is invalid, a court may need to examine the conduct of the parties and determine whether any party should bear responsibility for resulting losses. The consequences are fact-specific and depend on the legal rules applicable to the transaction.
In this dispute, the court did not treat the individual’s invalid guarantee as the end of the analysis. It considered the criminal judgment concerning the individual’s conduct in the loan application process and found fault relevant to the invalidity of the principal contract.
The resulting compensation obligation was distinct from the guarantee obligation originally asserted by the lender.
For guarantors, this means that a legal defense should assess the basis and scope of each potential claim, including whether the lender is seeking contractual performance, restitution or compensation arising from fault.
Legal Strategy and Case Outcome
Issue
Court’s Determination
Validity of the trust loan agreement
The agreement was found invalid.
Validity of the guarantee agreement
The guarantee agreement was also found invalid.
Borrower’s liability
The borrower was responsible for the loss of use of funds arising from the invalid loan agreement, assessed under the applicable legal framework.
Individual guarantor’s conduct
The court considered the relevant criminal judgment and found the individual at fault in relation to the invalidity of the principal contract.
Scope of the individual’s liability
The individual was ordered to compensate the lender for a portion of specified losses that the borrower could not repay, including relevant interest-related losses and reasonable legal fees.
Original contractual guarantee claim
The individual was not held liable simply by enforcing the guarantee as written; the court assessed liability in light of the invalid agreements and the individual’s fault.
The court accepted the defense’s position that the principal loan agreement and the guarantee agreement were invalid. It nevertheless imposed a limited compensation obligation on the individual because of the fault found in connection with the principal contract’s invalidity.
The precise amounts claimed and the detailed calculation of liability are omitted to protect client confidentiality.
Practical Lessons for Guarantee and Trust Loan Disputes in China
Examine the validity of the underlying transaction first. A guarantee dispute may depend on whether the principal contract is valid and whether the underlying obligation can be enforced as agreed. The documents and circumstances surrounding the original financing should be reviewed carefully.
Separate guarantee liability from compensation liability. A finding that a guarantee is invalid does not necessarily resolve every claim against the guarantor. The legal basis, relevant conduct and scope of any alleged loss must be analyzed separately.
Assess the significance of related criminal findings. Where a criminal judgment concerns conduct connected with the loan application or contract formation, its findings may be relevant to the civil court’s assessment of fault. The precise effect depends on the issues decided and the applicable law.
Challenge each component of the lender’s claim. Principal, contractual interest, default interest and legal expenses may be governed by different legal considerations. If the underlying contract is invalid, the lender may not automatically recover every amount calculated under its original terms.
Determine the scope of liability by reference to the governing law. Compensation arising from an invalid contract is not automatically equivalent to the entire debt or the full amount demanded by the lender. The applicable legal framework and the court’s findings determine the nature and extent of any liability.
Frequently Asked Questions
Does an invalid loan agreement automatically release the guarantor in China?
No. The invalidity of the principal contract may affect the guarantee agreement, but it does not automatically exclude every possible claim against the guarantor. Depending on the circumstances and applicable law, a court may consider separate compensation liability based on fault.
Can a guarantor be ordered to pay compensation even if the guarantee agreement is invalid?
Potentially, yes. A court may assess whether the guarantor was at fault in relation to the invalidity of the underlying contract and whether compensation is warranted under the applicable rules. Such liability is fact-specific and should not be assumed in every case involving an invalid guarantee.
Can a lender recover contractual interest when the underlying loan agreement is invalid?
The outcome depends on the legal basis of the claim and the rules applicable to the transaction. A court may assess the loss associated with the use of funds under the rules governing invalid contracts rather than simply enforce the contractual interest provisions.
Can a guarantor challenge a claim for excessive default interest and legal expenses?
Yes. The guarantor may dispute the legal basis, calculation and recoverability of the amounts claimed, subject to the procedural rules and the circumstances of the case. Whether the challenge succeeds depends on the evidence and applicable law.
Is compensation liability the same as joint and several guarantee liability?
No. Joint and several guarantee liability arises from an enforceable guarantee obligation. Compensation liability associated with an invalid contract has a different legal basis and depends on the applicable rules and the court’s findings concerning fault and loss.
Conclusion
This case demonstrates that a guarantee dispute involving an invalid trust loan agreement requires a careful distinction between contractual enforcement and fault-based compensation. Although the court found both the loan agreement and guarantee agreement invalid, it separately assessed the individual guarantor’s conduct and imposed a limited compensation obligation.
For parties involved in trust financing and guarantee disputes in mainland China, reviewing the validity of the underlying transaction, the conduct of the guarantor and the legal basis for each claimed loss can be central to determining the proper scope of liability.
About the Author
Yu Yuting Partner | NEO-ARK Law Firm
LawyerYu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.
NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
2026-10-06
Enforcing Renewed Loan Agreements in China: Debt Classification and Interest Reconciliation
Large private lending disputes can involve years of renewed agreements, substantial transfers and repeated interest payments. When a borrower later argues that the relationship was a form of investment or financial cooperation rather than a loan, the creditor may need to establish the true nature of the transactions and reconcile the historical accounts.
In this case, a US national entered into multiple renewed loan agreements with an individual borrower in China. Two companies were named as joint and several guarantors. After interest payments stopped, the lender commenced proceedings before the Shanghai Financial Court to recover the outstanding principal and interest.
The first-instance court upheld the validity of the loan agreements and recognized the underlying relationship as borrowing rather than a risk-sharing investment arrangement. After reviewing the historical payments and interest calculations, the court determined the outstanding debt. The claims against the two corporate guarantors were unsuccessful because the guarantees were found invalid and the applicable guarantee periods had expired.
The case illustrates the importance of documenting the continuity of a long-term lending relationship, establishing the legal character of renewed agreements and reconciling principal and interest under the rules applicable to the transactions.
First-instance judgment; within the appeal period as reported
Key Legal Issues
1. Can renewed agreements remain valid loan contracts when the borrower alleges an investment or cooperation arrangement?
A dispute over the legal nature of a funding arrangement can materially affect the creditor’s recovery rights. A borrower may argue that funds were advanced as part of a broader commercial cooperation rather than a conventional loan, particularly where the parties have signed successive agreements over several years.
In this case, the borrower challenged the characterization of the relationship as a loan. The lender maintained that the arrangement involved repayment obligations and fixed returns rather than an investment under which the lender assumed the underlying business risks.
The first-instance court accepted the loan characterization and upheld the relevant renewed agreements and confirmation document.
The case demonstrates that contractual labels alone may not resolve a dispute over the nature of a transaction. The substance of the arrangement, the parties’ actual obligations and the history of performance can all be relevant to determining whether the relationship constitutes a loan or another form of commercial arrangement.
2. How can a creditor establish the outstanding balance under multiple renewed loan agreements?
Where a lending relationship continues through successive agreements, the outstanding balance may be affected by historical payments, interest settlements and adjustments made over time. A creditor must establish not only the original amount advanced but also how the balance developed throughout the relationship.
Here, the court considered the multiple loan agreements and the parties’ historical financial dealings when determining the outstanding debt. It accounted for interest previously paid and the relevant compensation associated with the use of funds before calculating the balance recoverable under the first-instance judgment.
The result illustrates the distinction between the original principal recorded in the agreements and the amount ultimately recognized as outstanding after the court’s accounting assessment.
For creditors, consistent records of the contractual history and payment arrangements can help explain how a debt has evolved and reduce uncertainty over the amount claimed.
3. How are historical interest payments treated when determining the remaining principal?
Long-term lending relationships may involve payments that need to be reconciled against the interest legally recoverable under the applicable rules. Depending on the facts and the governing provisions, the court may need to consider whether previous payments exceed the permitted interest and how any resulting adjustment affects the outstanding balance.
In this case, the court examined the historical interest payments and the parties’ account records. After its assessment of the interest and funding-related compensation, it determined the principal remaining payable by the borrower.
The applicable interest rules can depend on the agreement date, the relevant period and transitional provisions. The rate and accounting treatment applied in an individual judgment should therefore not be assumed to govern every private lending arrangement.
4. Why might corporate guarantors be released even when the borrower remains liable?
A creditor may obtain a judgment against a borrower without necessarily establishing an enforceable guarantee against every company named in the agreements.
In this case, the two corporate guarantees were found invalid, and the applicable guarantee periods had also expired. The first-instance court therefore did not impose guarantee liability on the companies.
This outcome highlights the need to assess the validity of each guarantee and the timing of actions required to preserve rights under it. The borrower’s repayment obligation and a third party’s guarantee obligation are legally distinct questions; success on the underlying debt claim does not automatically establish liability against every guarantor.
Legal Strategy and Case Outcome
Issue
Court’s First-Instance Determination
Nature of the transaction
The relationship was recognized as borrowing rather than the alleged investment or financial cooperation arrangement.
Renewed agreements
The relevant loan agreements and confirmation document were upheld as valid.
Outstanding principal
The court determined the remaining principal after reviewing historical payments and relevant adjustments.
Interest
The court assessed the historical interest and ordered payment of overdue interest under the terms and legal analysis reflected in its judgment.
Corporate guarantees
The two companies were not held liable because the guarantees were found invalid and the applicable guarantee periods had expired.
Procedural status
The case was within the appeal period following the first-instance judgment, as reported.
The first-instance court ordered the individual borrower to repay the outstanding principal and overdue interest. It did not impose guarantee liability on the two corporate defendants.
The precise judgment amount, detailed interest adjustments and litigation-cost allocation are omitted to protect client confidentiality. The first-instance result should not be treated as final while the appeal period remains relevant.
Practical Lessons for Large Private Lending Disputes in China
Document each renewal clearly. When a loan is renewed repeatedly, the agreements should make the continuing repayment obligation and the relationship to earlier transactions understandable. Confirmation documents and payment records may also help establish the continuity of the debt.
Establish the substance of the funding arrangement. Where the borrower characterizes a transaction as investment or cooperation, the parties’ actual obligations, allocation of commercial risk and payment arrangements may be important to the legal analysis.
Maintain a consistent historical account. For long-term lending, a coherent record of principal, payments, interest and adjustments can help explain the outstanding balance. Calculations should be reconcilable with the underlying transaction records and the legal rules applicable to each relevant period.
Review guarantee validity and timing separately. Corporate approval requirements and guarantee periods can determine whether a company can be held liable. These issues should be assessed independently of the borrower’s underlying repayment obligation.
Distinguish a first-instance result from a final outcome. A judgment that remains subject to appeal may be challenged or changed. Public case descriptions should accurately identify the procedural stage and avoid presenting the first-instance result as conclusively final.
Frequently Asked Questions
Can a renewed loan agreement be enforced in China if the borrower says the transaction was an investment?
Potentially, yes. The court may examine the substance of the arrangement, the parties’ contractual obligations, how returns were structured and whether the lender assumed commercial risks. The characterization depends on the facts and applicable law, not simply on the terminology used by one party.
How does a court calculate the outstanding principal in a long-term private lending dispute?
The court may review the original advances, renewed agreements, repayments, historical interest payments and other relevant adjustments. The resulting balance depends on the evidence and the legal rules applicable to the transaction and the relevant periods.
Can a company avoid guarantee liability if its guarantee is invalid?
An invalid guarantee may prevent enforcement of the guarantee as written, but the legal consequences depend on the circumstances and applicable law. Any separate compensation liability requires its own legal basis and should not be assumed automatically.
Does the borrower’s liability depend on whether the corporate guarantees are enforceable?
Not necessarily. The borrower’s contractual repayment obligation and a guarantor’s liability are distinct. A borrower may remain liable even where claims against corporate guarantors fail.
Is a first-instance judgment final in China?
Not necessarily. Where an appeal remains available or has been filed, the first-instance judgment should be described according to its actual procedural status. The final outcome may differ if the judgment is changed on appeal.
Conclusion
This case illustrates the challenges of recovering a substantial debt arising from multiple renewed loan agreements. Establishing the true nature of the transaction, documenting the continuity of the debt and reconciling historical interest are central to determining the amount legally recoverable. At the same time, guarantee validity and the applicable guarantee periods must be examined separately from the borrower’s repayment obligation.
For creditors involved in long-term private lending in mainland China, careful contractual documentation and a consistent financial record can help clarify the debt and support a more reliable assessment of recovery prospects.
About the Author
Yu Yuting Partner | NEO-ARK Law Firm
LawyerYu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.
NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.
 Skip to content