News

News

Inclusion ▪ Respect ▪ Professionalism ▪ Excellence

Following a landmark settlement stemming from the European Court of Justice (CJEU) ruling in the Lassana Diarra v. FIFA case, FIFA officially adopted the revised Regulations on the Status and Transfer of Players (2027 RSTP), set for global implementation on January 1, 2027.About Ushttps://www.pinsentmasons.com/out-law/news/fifa-announces-new-player-transfer-regulations-following-diarra-settlement#:~:text=Revamped%20football%20transfer%20rules%20announced%20by%20FIFA,ruling%2C%20they%20did%20not%20go%20far%20enough.
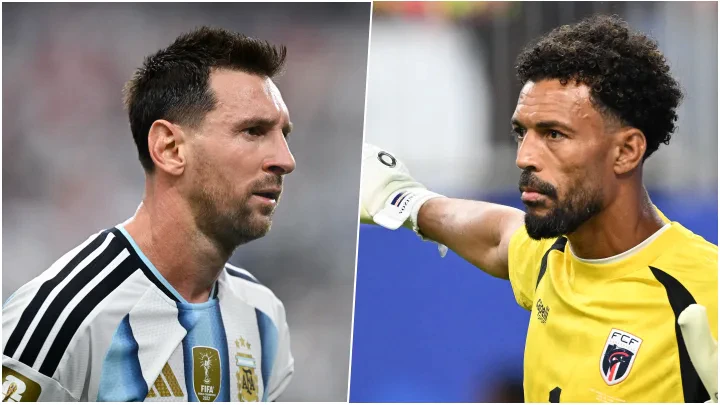
(Lionel Messi and Cape Verde goalkeeper Vozinha competing during the World Cup Round of 32. Source: Xinhua News Agency)

The CJEU determined that FIFA's former transfer restrictions unlawfully impeded the free movement of workers and restricted market competition under EU law. Departing from unilateral rulemaking, FIFA formulated these amendments through collective negotiation via the newly established Global Social Dialogue Platform, alongside FIFPRO, the European Club Association (ECA), and the World Leagues Association (WLA).

This landmark shift marks the evolution of global football governance from unilateral regulatory authority to structured collective bargaining.
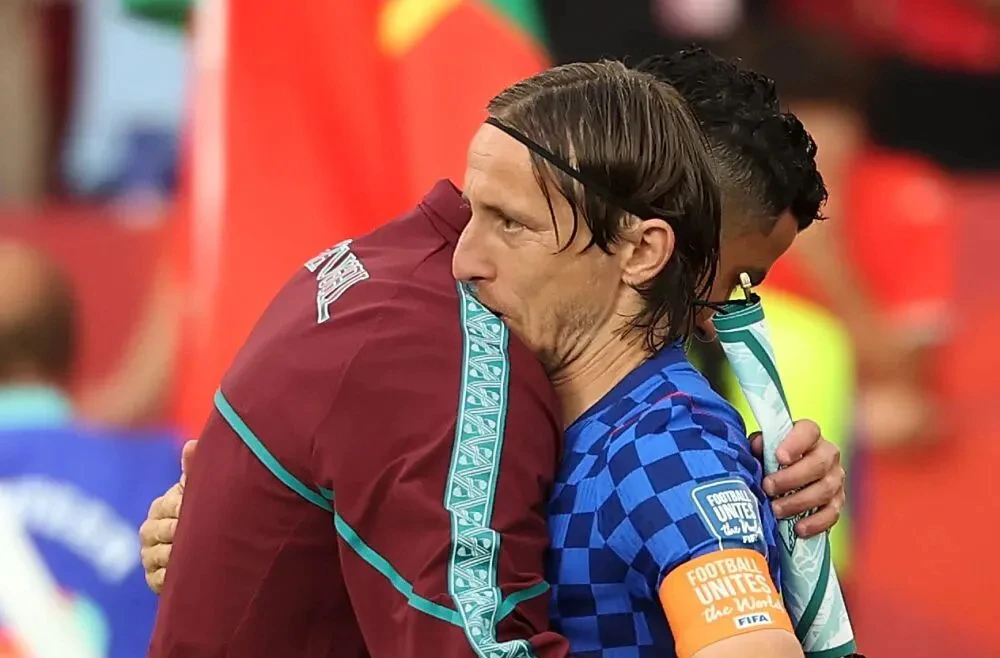
(Cristiano Ronaldo and Luka Modrić on the pitch during the World Cup Round of 32. Source: Xinhua News Agency)

I. Scope and Universal Application

  • Regulated Entities: Applies universally to professional football players, professional clubs, national member associations, licensed football agents/intermediaries, and sports dispute resolution bodies (such as the FIFA Football Tribunal and the Court of Arbitration for Sport).
  • Geographic Jurisdiction: Universally binding across all 211 FIFA member associations worldwide.

II. Core Structural Changes: Articles 17–21 Breakdown

1. Standardization of Contract Breach Calculations (Article 17)

Historically, unilateral contract terminations without just cause exposed buying clubs to unpredictable compensation awards and joint liability, discouraging the signing of players in contract disputes. The 2027 RSTP introduces two key structural fixes:

  • Enforceability of Liquidated Damages Clauses: Validates pre-agreed contractual liquidated damages (buyout clauses). When a buying club meets the pre-agreed valuation, the releasing club cannot impose artificial procedural barriers.
  • Standardized Compensation Benchmarks: Establishes predictable compensation floors tied to the residual value of the unfulfilled employment contract, eliminating speculative parameters such as unproven expected commercial revenue. Furthermore, buying clubs face joint financial liability only if proven to have actively induced the breach.
2. Statutory 5% Transfer Fee Equity Cut for Players (Article 21)

For the first time in football history, players hold a statutory right to participate directly in the financial value generated by their transfer fee:

  • Lower-Income Players (Earning under €150,000 / year): Entitled to a non-waivable, mandatory 5% direct cut of the fixed transfer fee received by the releasing club.
  • Higher-Income Players: May partially negotiate or waive their entitlement. However, the net payment received cannot fall below the higher of:
    • (a) The player’s total fixed annual salary during their final contract year; or
    • (b) 2.5% of the total fixed transfer fee.
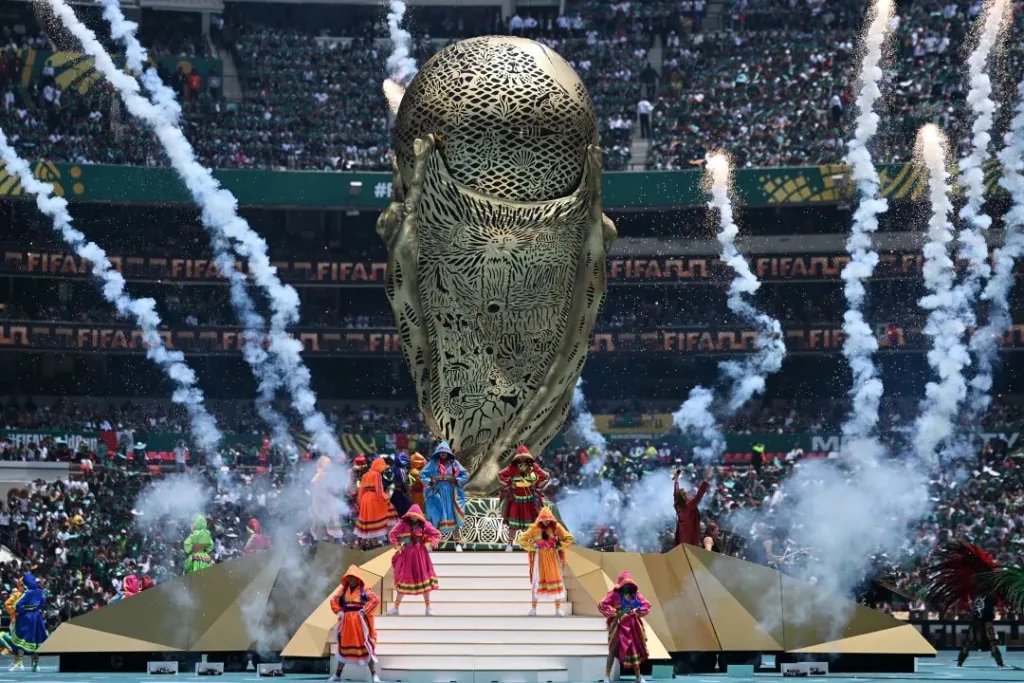
(Opening ceremony performance at the FIFA World Cup. Source: Xinhua News Agency)

3. 5-Year Professional Contracts for Homegrown Academy Minors (Article 18)

To balance player mobility with academy investment protection, the default 3-year cap on professional contracts for minors under 18 can now be extended up to 5 years, provided:

  • The player has been registered with the club's academy for at least 20 months or two consecutive competitive periods.
  • The contract complies with local minimum wage statutes and respects annual squad allocation limits for long-term youth deals.
4. Tripartite Rulemaking via the Global Social Dialogue Platform

Substantive regulatory modifications regarding transfer frameworks, player welfare, international match calendars, and health standards can no longer be unilaterally enacted by FIFA. Future regulatory changes require formal consensus between FIFA, player unions (FIFPRO), and employer representatives (ECA, WLA) through the Global Social Dialogue Platform.

III. Strategic Legal & Industry Impact

  • Redefining Contractual Nature: Employment agreements transition from restrictive, life-binding lock-ins to redeemable commercial employment contracts with transparent buyout valuations and exit mechanisms.
  • Prohibition of Constructive Dismissal ("Solo Training"): Explicitly classifies squad exclusions, forced reserve-team demotions, or isolated training regimes as material employer breaches. Affected players gain immediate statutory grounds to terminate their contract for just cause and claim full residual compensation.
  • Sophisticated Financial Planning: Cross-border transfer budgets must account for mandatory 5% player distributions, agent commissions, training rewards, and an annualized 8% default interest penalty on late payments, squeezing unearned transfer markups.

IV. Star Player Case Studies Under the 2027 Framework

  • Constructive Breach Protections (The Mbappé Scenario): Unilateral exclusions from pre-season tours or isolated training routines—previously legal gray areas—are now statutory employer breaches. Players can immediately cancel their contract for just cause and claim full remaining salary payments.
  • Standardized Buyout Clauses (The Haaland Model): Pre-agreed buyout clauses, historically limited to elite negotiations, become the global statutory baseline. Acquiring clubs like Real Madrid or Manchester City can secure talent cleanly by meeting clear buyout thresholds without facing prolonged contractual holds.
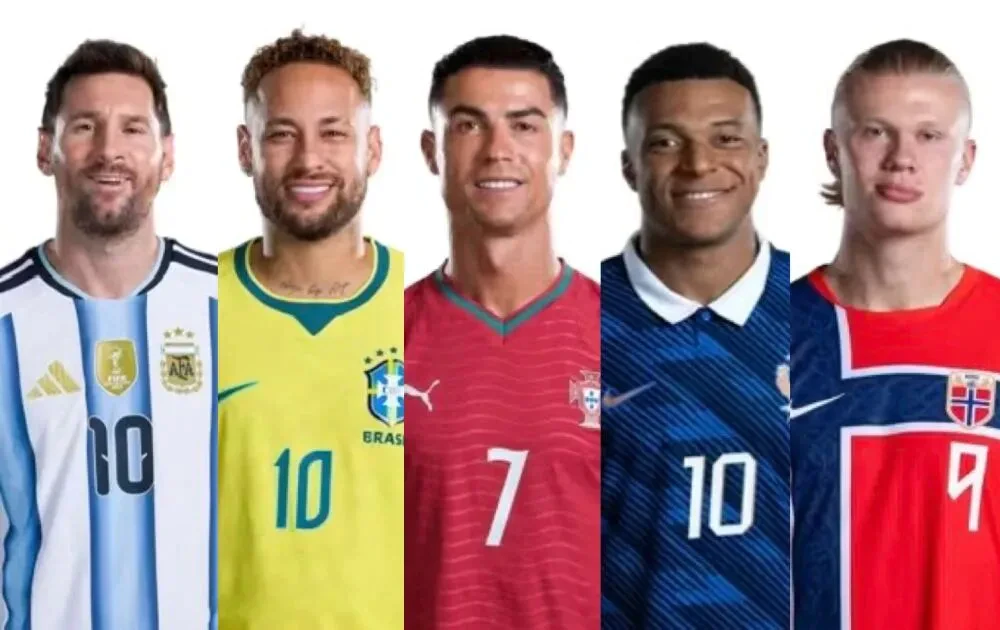
(From left to right: Lionel Messi, Neymar Jr., Cristiano Ronaldo, Kylian Mbappé, and Erling Haaland. Source: Xinhua News Agency)

Conclusion

The 2027 RSTP represents a fundamental structural overhaul of global football governance. By pairing substantive legal protections with a collaborative social dialogue platform, the new framework establishes a more balanced, legally compliant, and predictable cross-border transfer market.https://www.pinsentmasons.com/out-law/news/fifa-announces-new-player-transfer-regulations-following-diarra-settlement#:~:text=Revamped%20football%20transfer%20rules%20announced%20by%20FIFA,ruling%2C%20they%20did%20not%20go%20far%20enough.

Disclaimer & Copyright: This article is co-authored by lawyer Yu Yuting and Mandy Wu. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
The Guangzhou Bar Association officially announced the Decision on Guangzhou Bar Association 2025 Annual Member Awards.

Multiple attorneys from Guangdong NEO-ARK Law Firm received prestigious recognitions across several key categories—including the Theoretical Achievement Award, Social Stability Maintenance Award, Practice Excellence Award, Outstanding Working Committee Member, and Outstanding Special Committee Member—in recognition of their outstanding clinical legal practice, academic research, and contributions to bar organization development.

I. Theoretical Achievement Award

  • Analysis of Practical Dilemmas and Institutional Solutions for Cross-Border Visitation Rights of Minors Between Mainland China and Hong Kong/MacaoAuthors: Attorney Liu Minghong, Attorney Li Wanjun
  • Research on the Digital Estate Manager System in the Guangdong-Hong Kong-Macao Greater Bay AreaAuthor: Attorney Pan Wenjing
  • Legal Conflicts and Judicial Coordination of Cross-Border Wills Between Hong Kong and Mainland ChinaAuthors: Attorney Tang Jingying, Attorney Sun Kaiyang
  • Research on Criminal Jurisdiction Conflicts for Telecom Fraud in the Guangdong-Hong Kong-Macao Greater Bay AreaAuthor: Attorney Xie Guizhen

II. Social Stability Maintenance Award

  • Construction Engineering Contract Dispute CaseAwardees: Attorney Huang Jianqiu, Attorney Yu Yuting

III. Practice Excellence Award

  • Network Tort Liability Dispute CaseAwardee: Attorney Liu Xinyi
  • Medical Cooperation Contract Dispute CaseAwardees: Attorney Sun Jianhui, Attorney Ye Wenya

IV. Working Committee & Special Committee Honors

1. Outstanding Working Committee Member
  • Attorney Chen MeijuanInformatics and Legal Technology Promotion Working Committee
2. Outstanding Special Committee Members
  • Attorney Fang ZhilinDuty-Related Crimes Criminal Law Special Committee
  • Attorney Li WanjunMarriage and Family Law Special Committee

Conclusion

Every award reflects dedication, rigors of practice, and social responsibility. These recognitions highlight our attorneys' sustained commitment to frontline legal practice, cutting-edge theoretical research, bar organization governance, and social service.

NEO-ARK Law Firm remains committed to building practice excellence and social responsibility. The firm will continue encouraging its legal team to deepen expertise in complex legal fields, actively contribute to bar association initiatives, and advance high-quality legal services in the Guangdong-Hong Kong-Macao Greater Bay Area.

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
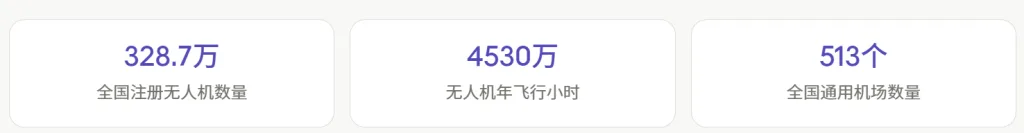
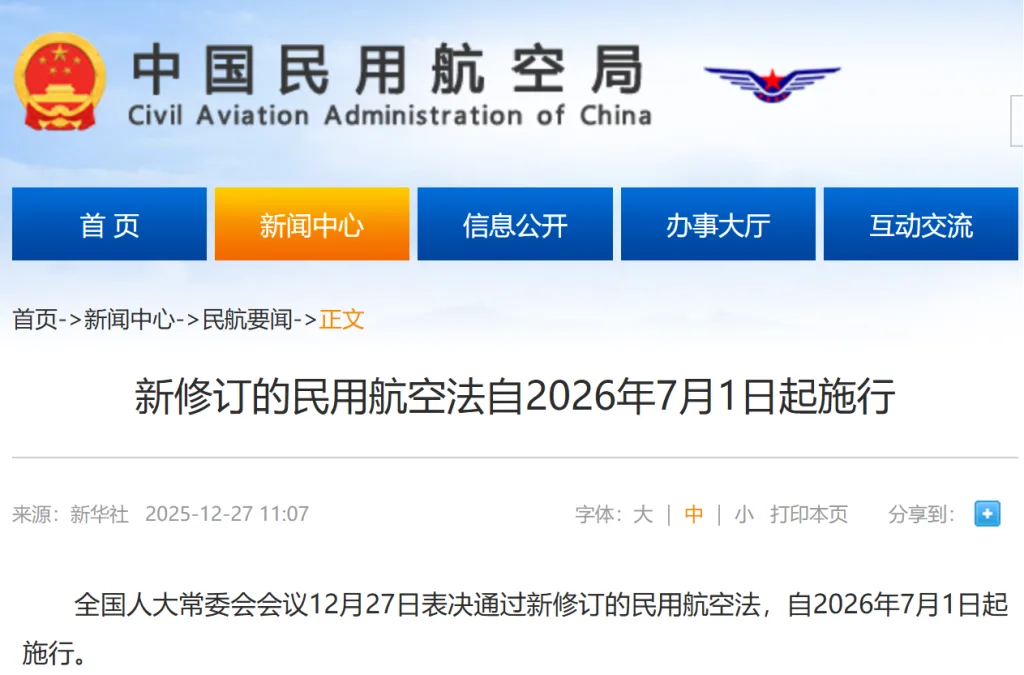
The newly amended Civil Aviation Law of the People's Republic of China officially takes effect today. As a comprehensive overhaul of the foundational legal statute that has governed China’s civil aviation sector for three decades, this legislative landmark transitions the low-altitude economy from fragmented regional trial programs into a unified, rule-of-law operational era.

(Source: Civil Aviation Administration of China)

Core Structural Shifts at a Glance:

  • Statutory Airspace Allocation: For the first time, low-altitude economy development is legally integrated into high-level airspace planning and local government infrastructure mandates.
  • Lifecycle Drone Identification: Mandatory airworthiness certifications and unique product identification codes (Product IDs) extend regulatory enforcement upstream to manufacturers.
  • Dynamic Enforcement & Countermeasures: Civil aviation authorities receive expanded enforcement powers, including site inspections, asset seizures, and mandatory anti-drone defense systems near sensitive zones.
  • Data Security & Privacy Safeguards: Explicit restrictions govern data collection, surveillance, and international data transfers during commercial drone operations.

I. Institutional Guarantee for Low-Altitude Airspace Allocation

Previously, low-altitude airspace opening and spatial planning relied primarily on local municipal rules or industry guidance, lacking direct grounding in national statute.

  • Core Statutory Provisions (Articles 74 & 225): The amended law explicitly mandates that airspace classification principles must incorporate the needs of low-altitude economic development. It adds a dedicated "Development Promotion" chapter, establishing legal duties for local governments at or above the county level to plan infrastructure and support industry growth.
  • Legal Impact: The law provides a solid legal foundation for government-led low-altitude infrastructure (such as physical vertiports, eVTOL landing pads, and integrated sensing-and-communication networks), accelerating municipal infrastructure investment and project rollouts.

II. Digital ID Enforcement: Full-Lifecycle Traceability for Unmanned Aircraft

To address public safety concerns surrounding commercial and consumer drones, the regulatory boundary extends directly upstream into aircraft design and manufacturing.

  • Core Statutory Provision (Article 34): Entities engaged in the design, production, import, maintenance, and flight operations of civil unmanned aircraft must obtain airworthiness approval, unless explicitly exempted by law. Furthermore, manufacturers are legally required to assign a standardized, unique product identification code to every aircraft.
  • Legal Impact: Commercial drones enter a fully transparent, lifecycle-monitored regulatory framework. Non-compliant manufacturers using uncertified components or failing safety standards will be phased out. In instances of unauthorized flights ("black flying") or property damage, regulatory agencies can achieve full-chain traceability from the aircraft straight to the registered operator.

(Source: Guangdong Digital Jurisprudence Society)

III. Enforcement Powers & Sensitive Zone Countermeasures

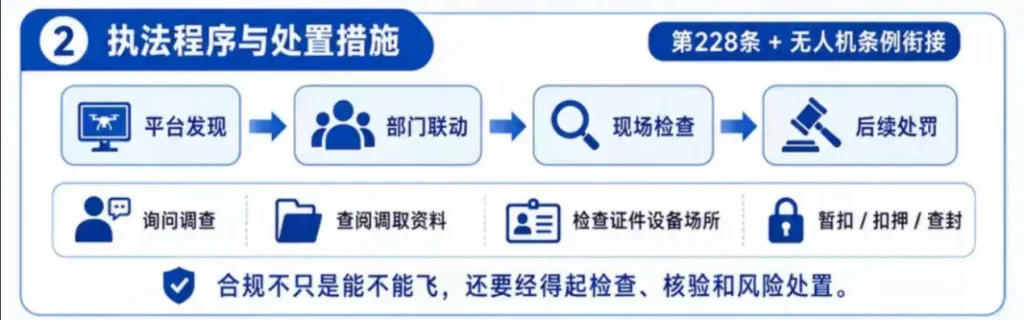
Recognizing the high volume and complex operational scenarios of low-altitude activities, the law equips civil aviation administrative authorities with enhanced enforcement mechanisms.

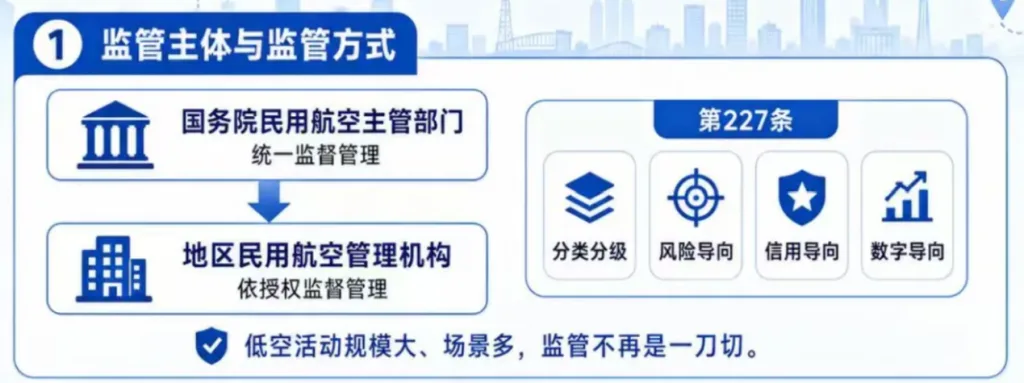
  • Core Statutory Provisions (Articles 61 & 228): Authorities are granted explicit powers for on-site inspections, data retrieval, asset impoundment, and temporary seizures. Additionally, civil airports are required to delineate designated drone control zones and equip them with detection and anti-drone countermeasure systems.
  • Legal Impact: Compliance for commercial low-altitude operators shifts from a one-time permit to continuous operational logging. Enterprises must maintain verifiable flight logs, real-time telemetry reporting, and audit trails to handle random dynamic inspections.

(source: Civil Aviation Administration of China)

IV. Urban Airspace Operational Restrictions

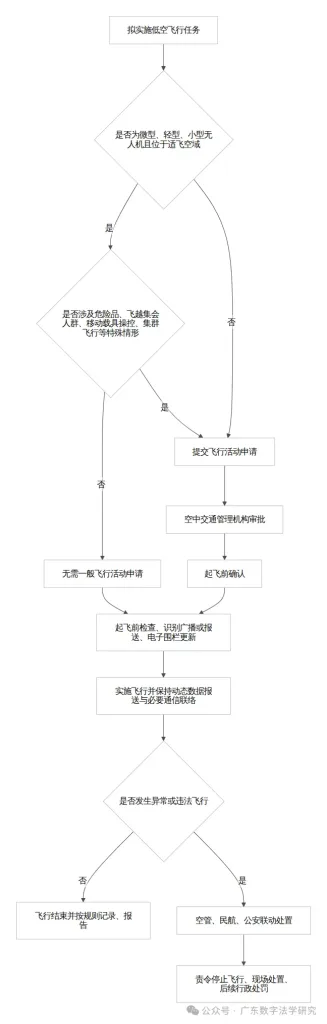
The law reinforces strict boundaries regarding flight paths over densely populated urban areas.

  • Core Statutory Provision (Article 83): Preserves the strict restriction that civil aircraft shall not fly over urban areas, unless strictly required for takeoff, landing, or designated flight corridors, maintaining altitudes sufficient to exit urban airspace in an emergency without endangering ground safety, or operating under special regulatory approval.
  • Legal Impact: Legislative encouragement of the low-altitude economy does not translate to unregulated urban flights. For enterprises planning urban air logistics or intercity eVTOL passenger transport, core competitiveness depends on maintaining superior safety standards, real-time airspace monitoring, and coordination with local air traffic control to secure special route permits.

(Source: Guangdong Digital Jurisprudence Society)

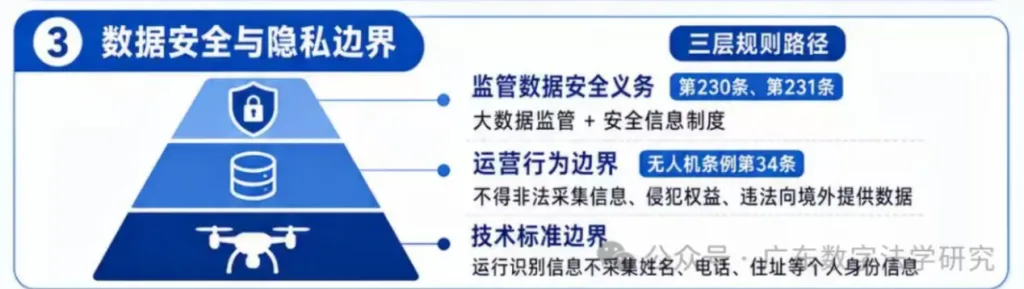
V. Data Privacy & Cross-Border Data Compliance

As aerial photography, infrastructure inspection, and geographic surveying become widespread, data privacy and national security controls have intensified.

  • Core Statutory Provisions (Articles 230 & 231): While encouraging the use of big data technologies for oversight, civil aviation authorities are legally bound to protect data security. In tandem with the Interim Regulations on the Flight Management of Unmanned Aircraft, the law strictly prohibits illegal data collection, infringement of individual privacy rights, and unauthorized cross-border data transfers.
  • Legal Impact: Enterprises utilizing drones for geographic mapping, industrial inspection, or high-definition surveying must implement strict data residency and access controls. Capturing sensitive geographic data or transferring flight telemetry abroad without security assessments triggers severe administrative and data privacy liabilities.

(Guangdong Digital Jurisprudence Society))

Conclusion

The implementation of the amended Civil Aviation Law reshapes legal predictability across the low-altitude sector, bringing an end to unregulated growth. Future market leaders will be those who seamlessly integrate airworthiness certification, data security protocols, and operational compliance into their core commercial architecture.

(Guangdong Digital Jurisprudence Society))

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
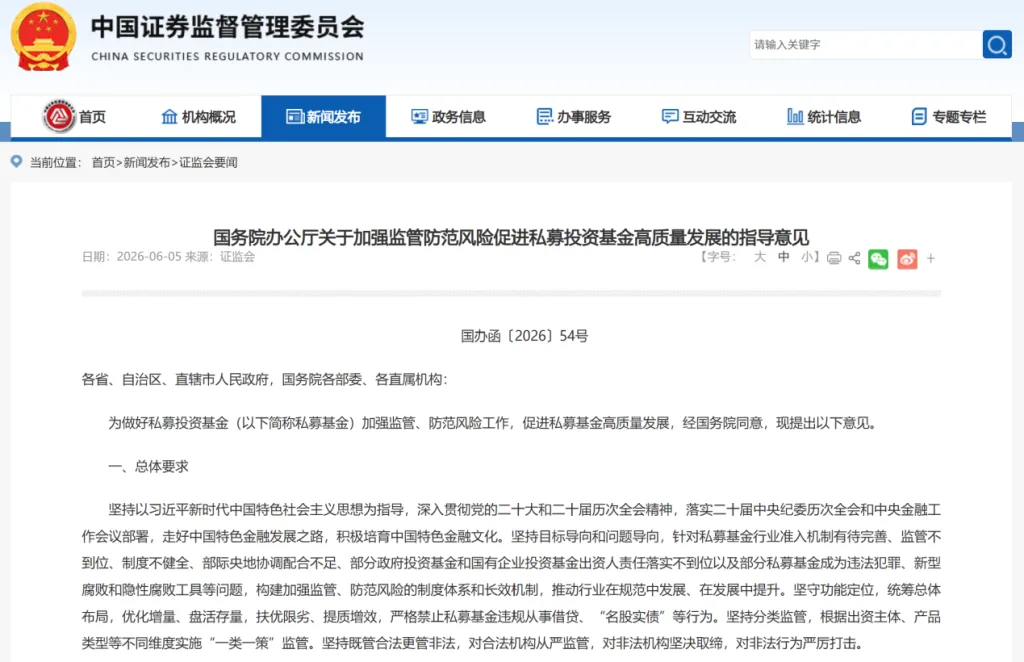
On June 5, 2026, the General Office of the State Council issued the Guiding Opinions on Strengthening Supervision, Preventing Risks, and Promoting High-Quality Development of Private Equity Investment Funds (State Council Letter [2026] No. 54, hereinafter referred to as "Decree 54").

As the top-level charter governing China's "1+N+X" private equity regulatory framework, Decree 54 marks the end of wild expansion and ushers in an era of stringent, high-quality institutional compliance.

Core Structural Shifts at a Glance:

  • Market Entry Control: Prequalification screening by provincial regulators is now a mandatory prerequisite prior to corporate registration.
  • Mandatory Custody: Mandatory fund custody rules expand significantly, systematically eliminating "self-custody" loopholes.
  • Valuation Adjustment Mechanism (VAM) Governance: Introduces the first-ever top-level regulatory restriction on VAM and Earn-out agreements, cracking down on disguised debt and rigid redemptions.
  • State Capital Scrutiny: Strictly bans county-level governments from establishing redundant new government funds, prohibiting state-owned enterprises (SOEs) from off-spectrum cross-industry investments.

(source:CCTV 13)

I. Regulatory Restructuring: Rebalancing Administrative Enforcement and Self-Regulation

Decree 54 establishes a dual-tier governance system that explicitly segregates administrative enforcement from industry self-regulation:

  • Legacy Model: Heavy reliance on Asset Management Association of China (AMAC) self-regulation, resulting in limited deterrence over unregistered entities.
  • Decree 54 Model: China Securities Regulatory Commission (CSRC) and its regional offices act as administrative gatekeepers for entry checks, investigations, and penalties, supported by AMAC for frontline daily monitoring, filings, and self-disciplinary reviews.

By placing administrative oversight at the forefront, compliance obligations transition from mere industry association rules to binding statutory duties. Continued compliance is now the absolute legal precondition for fund managers to operate in mainland China.

Attorney's Compliance Note:

Existing fund managers should establish a dual-line compliance protocol connecting both the CSRC and AMAC. Shift internal compliance priorities from formality-based initial filing reviews to full-lifecycle ongoing operational control. Fund managers should proactively build audit-response mechanisms for sudden regulatory inquiries and on-site inspections.

(Official release and regulatory bulletin on private equity oversight guidelines issued by the China Securities Regulatory Commission. Source: CSRC)

II. Gatekeeping at Market Entry: Mandatory Joint Prequalification Screening

Under Section II of Decree 54, any entity seeking to register as a private equity fund manager—or planning to include private equity or venture capital terminology in its corporate name or business scope—must complete a joint prequalification screening by the provincial financial regulatory authority and local CSRC office before applying for market regulation registration.

Registration Procedure Framework:

  1. Apply for Joint Prequalification Screening through the Provincial Authority and Local CSRC.
  2. Upon prequalification approval, proceed to Market Regulation Corporate Registration.
  3. Complete official AMAC Fund Manager Registration.
Entity TypeCorporate Name / Scope FeatureTrigger Prequalification?Required Registration Path
Licensed PE/VC ManagerContains "Private Equity", "VCF", etc.Yes (Mandatory)Prequalification Screening -> Corporate Registration -> AMAC Filing
Standard Investment FirmGeneral "Investment Management", "Asset Management"NoStandard Market Regulation Corporate Registration

Attorney's Compliance Note:

Prospective fund managers must factor in an additional 1 to 3 months for prequalification screening. Applications require complete transparency regarding ultimate beneficial owners (UBOs), actual controllers, capital contribution capabilities, and risk control systems.

III. Custody System Upgrade: Full-Coverage Mandatory Custody Execution

Decree 54 mandates the creation of unified, mandatory fund custody regulations across all PE structures. The regulatory threshold for custody exemptions has shrunk considerably:

  • Contractual Securities Funds: Mandatory custody applies across all structures.
  • Partnership & Corporate Securities Funds (Issued post-Aug 2024): Mandatory custody required without exception.
  • PE & VC Funds: Mandatory custody applies to all contractual structures, Special Purpose Vehicle (SPV) investments, and fund expansion products.

Attorney's Compliance Note:

Audit all active non-custodial funds within your portfolio immediately. Distinguish between legally exempted products and non-compliant structures requiring remediation. For newly established funds, embed qualified custodian institutions during the initial structural design phase to establish unambiguous cash-sweep and oversight covenants.

IV. Refining Equity Investments: Dual Regulation of VAM Agreements

For the first time, a State Council policy explicitly mandates the creation of specialized regulatory rules governing Valuation Adjustment Mechanisms (VAM / Earn-out agreements).

Going forward, VAM terms in PE/VC deals will be governed by two independent, parallel legal frameworks:

  1. Civil & Judicial Review: Governed by Supreme People's Court judicial guidelines evaluating corporate law feasibility and capital maintenance principles.
  2. Administrative Regulation (Decree 54): Strictly prohibiting VAMs structured to guarantee returns ("rigid redemption"), disguise debt as equity, or bypass leverage limits.

Attorney's Compliance Note:

Review all existing portfolio VAM provisions and classify them into strategic remediation categories:

  • Maintain: Commercial performance adjustments and legitimate shareholder-level compensation arrangements that comply with capital maintenance.
  • Amend or Excise: Unenforceable target-company buybacks, guaranteed return provisions, and rigid repurchase clauses that risk being recharacterized as illegal debt disguised as equity.

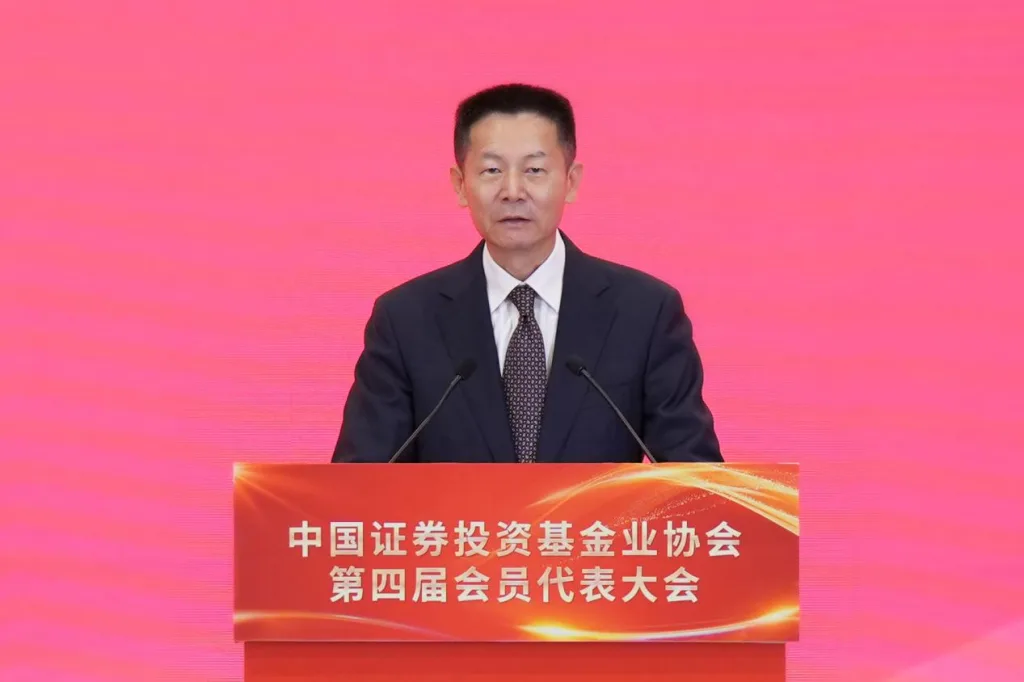
(CSRC Chairman Wu Qing delivering an opening address at the 4th Member Representative Congress of the Asset Management Association of China. Source: CSRC)

V. Tightening State-Owned and Government Fund Participation

Decree 54 imposes strict parameters on state-backed capital commitments:

  1. Government Investment Funds: County and district-level governments are principally prohibited from launching new government investment funds. Exceptions require approval from higher-level municipal or provincial governments. Functional overlaps across funds are eliminated, and disguised debt raising or guaranteed returns are strictly illegal.
  2. State-Owned Enterprise (SOE) Capital: SOE fund investments must align tightly with the enterprise's core operational mandate. SOEs are barred from cross-industry non-core investments, pure conduit operations, and non-compliant real estate funding.

Attorney's Compliance Note:

Shift fundraising priorities toward established provincial and municipal guidance funds. When partnering with SOE capital, conduct formal core business alignment reviews beforehand to ensure all transaction documents are stripped of guaranteed return terms.

VI. Closed-Loop Risk Cleanup & Digital Supervision

Decree 54 institutes a centralized digital monitoring platform that aggregates data across corporate registries, fund filings, bank custody, and judicial records to enable full-scope look-through enforcement:

  • Fund Manager Phase-Out: Entities involved in major illegalities will have their registrations revoked directly. Dormant ("shell"), abnormal, or untraceable managers will face strict time-bound rectification or cancellation.
  • Commercial Entity Phase-Out: Entities holding private equity designations in their business scope without actual operational capacity will have their business licenses revoked by market regulation authorities.

Conclusion & Strategic Action Plan

With the release of Decree 54, detailed departmental rules addressing information disclosure, fundraising, custody, VAM terms, and state capital will be rolled out rapidly. Compliance is no longer an operational cost—it is the foundational license to operate. Fund managers and institutional investors should immediately initiate comprehensive internal compliance audits to navigate this regulatory transition safely.

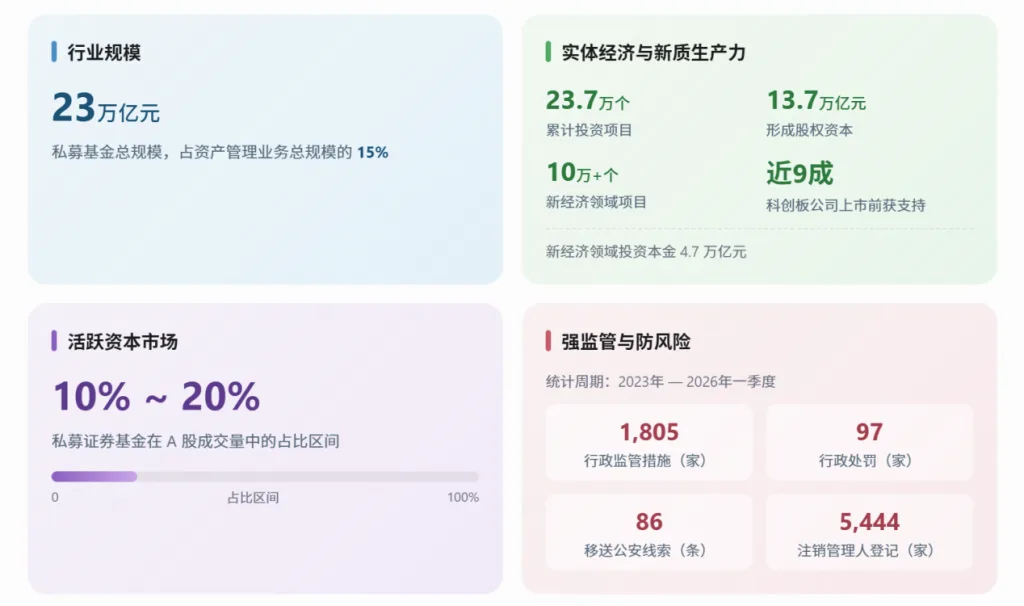
(Official data presentation from the State Council press conference detailing the implementation metrics and timeline for Decree No. 54. Source: CSRC Press Briefing)

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
Overview

A foreign-related inheritance dispute arose after the death of an individual who left no will or testamentary arrangement.

The deceased had three daughters as first-order statutory heirs. One daughter initiated inheritance proceedings, claiming a one-third share of the assets.

Representing the other two heirs, Yu Yuting of NEO-ARK Law Firm challenged the scope of the claimed estate, arguing that certain amounts included by the claimant were not inheritance assets but instead involved compensation payments, funeral expenses, or funds held by third parties.

The court ultimately confirmed the actual estate subject to inheritance division and adopted the legal position that non-estate assets and disputed third-party funds should not be included in the inheritance distribution.

Case Snapshot

ItemDetails
Practice AreaForeign-Related Inheritance Law
Case TypeEstate Distribution Dispute
ClientTwo Legal Heirs
JurisdictionChina
Core IssueDefinition of Estate Assets
Key IssueWhether Compensation Payments and Third-Party Held Funds Form Part of the Estate
Lead LawyerYu Yuting / Li Wanjun
Law FirmNEO-ARK Law Firm

Client's Situation

The dispute developed as follows:

1. Death Without a Will

The deceased passed away without leaving a will or inheritance agreement.

Under Chinese statutory inheritance rules, the deceased's three daughters were first-order legal heirs.


2. Inheritance Claim

One daughter filed a lawsuit requesting division of the deceased's assets and claimed a one-third inheritance share.


3. Dispute Over Estate Scope

The defendants, represented by NEO-ARK Law Firm, disagreed with the claimed estate amount.

They argued that certain claimed assets included:

  • Death-related compensation payments;
  • Funeral expenses;
  • Funds withdrawn or held by a third party;
  • Assets involving separate ownership disputes.

4. Legal Representation

The legal team focused on identifying which assets legally qualified as inheritance property and which should be excluded from estate distribution.


Legal Strategy

StrategyPurpose
Investigate the deceased's financial assetsIdentify the actual estate available for inheritance
Distinguish estate and non-estate assetsPrevent improper inclusion of compensation payments and other funds
Challenge third-party held fundsClarify that separate ownership disputes should not be decided within inheritance proceedings
Present legal analysis before the courtProtect the legitimate inheritance interests of the clients

Key Legal Issues

1. Are Compensation Payments and Funeral Expenses Part of the Estate?

The legal team argued that certain payments issued after death were not the deceased's personal property.

Death-related compensation and funeral expenses are generally intended to provide financial support and assistance to close relatives rather than constitute assets owned by the deceased at the time of death.

Therefore, such payments should not automatically be included in inheritance distribution.


2. Should Third-Party Held Funds Be Divided in an Inheritance Case?

Certain funds had been withdrawn or held by a third party after the deceased's death.

The legal team argued that these funds involved separate ownership issues and should not be directly handled through inheritance proceedings without independent determination of ownership.

Outcome

After reviewing the evidence and legal arguments, the court determined that:

  • Bank deposits of approximately RMB 2.3 million and AUD 1,000 constituted inheritance assets;
  • The three daughters were each entitled to one-third of the confirmed estate;
  • The claimant's other requests were dismissed.

The court accepted the legal position presented by NEO-ARK Law Firm regarding the distinction between inheritance assets and non-estate property.


Why This Case Matters

Inheritance disputes often involve more than simply dividing assets.

The most important question is usually:

What assets legally belong to the estate?

This case demonstrates that accurate classification of assets is essential in inheritance proceedings.

Compensation payments, funeral-related funds, and assets controlled by third parties may have different legal characteristics from ordinary personal property and should not automatically be included in inheritance distribution.

For overseas Chinese families and individuals with assets in China, professional legal analysis is particularly important where inheritance involves multiple jurisdictions, family members, or unclear asset ownership.


Frequently Asked Questions

Are all assets received after someone's death considered inheritance?

No.

Only assets legally owned by the deceased at the time of death generally form part of the estate. Certain compensation payments or benefits may have different legal purposes and may not be inheritance property.


Are funeral expenses and death compensation divided among heirs?

Not necessarily.

Their legal nature must be examined separately. Some payments are intended for specific purposes or specific beneficiaries rather than estate distribution.


Can disputed funds held by another person be handled in an inheritance lawsuit?

It depends on the nature and ownership of the funds.

Where ownership itself is disputed, the court may require separate legal proceedings rather than deciding the issue directly within inheritance distribution.


Key Takeaways

  • The first step in an inheritance dispute is identifying the true estate.
  • Not all post-death payments are inheritance assets.
  • Third-party held funds may require separate ownership analysis.
  • Proper asset investigation can significantly affect inheritance outcomes.
  • Professional legal advice is essential in complex or foreign-related inheritance matters.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.

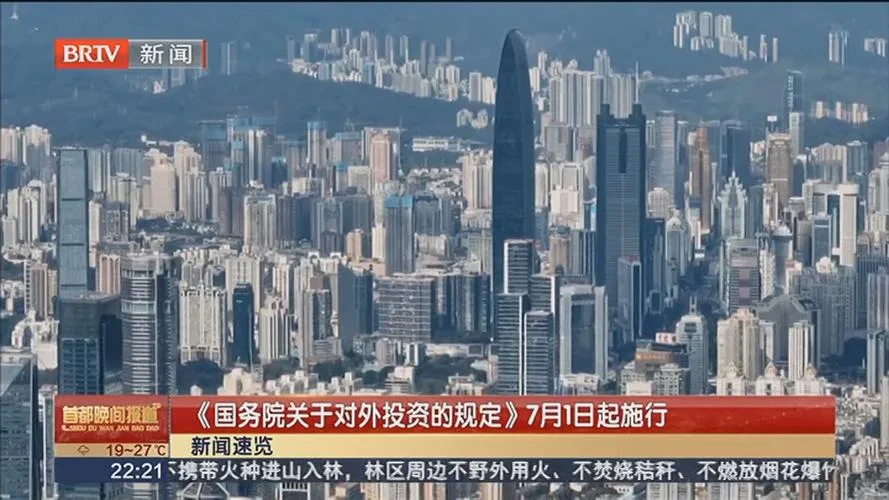
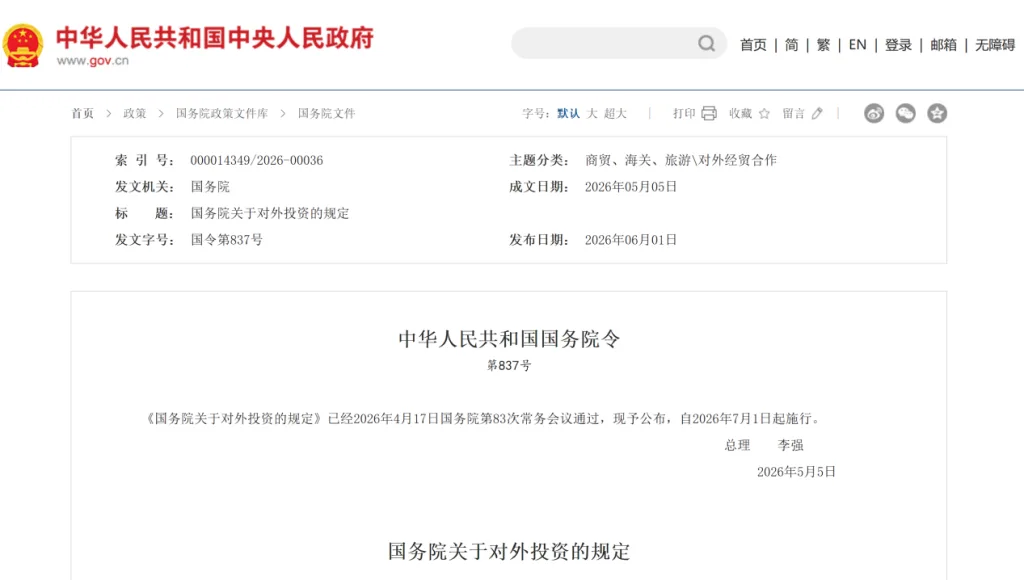
On June 1, 2026, the State Council officially promulgated the Regulations on Outbound Investment (State Council Decree No. 837, hereinafter referred to as the "Regulations"), which will take effect on July 1, 2026.

(A view of the State Council administrative updates. Source: Beijing Web TV)

As the first systematic administrative regulation enacted by the State Council in the field of outbound direct investment (ODI), this landmark regulation consolidates previously scattered departmental rules from the National Development and Reform Commission (NDRC), the Ministry of Commerce (MOFCOM), and other authorities. It establishes a comprehensive framework covering outbound investment services, administration, and protection, marking a milestone in the development of China’s outbound investment regime.

Previously, outbound investments were governed by NDRC's "Decree No. 11" and various foreign exchange regulations under the State Administration of Foreign Exchange (SAFE). How does this new framework differ? This article analyzes the core shifts, compliance priorities, and practical impact on cross-border business based on the official text and practical experience.

(The official release portal of the Central People's Government of the People's Republic of China. Source: gov.cn)

I. Regulatory Shifts: 6 Key Upgrades Under the New Framework

1. Individual Investors Officially Regulated

Individual investors who hold overseas assets through Special Purpose Vehicles (SPVs) or nominee holding structures (trust arrangements) are now officially brought under unified regulatory supervision.

Attorney’s Note: While detailed implementation guidelines are pending, individuals holding overseas assets should closely monitor regulatory updates and evaluate whether their existing offshore holding structures require compliance adjustments.

2. Dual Oversight Expands to Quadruple Supervision

The old approval process primarily focused on NDRC and MOFCOM filings. The new framework introduces a comprehensive four-pronged oversight mechanism:

  1. Macro-Advisory Filings & Approvals (NDRC & MOFCOM)
  2. Cross-Border Capital Checks (Foreign Exchange/SAFE & Commercial Banks)
  3. National Security Reviews (Multilateral security screening on strategic assets)
  4. Information Reporting & Joint Disclosures (Post-investment compliance monitoring)

Attorney’s Note: The National Security Review is an independent screening procedure. It does not rely on, nor is it bypassed by, standard NDRC or MOFCOM filings. Involved entities and individuals are legally obligated to cooperate and must not block or reject official inquiries.

3. Clear Boundaries for Export Control and Data Compliance

For the first time, outbound investment regulations explicitly mandate export control compliance.

Attorney’s Note: Enterprises deploying staff abroad, sharing proprietary technology, or engaging in transnational training must conduct dual-compliance reviews under the Export Control Law and the Regulations on Export Control of Dual-Use Items. While the "Sensitive Industry Directory" awaits updates, emerging sectors like AI infrastructure, quantum computing, 6G communications, biometrics, and strategic minerals are heavily scrutinized in practice. Projects in these areas require comprehensive risk assessments regardless of transaction size.

4. Strict Penalties for Unapproved Outbound Investments

The regulatory cost of non-compliance has escalated dramatically.

Practical Example: For an outbound investment of RMB 100 million, failure to complete timely filing procedures can lead to a confiscation of illegal gains and administrative fines ranging from RMB 100,000 to RMB 500,000. For severe violations, the fine ceiling reaches RMB 1 million, accompanied by a ban on processing new applications or participating in outbound investments for 1 to 3 years.

5. Personal Accountability: The Dual-Punishment System

Corporate violations now carry personal consequences. Regulatory penalties will target both the corporate entity and the responsible decision-makers.

Attorney’s Note: Signing directors, Chief Financial Officers (CFOs), and General Counsels can face direct personal administrative liability if an enterprise violates these regulations. Executives must proactively verify outbound compliance before authorizing transactions.

6. Crackdown on Fraudulent Filings and Illegal Activities

The Regulations strictly prohibit using fraudulent documentation to obtain approvals, or using outbound investments to facilitate illegal capital flight, tax evasion, or money laundering.

Attorney’s Note: If an outbound project is found to be a sham structured to move domestic capital offshore, the ODI Certificate will be revoked, exposing the parties to civil, tax, and criminal liabilities. The cross-departmental coordination between this regulation, anti-money laundering (AML) frameworks, and the Common Reporting Standard (CRS) should be carefully monitored.

(Outbound investment and trade developments driving global industrial growth and bilateral partnerships. Source: Xinhua News Agency)

II. High-Risk Areas and Most Affected Business Categories

1. High-Priority Corporate Categories
  • Existing Outbound Enterprises: Companies with existing offshore entities, active overseas operations, or foreign equity investments.
  • Prospective Outbound Enterprises: Businesses planning offshore acquisitions, capital increases, or establishing new foreign entities in the second half of 2026.
  • Sensitive Sector Enterprises: Entities operating in high-risk jurisdictions, cross-border finance, advanced technology, or strategic natural resources.
2. High-Risk Business Activities
  • Retroactive Filings ("Invest First, File Later"): Formerly a common workaround, this practice is now prohibited and subject to immediate administrative penalties.
  • Non-Core Large-Scale Investments: Transnational financial investments or cross-industry acquisitions unrelated to the company's core business will face strict scrutiny.
  • Incomplete Portfolios for Existing Projects: Active overseas projects with missing corporate records, outdated financials, or incomplete risk reporting.
  • Investments in Sensitive Regions/Industries: Proposed projects in high-risk jurisdictions or restricted sectors will experience lower approval rates and prolonged review cycles.
3. Common Compliance Pitfalls
  • Individual Offshore Holdings: Founders holding overseas assets through offshore SPVs or proxy structures risk triggering compliance audits.
  • High-Tech Enterprises: Cross-border research centers, technology licensing, and global data transfers are subject to overlapping export control and data security reviews.
  • Unreported Tier-2 Reinvestments: Making down-stream investments via existing offshore subsidiaries without completing corresponding filing procedures can lead to retroactive penalties.
  • Cross-Border Litigation Data Risks: Transferring internal corporate data or documents abroad for foreign litigation or arbitration without verifying data residency can violate domestic confidentiality laws.

III. The Essential Outbound Compliance Checklist

1. Action Items for Enterprises
  1. Structure Audit: Map out all existing offshore investment structures (including indirect holdings through SPVs or VIE structures) to ensure all projects are fully registered and approved.
  2. Export & Data Audit: Review international business operations for controlled technologies or sensitive data transfers, and evaluate compliance with current export control regulations.
  3. Directory Tracking: Monitor upcoming releases of the "Encouraged, Restricted, and Prohibited Outbound Investment Directory" by the NDRC and MOFCOM to evaluate project feasibility.
  4. Internal Controls: Upgrade corporate governance policies, establish clear authorization limits for outbound investments, and define liability lines to safeguard executives.
2. Action Items for Individual Investors
  1. Asset Structuring: Assess current personal holdings of foreign equity, real estate, and financial portfolios to evaluate whether supplementary disclosures or structural modifications are necessary.
  2. Offshore SPV Reviews: Closely track the forthcoming implementation details concerning individual ownership of overseas assets through SPVs.
  3. Immigration and Real Estate Planning: Re-align cross-border wealth management, immigration setups, and global property acquisitions with the new compliance standards.

IV. Crucial Provisions for Outbound Enterprises

  • Applicability to Hong Kong, Macao, and Taiwan: Investments in Hong Kong, Macao, and Taiwan are managed with reference to these Regulations. This explicitly includes structures established for Hong Kong IPOs or holding platforms set up in Hong Kong.
  • Indirect Outbound Investment Cover: The Regulations cover "indirectly acquiring ownership or control of enterprises or assets in other countries or regions." Investments routed through multi-layered overseas subsidiaries remain subject to domestic regulation.
  • Financing and Guarantees Classified as ODI: Providing financial assistance or guarantees to offshore entities is officially categorized as outbound investment. Issuing shareholder loans or corporate guarantees to overseas affiliates without proper regulatory filings constitutes a compliance violation.
  • Diplomatic and Consular Protection: Article 20 outlines the consular protection responsibilities of overseas diplomatic missions, and Article 23 establishes a mechanism to counter foreign investment barriers, offering compliant enterprises a reliable legal shield abroad.

Conclusion

A robust rule-of-law framework is the foundation of a healthy business environment. High-standard administrative regulations impose strict compliance duties, but they also provide a safer, more predictable landscape for outbound businesses. If you are advancing an overseas investment or planning global expansion, we recommend using the pre-implementation transition window to audit your processes, mitigate compliance risks, and secure long-term operational stability.

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
Overview

This case arose from the international transportation of commercial lighting products from China to Amazon Fulfilment by Amazon (FBA) warehouses in the United States.

During the COVID-19 pandemic, Amazon warehouses no longer issued traditional signed or stamped Proof of Delivery (POD) documents. Relying on the absence of a signed POD, the customer refused to pay the outstanding freight charges and filed a counterclaim alleging that the goods had never been delivered.

Representing the carrier, Yu Yuting, Attorney at NEO-ARK Law Firm, reconstructed the overseas delivery process using electronic logistics records, overseas delivery documents, and official Amazon communications. The court accepted the evidence, confirmed that the carrier had fully performed its contractual obligations, and upheld the client's claim in full.

Case Snapshot

ItemDetails
Practice AreaInternational Trade & Logistics Disputes
Case TypeMultimodal Transport Contract Dispute
Cross-Border ElementChina – United States
ClientInternational Freight Carrier
DestinationAmazon Fulfilment by Amazon (FBA) Warehouses, United States
Core Legal IssueRecovery of Freight Charges Without a Signed Proof of Delivery (POD)
Lead LawyerYu Yuting / Li Qikang
Law FirmNEO-ARK Law Firm

Client's Situation

The dispute developed through the following stages.

1. Cross-Border Transportation

The client arranged multimodal transportation of commercial lighting products from China to multiple Amazon FBA warehouses in the United States.


2. Operational Changes During the Pandemic

During the COVID-19 pandemic, Amazon adjusted its warehouse receiving procedures and no longer provided traditional signed or stamped POD documents for many deliveries.


3. Payment Dispute

The customer argued that, without a signed POD, the carrier could not prove delivery and therefore refused to pay the outstanding freight charges.

The customer also filed a counterclaim seeking compensation.


4. Legal Representation

The client instructed NEO-ARK Law Firm to recover the unpaid freight charges and defend against the counterclaim.


Legal Strategy

StrategyPurpose
Reconstruct the delivery processDemonstrate that the goods reached the designated Amazon FBA warehouses
Collect overseas delivery evidenceReplace the missing signed POD with a complete evidence chain
Verify Amazon's operational practicesExplain why signed PODs were unavailable during the pandemic
Defend against the counterclaimRefute allegations of non-delivery and contractual breach


Outcome

The court found that the carrier had successfully completed delivery despite the absence of a traditional signed POD.

Based on the evidence presented, the court:

  • Ordered payment of all outstanding freight charges;
  • Awarded interest calculated at four times the applicable Loan Prime Rate (LPR);
  • Rejected the customer's counterclaim in full;
  • Ordered the customer to bear the preservation costs and all litigation expenses.

Why This Case Matters

Cross-border logistics between China and the United States increasingly depends on digital records rather than traditional paper documentation.

This case demonstrates that the absence of a signed Proof of Delivery (POD) does not automatically prevent a carrier from proving successful delivery. When electronic logistics records, overseas delivery documents, platform communications, and tracking information form a complete and reliable evidence chain, they may be sufficient to establish contractual performance before a Chinese court.

For freight forwarders, logistics companies, exporters, and cross-border e-commerce businesses, preserving digital evidence is now just as important as transporting the goods themselves.


Frequently Asked Questions

Is a signed POD always required to recover freight charges?

No.

A signed POD is important evidence, but it is not the only way to prove delivery. Courts may accept other reliable evidence that establishes the goods reached the agreed destination.


Does Amazon FBA always provide a signed POD?

Not necessarily.

During the COVID-19 pandemic, many Amazon FBA warehouses relied on electronic receiving procedures rather than issuing traditional signed or stamped delivery receipts.


Can electronic logistics records be used as evidence?

Yes.

Electronic PODs, logistics tracking records, shipping documents, emails, and platform communications may all be used to establish successful delivery when considered together.


Key Takeaways

  • A missing signed POD does not automatically prevent recovery of freight charges.
  • Electronic logistics records can be strong evidence of contractual performance.
  • A complete evidence chain is often more persuasive than a single document.
  • Early legal advice helps reduce risks in international logistics disputes.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.

Overview

A South Korean company established a wholly owned subsidiary in Xi'an, China, to operate in the semiconductor industry.

Although the subsidiary appeared to satisfy the substantive requirements for China's preferential tax policies applicable to qualifying semiconductor enterprises, it failed to complete the required annual filing procedures and was not included on the official list of eligible enterprises for the following tax year.

The company engaged Yu Yuting, Attorney at NEO-ARK Law Firm, to assess the legal consequences of the missed filing, evaluate possible remedial measures under Chinese law, and develop a cross-border tax strategy designed to minimise the group's overall global tax burden.

Case Snapshot

ItemDetails
Practice AreaCross-Border Tax Advisory
Case TypeTax Incentive Compliance
Cross-Border ElementSouth Korea – China
ClientSouth Korean Company
IndustrySemiconductor (Integrated Circuit)
Core Legal IssueLoss of Tax Incentives Due to Missed Compliance Filing
Lead LawyerYu Yuting / Li Chengwan
Law FirmNEO-ARK Law Firm

Client's Situation

The matter developed through the following stages.

1. Investment in China

The client established a wholly owned subsidiary in Xi'an, China, to conduct business in the semiconductor industry.


2. Qualification for Preferential Tax Policies

Based on the applicable national policies, the subsidiary appeared to meet the substantive requirements for preferential tax treatment available to qualifying enterprises.


3. Missed Annual Compliance Filing

The company did not complete the required annual filing procedures or apply for inclusion on the official list of eligible enterprises within the prescribed deadline.


4. Loss of Preferential Tax Treatment

As a result, the subsidiary was unable to enjoy the relevant tax incentives for the following tax year.


5. Cross-Border Tax Advisory

The client sought legal advice on available administrative options in China and on cross-border tax planning aimed at reducing its worldwide tax exposure.


Legal Strategy

StrategyPurpose
Review China's tax incentive policiesAssess whether the company met the substantive eligibility requirements
Analyse compliance obligationsIdentify the legal impact of the missed filing
Review applicable international tax treatiesEvaluate available cross-border tax planning opportunities
Coordinate with overseas tax advisersDevelop an integrated global tax strategy
Assess available administrative remediesDetermine practical options under Chinese law


Outcome

Following the legal review, the client obtained a comprehensive assessment of its legal position and the available options under Chinese law.

The advisory work provided practical guidance on potential administrative remedies, cross-border tax treaty considerations, and coordinated international tax planning, enabling the client to evaluate the most commercially appropriate strategy for reducing its overall global tax burden.


Why This Case Matters

Many foreign-invested enterprises assume that qualifying for China's tax incentives is sufficient to secure preferential tax treatment.

In practice, continued eligibility often depends on ongoing compliance with administrative filing requirements and government procedures.

This case demonstrates that tax compliance involves more than meeting the substantive legal criteria. For multinational businesses operating in China, timely legal review and coordinated international tax planning can play an important role in preserving tax benefits and managing global tax exposure.


Frequently Asked Questions

Can South Korean companies qualify for China's tax incentives?

Yes.

Foreign-invested enterprises, including South Korean companies, may qualify for various preferential tax policies in China if they satisfy the relevant legal and regulatory requirements.


What happens if a company misses a required tax incentive filing?

The consequences depend on the applicable regulations and administrative practice. In some situations, supplementary procedures or other remedial measures may be available, but prompt legal and tax advice is essential.


Why should multinational companies consider international tax treaties?

Cross-border tax treaties and foreign tax credit mechanisms may affect the group's overall tax position. Coordinating Chinese tax compliance with international tax planning can help reduce worldwide tax exposure.


Key Takeaways

  • Tax incentives require both substantive eligibility and procedural compliance.
  • Missing an administrative filing deadline may affect access to preferential tax treatment.
  • Cross-border tax planning should combine Chinese law with international tax considerations.
  • Early legal advice may help identify available options and reduce global tax risk.

About the Author

Yu Yuting
Partner | NEO-ARK Law Firm

Lawyer Yu focuses on foreign-related litigation, cross-border disputes, commercial matters, and legal services for overseas individuals and businesses in China.

Email: [email protected]

About NEO-ARK Law Firm

NEO-ARK Law Firm provides legal services in foreign-related litigation, commercial disputes, family law, and cross-border legal matters, assisting both international and domestic clients throughout China.

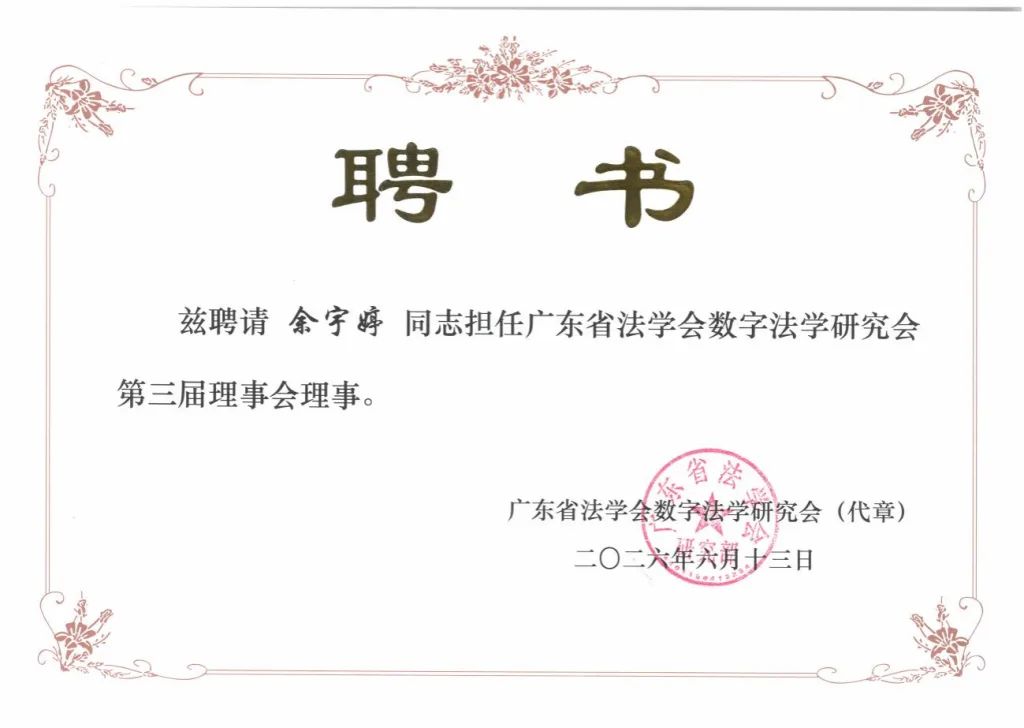
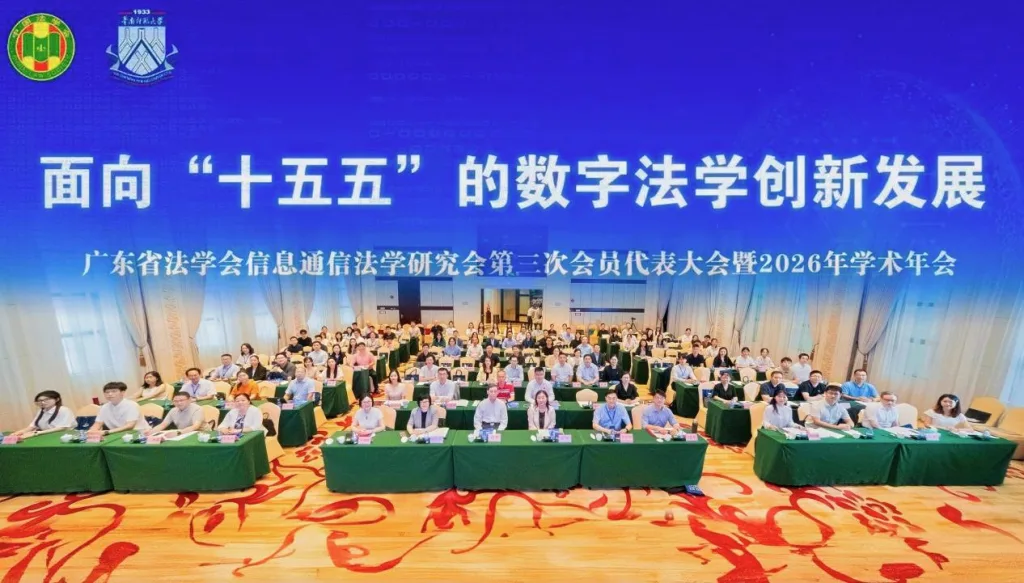
On June 13, 2026, the Guangdong Digital Jurisprudence Society successfully completed its leadership transition and election process.

Leveraging her deep professional expertise in data compliance and digital law alongside her exceptional clinical legal practice, Attorney Yu Yuting of our firm has been officially reappointed as a Council Director to the 3rd Council of the Guangdong Digital Jurisprudence Society.

I. Embracing the Digital Era: Advancing Frontier Compliance

As the global digital economy continues to expand, frontier legal issues such as data security, cross-border data flows, and artificial intelligence regulations are becoming increasingly critical.

The Guangdong Digital Jurisprudence Society serves as the province's premier platform for theoretical digital law research and practical innovation, bringing together top-tier academic experts, scholars, and leading legal practitioners from across China.

II. Translating Digital Legal Theory into Business Solutions

Since her initial appointment as Council Director, Attorney Yu Yuting has consistently worked at the intersection of digital legal research and practical client services.

During her tenure, she has remained at the forefront of digital transformation:

  • Actively participating in high-level academic symposiums.
  • Conducting in-depth research on corporate digital governance.
  • Pioneering practical legal strategies for cross-border data compliance and the financial assetization of intellectual property.
  • Devoting her practice to translating academic theories into practical, risk-mitigating compliance solutions for enterprise clients.

III. Looking to the Future of Digital Law

This reappointment represents both a prestigious professional recognition and a renewed commitment to the field.

Attorney Yu Yuting stated that she will continue to bridge the gap between academic theory and practical legal application. Leveraging NEO-ARK Law Firm's integrated platform, she plans to focus on the localization and system innovation of digital law, contributing her expertise to the growth of the Society and the advancement of digital rule-of-law initiatives in Guangdong.

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
I. Rules for Asset Division and Cross-Border Debt Under Chinese Jurisdiction

1. Jurisdiction and Practical Limits on Overseas Property Division

When handling international asset division, if a Chinese court applies Chinese law to resolve marital property disputes, it holds broad adjudicative authority. However, there are strict limits regarding what can realistically be enforced abroad due to conflict of laws, burden of proof, and sovereignty:

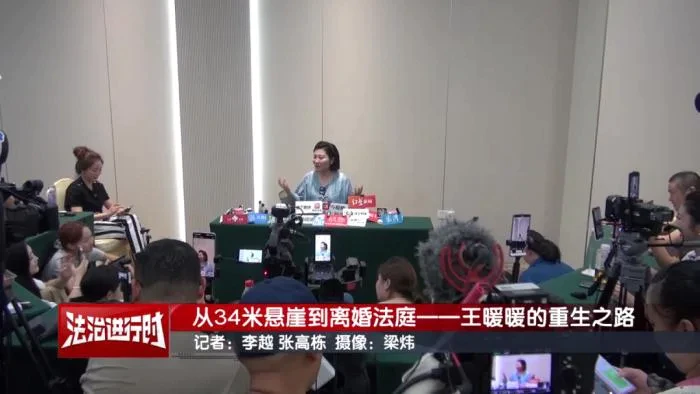
(Following multiple rounds of cross-border coordination, the defendant Yu Xiaodong appeared via video link from a Thai prison, and the Chinese court granted the divorce in the first-instance trial. Source: Chinanews.com)

  • Moveable vs. Immoveable Assets: For overseas moveable property (e.g., bank deposits, financial portfolios, corporate equity, vehicles), Chinese courts can directly adjudicate the split, ownership, or cash compensation—provided the parties supply sufficient evidence or reach a mutual agreement in court. Conversely, under Article 36 of the Law on the Application of Laws to Foreign-Related Civil Relations, real estate is governed by the lex situs (law of the place where the property is located). Consequently, mainstream Chinese judicial practice avoids directly splitting ownership of overseas real estate. Courts generally decline to adjust or process the physical title of foreign real property, choosing instead to determine equity shares, award cash compensation, or divide actual proceeds from a sale. If the status and valuation of the asset cannot be verified, courts typically decline to make a ruling.
  • Burden of Proof: Chinese courts do not have cross-border investigative powers. The existence, ownership, acquisition date, and market value of all overseas assets must be proved entirely by the parties themselves. Any document generated abroad (e.g., property deeds, bank statements, investment receipts) must be officially notarized locally, authenticated by the competent Chinese embassy or consulate, and accompanied by certified Chinese translations to be admissible.
  • Enforcement Constraints: A domestic court order dividing overseas assets is legally effective only within China. It cannot be directly executed by foreign authorities. Enforcement depends on bilateral treaties or mutual reciprocity with the destination state, which often involves procedural hurdles. If the destination state does not recognize the Chinese decree, parties must file a separate property division lawsuit in that local jurisdiction.

Key Takeaway on Property: Moveable property is dividable if verifiable or agreed upon; overseas real estate is subject to the principle of "no direct title division, compensation only". Strategically, you should resolve domestic assets first within the main divorce proceeding, handle overseas real property through offset compensations, and reserve unresolved foreign assets for separate local actions.

(The husband lost contact after going to the United States for work 8 years ago. The wife filed for divorce, and the court successfully resolved the case through online mediation via the smart court system. Source: China Peace Grid)

2. Strategic Management of Cross-Border Debt Risks
  • The Marital Status Loophole: An overseas divorce decree that has not been formally recognized by a Chinese court holds no legal effect inside mainland China. Legally, the parties remain married domestically. Consequently, newly acquired loans, mortgages, or credit liabilities may still be deemed community debt if they meet joint-liability standards.
  • Joint Debt Standards: Under Article 1064 of the Civil Code, joint marital debt requires joint signature, subsequent ratification, or proof that the funds were used for daily family needs. Unilateral, large-scale borrowing not used for family life or joint business remains personal debt.
  • Risk Warning: Do not take on substantial loans or act as a joint guarantor before an overseas divorce is officially recognized in China. Doing so risks exposing you to unexpected joint liability.

II. Recognition and Enforcement of Chinese Divorce Decrees Abroad

Once a Chinese court issues a divorce judgment or mediation decree, using it abroad (to divide foreign assets or to remarry) requires navigating the foreign jurisdiction's recognition and enforcement procedures.

The difficulty varies significantly by country. Monetary divisions (e.g., splitting savings or compensation) are widely recognized in jurisdictions like Canada, Australia, and Singapore. However, custody and visitation provisions often require a local de novo trial, as foreign courts exercise extreme caution regarding child welfare.

Core Principle: Recognition ≠ Enforcement

  • Recognition: The local foreign court formally acknowledges the legal status of the Chinese judgment (specifically, the fact that the marriage is dissolved).
  • Enforcement: The local court uses compulsory state measures (e.g., seizing bank accounts or real property) to execute the specific terms of the judgment.

III. Application Process for Foreign Recognition

Step 1: Document Preparation
  • The original Chinese divorce judgment or mediation decree.
  • An official certificate of effective judgment (proving the decree is final and binding).
  • An official translation of the documents into the official language of the executing country.
  • A formal application/petition for enforcement.
Step 2: Petition the Competent Foreign Court

File the petition with the local court where the assets or children are located. The foreign court will review the Chinese decree to ensure it does not violate local public policy or fundamental legal principles.

Step 3: Execute the Order

Once recognized, the foreign court will initiate enforcement actions, such as frozen bank assets or real estate foreclosures.

IV. Practical Legal Advice for Cross-Border Litigants

  • Coordinate Global Language Early: Inform your legal team immediately if your court documents need to be used overseas. This allows your attorneys to draft the settlement or proposed judgment with highly enforceable, clear-cut language (such as "a lump-sum offset of X Amount" rather than vague, ongoing custody and visitation terminology).
  • Budget Your Timeline: Expect the overseas recognition and enforcement process to take at least 6 months. Notarization, translation, legalization, and local judicial reviews take time.
  • Address Jurisdictional Discrepancies: Because countries apply different standards to property, debts, and child custody, any issues left unaddressed by your Chinese decree should be raised immediately with counsel in the foreign jurisdiction. This is particularly true for unallocated foreign assets, local child welfare benefits, or religious matrimonial requirements.

Conclusion

Cross-border divorces sit at the intersection of domestic family law, foreign civil procedures, and international judicial assistance. Because jurisdiction, service, global assets, and enforcement present highly technical hurdles, we recommend evaluating your domestic jurisdictional standing first. Secure your domestic assets and child custody arrangements within China, and systematically prepare your documents for foreign recognition to protect your global interests.

Disclaimer & Copyright: This article is co-authored by Mandy Wu and Yu Yuting. The insights shared are for general compliance trends only and do not constitute formal legal advice.As a specialized cross-border legal institution, Neo-Ark Law Firm provides comprehensive global compliance and rights-protection support for expanding enterprises. For more international legal updates, please visit the Neo-Ark Law Firm Official Websites (https://www.neoarklawyers.com/news).
Scroll to Top

+86 13503030053

BackToTop

Inquiry Inquiry Email Email Tel Tel

Request A Quote

×
Please enable JavaScript in your browser to complete this form.